Faced with the uncertainties surrounding retirement and the sustainability of Social Security, Individual Retirement Accounts (IRAs) are emerging as a great option for building a solid financial future.
But what is an IRA, and how does it really work? Let’s take a look at a key retirement tool.
What is an Individual Retirement Account?
An Individual Retirement Account (IRA) is a tax-advantaged retirement savings account that can be opened by anyone with an income. Unlike a 401(k), which depends on an employer, an IRA is managed directly by the saver, via a bank, brokerage firm or financial advisor. It allows you to invest in a wide range of assets like stocks, bonds, mutual funds, ETFs, etc.
IRAs are designed to encourage long-term savings for retirement, offering tax advantages either on entry or exit, depending on the type chosen.
Two main types: Traditional IRA and Roth IRA
IRAs come in several versions, but the most common are the Traditional IRA and the Roth IRA. Their main difference lies in their tax advantages.
Traditional IRA: The immediate tax advantage
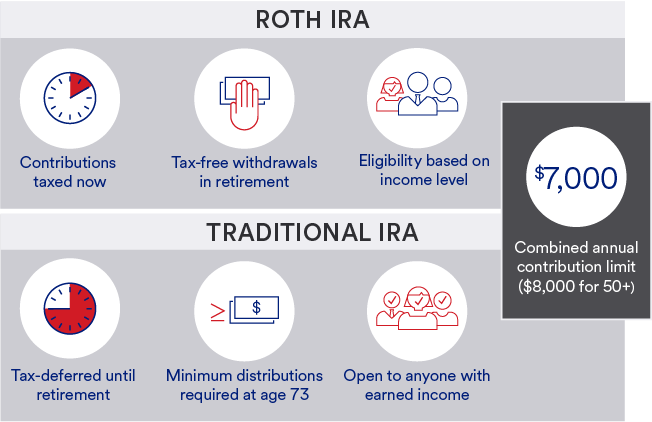
With a Traditional IRA, contributions may be tax-deductible (depending on your income and retirement coverage at work). On the other hand, withdrawals at retirement are taxed as ordinary income.
The major advantage is tax-deferred growth. Your investments grow tax-free until you withdraw them. This mechanism can lead to faster capital accumulation.
From age 73, holders are required to start making mandatory withdrawals, known as Required Minimum Distributions (RMDs).
Roth IRA: tax-deferred, withdrawals tax-free
The Roth IRA works in reverse. Contributions are made with money that is already taxed, but withdrawals at retirement are totally tax-free, provided certain conditions are met (being over 59½ years old and having held the account for at least five years).
Another advantage is that Roth IRAs are not subject to RMDs during your lifetime, making them an excellent inheritance or long-term tax planning tool.
Source: USBank
Contribution limits for IRAs
The IRS imposes contribution limits on all IRAs (Traditional + Roth combined). In 2025, the annual limit is set at :
- $7,000 for those aged under 50
- $8,000 with the catch-up contribution for those aged 50 and over.
Income limits also exist to determine eligibility for tax deductions (Traditional IRA) or to contribute to a Roth IRA. These thresholds vary according to tax status (single, married, etc.) and the presence of a retirement plan at work.
Why open an IRA, even when having a 401(k)?
Many people feel that their 401(k) is sufficient to prepare for retirement. But according to Fidelity, you'll need between 70% and 80% of your pre-retirement income to maintain your standard of living after you leave the workforce. Social Security only covers part of this amount, and 401(k)s often have limited investment options.
An IRA allows you to diversify your investments, complement a corporate plan and access more flexible tax planning strategies. You can also rollover from an old 401(k) to an IRA when you change employers, to consolidate and better manage your assets.
Withdrawal and tax rules
Withdrawing money from an IRA before age 59½ generally incurs a 10% penalty, in addition to applicable taxes (with exceptions, such as medical expenses or the purchase of a first home). That's why IRAs are designed for the long term.
A more comprehensive retirement planning
One option for an effectively planned retirement is to combine several sources of savings: 401(k), IRAs, taxable accounts and Social Security.
Having an IRA, whether traditional or Roth, allows you to balance the taxation of your future income and better manage your withdrawals according to your needs and tax bracket.
Whether you're employed, self-employed or an entrepreneur, Individual Retirement Accounts (IRAs) offer a solution for anticipating the future.
Their flexibility, accessibility and tax advantages make them a good tool for securing your retirement, especially at a time when the future of Social Security is uncertain and company plans are often no longer sufficient.
Information on these pages contains forward-looking statements that involve risks and uncertainties. Markets and instruments profiled on this page are for informational purposes only and should not in any way come across as a recommendation to buy or sell in these assets. You should do your own thorough research before making any investment decisions. FXStreet does not in any way guarantee that this information is free from mistakes, errors, or material misstatements. It also does not guarantee that this information is of a timely nature. Investing in Open Markets involves a great deal of risk, including the loss of all or a portion of your investment, as well as emotional distress. All risks, losses and costs associated with investing, including total loss of principal, are your responsibility. The views and opinions expressed in this article are those of the authors and do not necessarily reflect the official policy or position of FXStreet nor its advertisers. The author will not be held responsible for information that is found at the end of links posted on this page.
If not otherwise explicitly mentioned in the body of the article, at the time of writing, the author has no position in any stock mentioned in this article and no business relationship with any company mentioned. The author has not received compensation for writing this article, other than from FXStreet.
FXStreet and the author do not provide personalized recommendations. The author makes no representations as to the accuracy, completeness, or suitability of this information. FXStreet and the author will not be liable for any errors, omissions or any losses, injuries or damages arising from this information and its display or use. Errors and omissions excepted.
The author and FXStreet are not registered investment advisors and nothing in this article is intended to be investment advice.
Recommended content
Editors’ Picks
EUR/USD: The bears are winning, but something doesn't add up
The European currency has navigated another dreadful week, this time sending EUR/USD to the 1.0950 region for the first time since early April 2025. The pair’s severe retracement has exclusively followed the dynamics of the US Dollar (USD), which have mostly come in the form of increasing bets for further interest rate hikes by the Federal Reserve (Fed).
Gold: Hawkish Fed rhetoric, possible deleveraging weigh heavily on precious metal
Following a quiet start to the week, Gold (XAU/USD) came under heavy bearish pressure and fell to its lowest level since September 2025 near $3,500. After losing more than 6% in both September and October, the precious metal remains on track to end the third consecutive month deep in negative territory.
The Japanese Yen gains as Japan's inflation hits its highest since November 2025
USD/JPY retreats on Friday as the Japanese Yen (JPY) gains ground against the US Dollar (USD) following the release of Japan's latest inflation figures. The pair pulls back after approaching the psychological 160.00 level last week, a level that has renewed concerns about possible intervention by Japanese authorities.
Bitcoin: Storm not yet over
Bitcoin (BTC) extends its losing streak, dropping to $61,222 on Friday and heading toward a seventh consecutive week of losses as bearish pressure grips the broader crypto market. Persistent institutional outflows and leveraged liquidations are keeping BTC under pressure, while the hawkish tone of the Federal Reserve (Fed) leaves Crypto King vulnerable to further downside.

US Dollar: The Dollar is on fire. Its positioning? Not so much
The US Dollar (USD) maintained its march north well in place for the fourth consecutive week, sending the US Dollar Index (DXY) to the doorsteps of the key 104.00 hurdle for the first time since April 2025.
WTI falls to near $89.50 as Trump hints at reduced US-Iran tension
West Texas Intermediate oil price loses ground after remaining nearly flat in the previous day, trading around $89.60 during Asian hours on Monday. Crude oil prices fell following statements from US President Donald Trump indicating that further military strikes on Iran are "highly unlikely," provided there is significant progress in negotiations surrounding Iran's nuclear program and the reopening of the Strait of Hormuz.