Week ahead – Nonfarm Payrolls and US midterm elections take center stage
- US employment report to prove decisive for December Fed move.
- US midterm elections: Will markets cheer a divided Congress?
- RBA and BoE ready to press the hike button; focus to shift to guidance.
- Eurozone inflation data to clear the fog after the ECB decision.
Fed sounds less hawkish than expected, Warsh signals patience
The US dollar traded higher against most of its peers this week, beginning the week on a solid footing amid expectations of a hawkish FOMC decision on Wednesday. Although market participants were convinced that a rate hike was off the table, they were on the lookout for clues and hints on whether they were correct in nearly fully pricing in a 25bps rate hike in December.
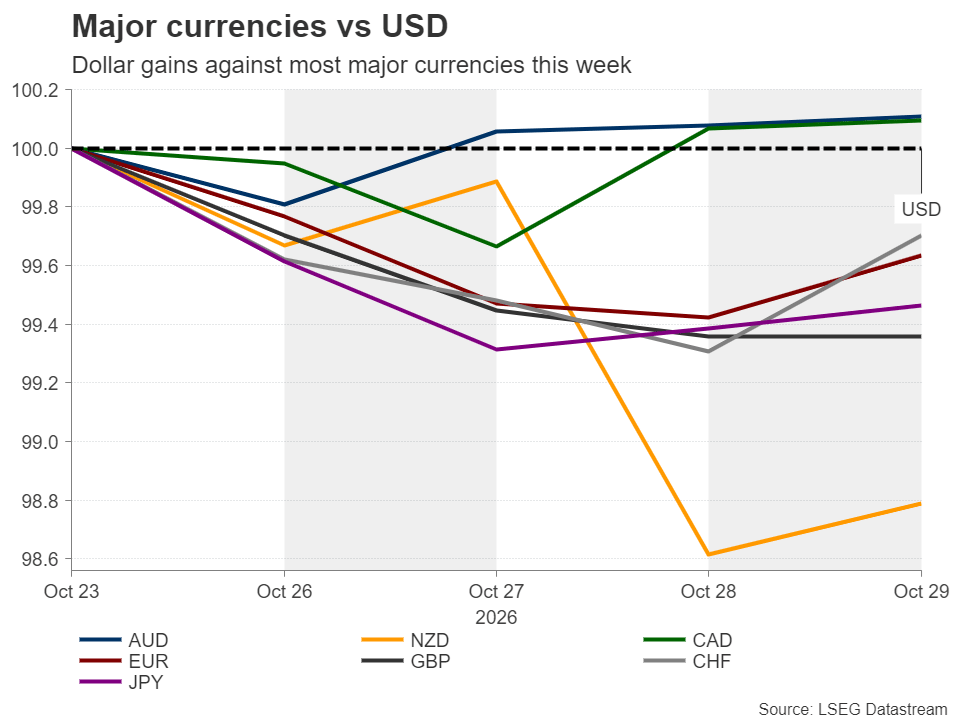
Investors were correct in anticipating no action at this gathering, but the hold was not as hawkish as they may have expected.
The statement did have a hawkish flavor, with policymakers upgrading their description of economic activity from “solid” to “strong”, and retaining the warning that inflation remains elevated. There were also two policymakers dissenting from the decision and voting for an immediate quarter-point increase.
Nonetheless, at the press conference, Fed Chair Kevin Warsh signaled patience as more data and information is needed before the next move. The market response was a retreat in Treasury yields and a pullback in the US dollar as a December hike was far from sealed.
NFP to prove decisive on whether the Fed will hike in December
Still, the probability of such action remained elevated at around 80%, which means that if next week’s data, especially the nonfarm payrolls report, comes in strong, investors could seal the deal for December, and add some more basis points worth of rate hikes for 2027. They now see the Federal funds rate being around 70bps higher by the end of next year.
Nonfarm payrolls disappointed largely in September, with employment slowing to 29k from 133k in August, and missing the forecast of 90k. However, according to the flash S&P Global composite PMI, hiring in the manufacturing and services sectors was the second-fastest since 2022, which combined with the lower prints of initial jobless claims during the month, tilts the risks of next week’s release to the upside.
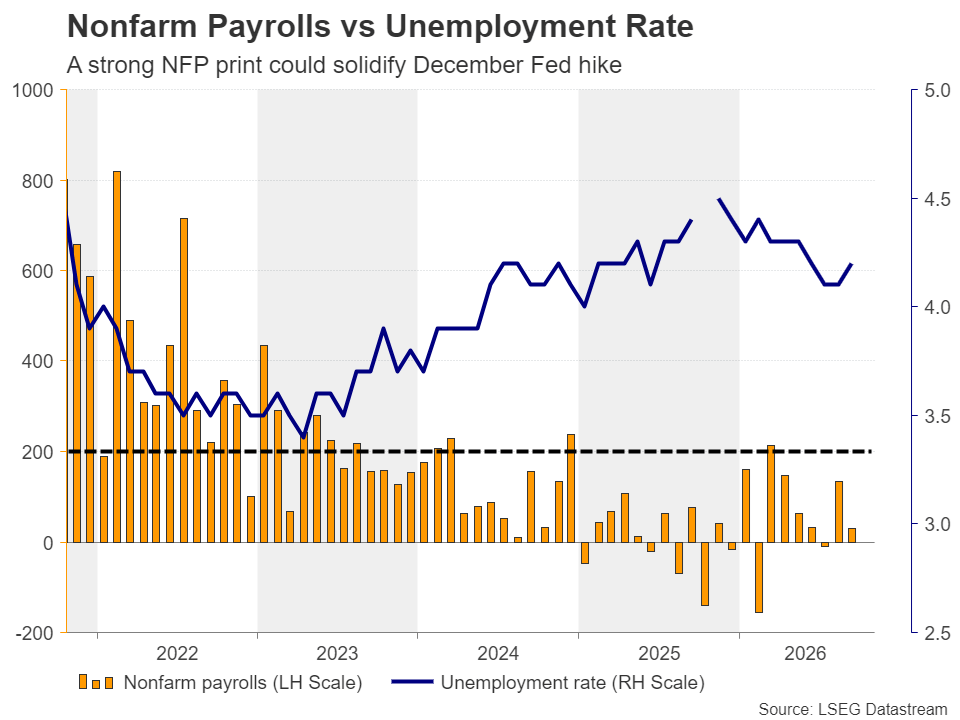
The ISM manufacturing PMI on Monday, the ISM services index on Wednesday, and the ADP private employment report, also on Wednesday, could provide more information about how the US labor market had fared during October.
US midterms: Red wave, Blue sweep, or stalemate?
Nonfarm payrolls are not the only big event on next week’s agenda. On Tuesday, US citizens will head to the polls for their midterm elections. Investors’ angst is whether the US Congress will shift from unified Republican control to a divided government. Democrats are expected to claim the House, but whether they succeed in the Senate remains a close call.
A Democratic House and a Republican Senate would mean that Democrats will have investigative powers, push for more regulatory compliance for banks, crypto and technology firms, but Trump would retain veto power and executive authority over tariffs, immigration and foreign policy, limiting legislative change. A Democratic sweep would strengthen oversight, allowing Democrats to block nominees and control committees, but presidential veto would still constrain policy.
On the other hand, continued Republican control could reduce near-term budget friction and support defense and deregulation themes, while reinforcing tariff and deficit concerns.
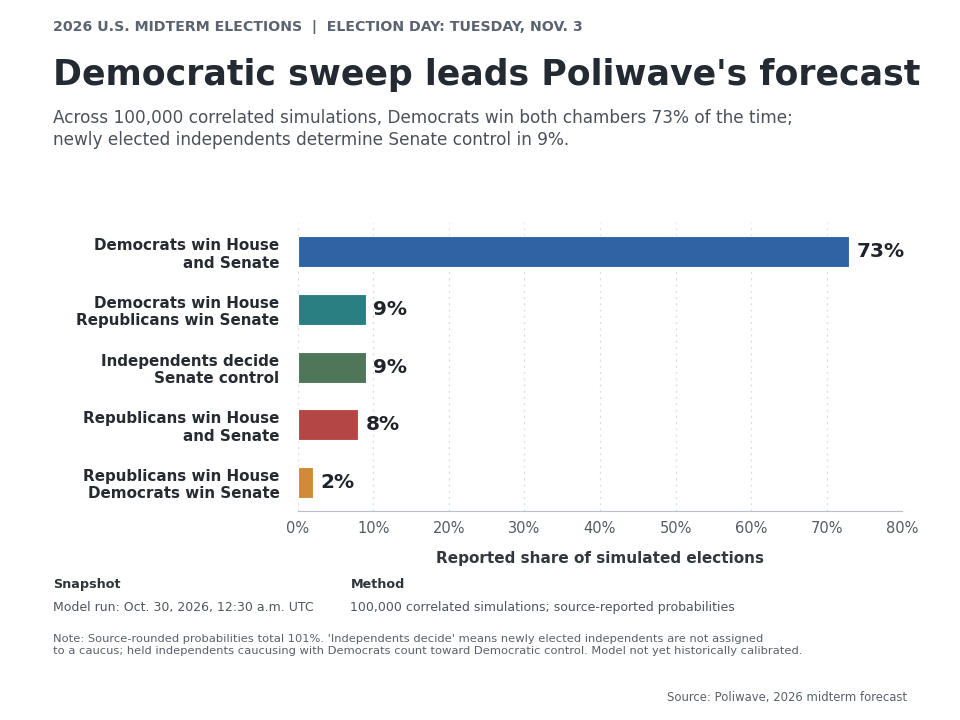
In terms of the market response, a Democratic sweep could be negative for US equities, reflecting expectations of stronger oversight and regulation, while Treasury yields and the dollar could slide on expectations of tighter fiscal policy and slower growth. A Republican sweep could also be negative for Wall Street amid renewed anxiety that Trump could pursue more protectionist policies, but Treasury yields and the dollar are likely to rise as concerns about fresh tariffs could translate into heightened fears about inflation remaining elevated and thereby expectations of more rate hikes next year.
The most market-friendly outcome may be a Democratic House and a Republican Senate. Legislative gridlock would restrict major tax, spending and regulatory changes. Wall Street could edge higher as uncertainty fades, with investors shifting attention back to the earnings season. Treasury yields and the dollar could ease somewhat as democrats will have more power in opposing some of Trump’s protectionist policies.
RBA to hike, but the Aussie needs more
Outside the US, we have two central banks deciding on monetary policy: The Reserve Bank of Australia on Tuesday and the Bank of England on Thursday.
Getting the ball rolling with the RBA, Australian policymakers decided to raise interest rates by 25bps at their latest meeting on September 29 amid increased concerns about persistently elevated inflation, adding that they remain ready to tighten policy again if deemed necessary.
The monthly CPI data for September, released on October 28, revealed that headline inflation accelerated to 4.3% year-on-year from 4.0% in August, while the trimmed mean rate ticked up to 3.6% y/y from 3.5%. With both rates hovering well above the upper bound of the RBA’s inflation target range of 2-3%, investors are now assigning a strong 85% chance of another 25bps hike at Tuesday’s meeting.
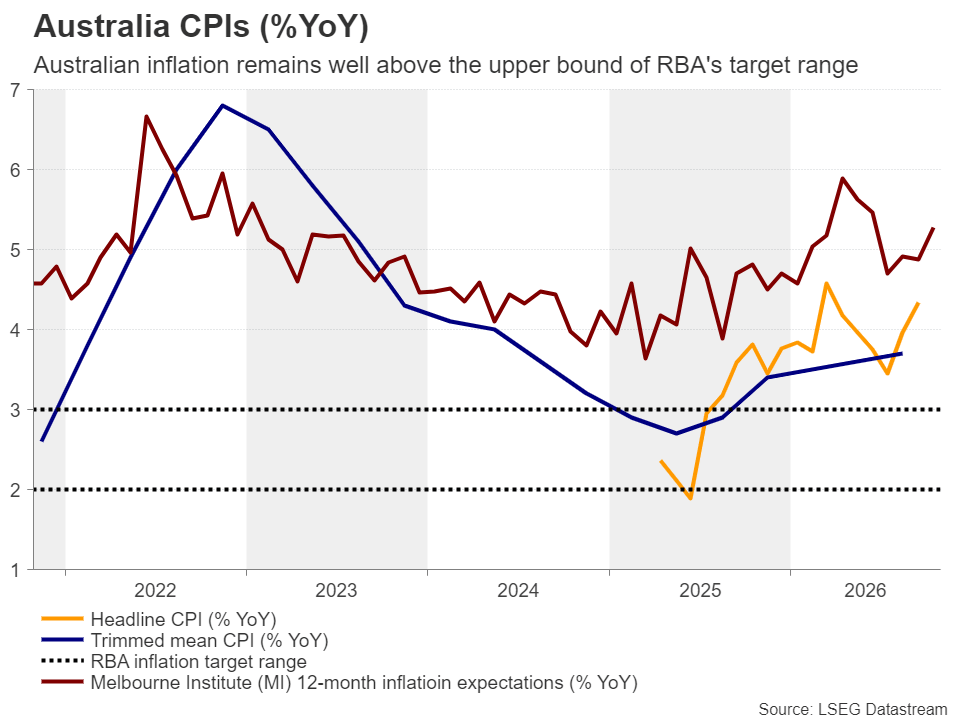
However, there is only a 50% chance that the RBA will hike again in 2027. Therefore, for the aussie to gain ground after the decision, a hike alone may not be enough. Policymakers may need to appear hawkish enough to convince market participants to start penciling in more rate increases for next year.
First BoE hike since August 2023
Passing the ball to the BoE, this Bank remained sidelined in September, but the decision revealed a growing hawkish split, with three members voting for a rate hike. Although this was the sixth consecutive hold, a 25bps increase is now fully priced in for this gathering.
UK inflation accelerated to 3.5% y/y in September, further above the BoE’s objective of 2%, solidifying the case for the Bank’s first increase since August 2023. Therefore, the pound is unlikely to be driven by the hike itself, rather than by the vote, the updated economic projections and the guidance on further tightening. A unanimous vote for an increase, upwardly revised inflation projections and strong willingess to continue with more rate increase could add fuel to sterling’s engines.
EZ inflation awaited after ECB’s wait-and-see stance
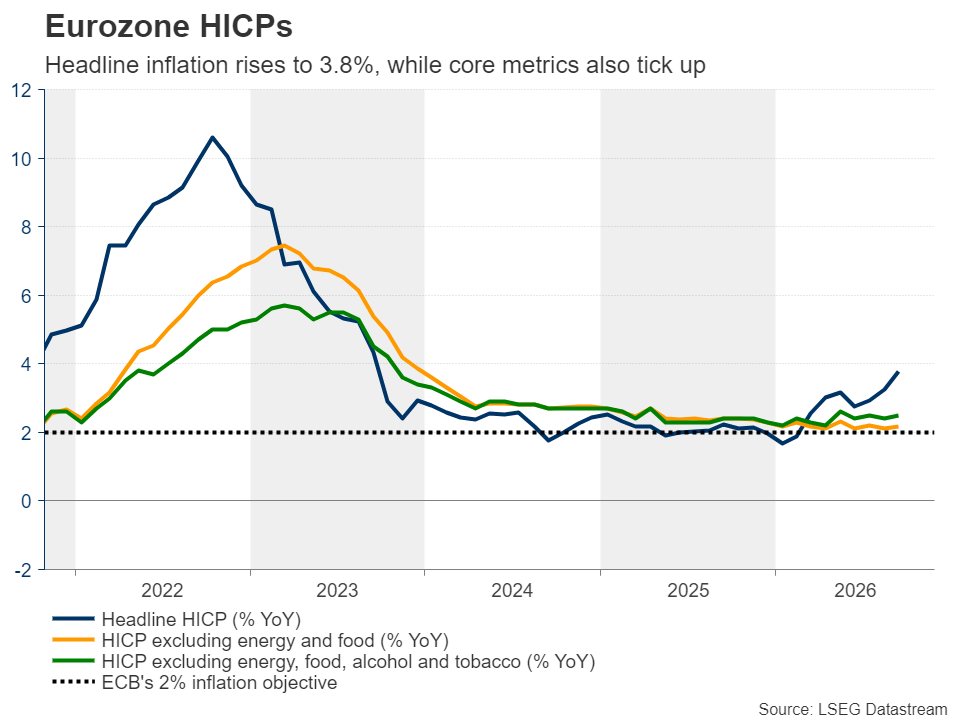
Elsewhere, Eurozone’s flash inflation data for October will be released on Wednesday and may be of more importance than usual after the ECB remained on hold this Thursday, with Christine Lagarde noting that policymakers debated whether a rate hike was warranted before opting for a wait-and-see stance.
Although officials remained concerned about the upside risks to inflation amid the energy crisis stemming from the Middle East, they also emphasized the downside risks to growth. That’s why they explicitly reiterated that they are not pre-committing to any trajectory, leaving all the cards on the table for December.
According to Euro-area’s money markets, there is a 65% chance of a rate hike in December and another data set pointing to sticky inflation could take that number higher and thereby help somewhat the wounded euro.
New Zealand and Canadian jobs, earnings season continues
New Zealand’s employment report for Q3 will be released during the Asian session Wednesday, while at the same time with the US nonfarm payrolls, dollar/loonie traders will have to digest the Canadian employment report for October.
As for the earnings season, Apple, Palantir and ON Semiconductor announce results on Monday after the closing bell, AMD reports Tuesday, and Qualcomm on Wednesday. With concerns about massive spending and borrowing by tech giants to finance their AI projects, disappointing results could inflict deep wounds on Wall Street.
Author

Charalampos joined Trading Point in August 2022 as a senior market analyst. He has extensive experience in analyzing financial markets, gained through a decade-long career, with his primary focus being on the currency market.