It’s looking like the wishful thinking of the peak high crowd is not totally nuts, after all

Outlook: We were in the throes of risk appetite run amuck yesterday when the market decided the ECB rate hike was the last hike and the rumor hit that the Bank of Japan was, at last, adopting a more hawkish policy.
Everyone knew in a flash this puts over $3 trillion of foreign investments at risk of repatriation. In a classic contamination, the euro crashed 155 points in three hours, taking the pound along with it. Oddly, while this was going on, the US had just reported Q2 GDP at 2.4%, much higher than 1.8% forecast, and along with it, something named the price index for gross domestic purchases.
This inflation measure rose at a 1.9% rate, the slowest in three years, after 3.8% in Q1. Reuters reports the core PCE rose at a rate of 3.8% from 4.9% in Q1. Mind you, these are the quarterlies. We get the PCE deflator for July this morning. After that, the various Feds will release their adjusted versions, including the St. Louis Fed’s trimmed mean PCE.
Remember the comment from the day before from Jim Bianco that if we expect the Fed’s hike this week to be the last, we need the new core PCE inflation rate to have a 3 in front of it. The forecast up to now has been 4.2% (from 4.6%).
As we wrote yesterday, the Fed will have stopped hiking before core PCE gets to 2%. We just don’t know how big the wiggle room is going to be. It might even be 3% or 3.5%. We agree with Bianco—the only thing to pay attention to is PCE core inflation and we can forget all the other data. When core PCE is nearing 2%--not at it, but headed that way and close to it—the Fed will relent.
It’s looking like the wishful thinking of the peak high crowd is not totally nuts, after all. The probability of additional hikes in the fall is not zero, but at the same time, the probability of a pause is now much higher.
As for the tiny tweak in policy at the Bank of Japan, the seemingly outsized response is not inappropriate. There really is over $3 trillion in Japanese-owned assets outside of Japan at risk of getting dumped and the money repatriated. It’s going to take some time for this to sink in, let alone be reflected in FX rates. We can easily imagine the dollar/yen sliding back down to 105-110, where it spent most of 2019-2020. But it won’t be a straight line—it never is—because this is a winding road. Even if the JGB rises a bit from 1%, the US will have 4% or more and that favorable differential, plus better growth and more variety in investment opportunities, will not shove the dollar into the basement.
Forecast: There’s nothing like FX to make you eat crow two days in a row. No sooner do we succumb to the crowd and admit risk-on is running the show at the dollar’s cost than we get a big, fat correction in the euro inspired by events halfway around the world. The word ”event” is not even accurate—the BoJ spoke of the new 10-year bond cap at 1% as a suggestion rather than a rigidi limit. It doesn’t get any more minor than this, but the message is huge. The immediate response is not going to be the lasting one and never before has our advice to close positions ahead of the weekend been more sincere. We expect the euro and pound to recover and resume the upward move, but it will take a long time before we know for sure the dollar/yen will fade below the previous low (137.23 from July 13).
Note to Readers: We will take next week off and not publish any reports. We will have access to e-mail if you want to write.
Tidbit: We finally get the core PCE inflation today. It’s still sticky. Most recently it was 4.62%, lower than the month before, but it was 4.88% the year before. It is expected to come in at 4.2% today. For perspective, see the one-year core PCE vs. the 5-year. Still think the Fed will relent. Remember the charts the next time someone says “higher for longer” is a dead duck and we have reached “peak rates.”
If the Fed is well and truly data-dependent, we have not reached “peak rates.” The only excuse for making the peak rate assumption is that at the Sept meeting, the Fed might identify the trend trajectory as headed below 3% and that justifies another pause. We know that the Fed will quit before 2% on the dot. But it’s not The End until we see the whites of 2% eyes. Where is that? Not anything over 4%. It has to be in the low to mid 3’s at the very least, and maybe under 3%.
Tidbit: News junkies are avidly following the Trump indictments saga. Yesterday he got hit with a few more federal crimes in the Mar-a-Lago indictment. The list of crimes for which Trump has been indicted or is expected to be indicted is going to number over 50 before all is said and done.
The evidence available to the public is overwhelmingly in favor of a guilty verdict in all the cases, although you never know with a jury that might have a secret Trumper. And the trials are way off in the future and overlapping with or later than important Republican party events (debates, primaries). Still, the stink of crime is starting to cling to Trump.
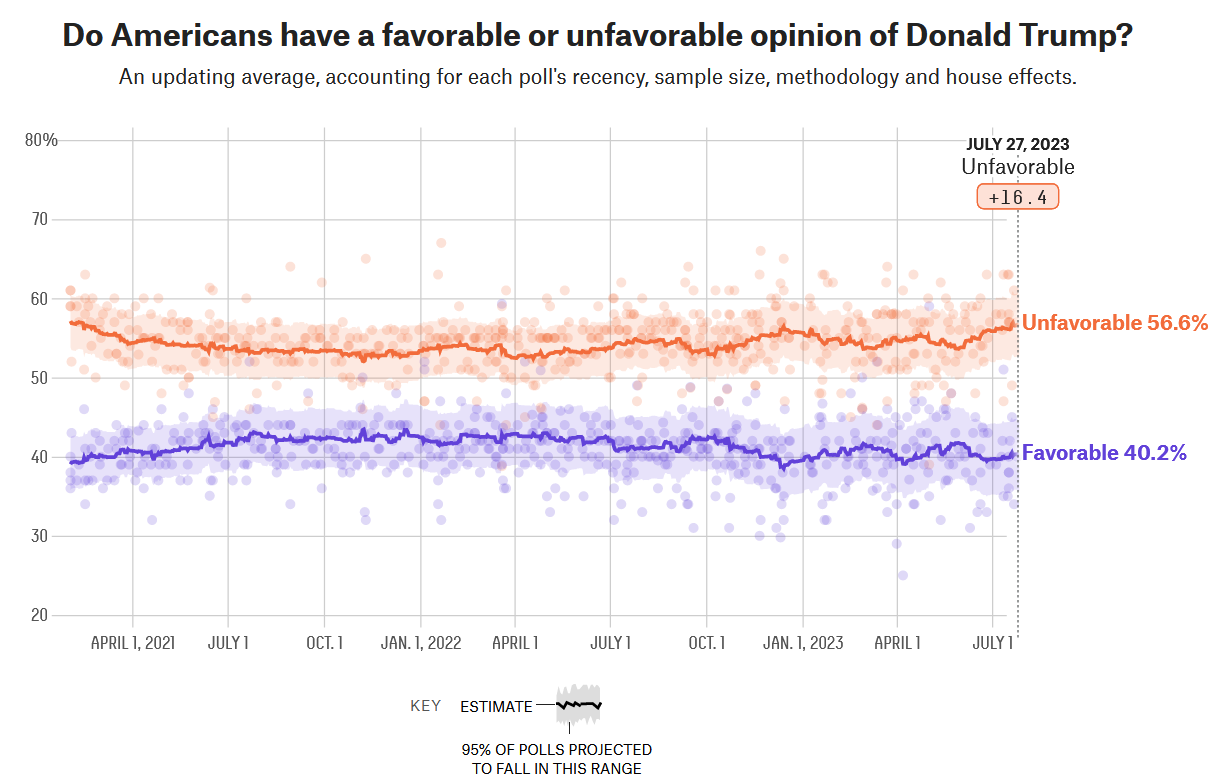
While the State of Georgia was painfully and slowly building its case, the first political development was the FBI raid on Mar-a-Lago that delivered stolen national security documents. Trump’s popularity rose on his witch-hunt rhetoric, and he collected millions from the suckers in the cornfields. But now that we have the guilty verdict in the Trump Organization and Carroll trials, and the other cases are in the works, Trumps’ favorability is falling.
The latest Pew survey shows 63% of Americans of all political affiliations have an unfavorable opinion of Trump, up from 60% last year. Among Republicans, 66% have a favorable view, down from 75% last July. No surprise, 91% of Democrats view him unfavorably.
The 538.com collection of polls has the unfavorability rate at 56.6% and the favorable at 40.1%, or 16.5% against vs. 13.4% at end-July a year ago. You can scroll the chart to see the changes. 538.com has changed its statistical methodology from what it used in the 2020 election, but we still wonder whether aggregation is useful.
It might be overreaching to deduce that the American public really doesn’t favor an indicted and/or convicted criminal as leader of one of only two parties, let alone president. But it’s gratifying to think the public is not so stuck to party loyalty or so opposed to the Dems, or so factually deficient, that they would actually re-elect this guy.
Conviction of some of the crimes with which Trump is charged means a jail sentence. Nobody knows how that would work—does it mean some Secret Service guards would have to be seconded to the prison? Or does it mean he would get an ankle bracelet and home confinement? An airplane might be for sale.
Historically, US politics tend to have very little effect on FX. A test was the first US government shutdown, supposedly over the budget issue, when Clinton was president in the 1990’s. It was really because Speaker Gingrich got a bug up his nose. But the dollar barely burped. The first time we saw US politics meaningfully affect the dollar was the Trump years, when the rise in risk from this incompetent mismanager supported the dollar, a classic FX perversion. If Trump were to get re-elected, we’d expect to see the same response—far higher global risk, dollar up. At this point in time, over a year ahead of the Nov 2024 election, Trump’s chances are going down the tubes. But this is breathing room and not final.
This is an excerpt from “The Rockefeller Morning Briefing,” which is far larger (about 10 pages). The Briefing has been published every day for over 25 years and represents experienced analysis and insight. The report offers deep background and is not intended to guide FX trading. Rockefeller produces other reports (in spot and futures) for trading purposes.
To get a two-week trial of the full reports plus traders advice for only $3.95. Click here!
Author

Barbara Rockefeller
Rockefeller Treasury Services, Inc.
Experience Before founding Rockefeller Treasury, Barbara worked at Citibank and other banks as a risk manager, new product developer (Cititrend), FX trader, advisor and loan officer. Miss Rockefeller is engaged to perform FX-relat