BoJ preview: Hawkish hold
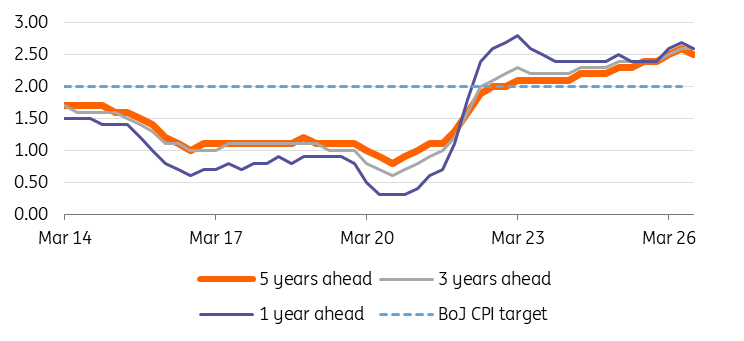
Price expectations well above 2%
Having hiked rates by 25bp to 1.25% in September, the central messages from the BoJ were largely similar; upside price risks remained, real interest rates were still negative and further policy rate hikes should be expected.
Perhaps the only reason that a rate hike is not expected at this 30 October meeting is that the BoJ has never delivered back-to-back rate hikes since it was given monetary policy independence in 1998. A hike in October could therefore smack of urgency.
Behind a widely expected unchanged decision will be a focus on the voting pattern. Did arch-hawk Hajime Takata again dissent in favour of back-to-back hikes? His vote for a hike would not be a surprise. Anyone joining him would.
More interest will be had in the October outlook report. The July report was pretty hawkish in that the median forecast for core (all items less food and energy) inflation for FY27 and FY28 were 2.6% and 2.2%, respectively. Let’s see how they change in the new release.
Perhaps one comfort for the BoJ is that inflation expectations do not seem to have worsened. The September Tankan report showed business expectations for inflation fractionally dipping from the highs, with PPI also showing early signs of topping out.
BoJ Tankan price expectations stabilise
Market reaction
Markets currently price in an 80% chance of a 25b rate hike in December and then another 50bp by next September. While government representatives may well want the BoJ to go slow with its tightening, the case against the BoJ taking rates up to the 1.75-2.00% area is a weak one. Here the BoJ remains concerned with a weak yen, broadening AI demand and elevated energy prices.
There does not seem an obvious case for a big move in market rates or the yen on the back of Friday’s BoJ decision. A hawkish Fed keeping USD/JPY bid in a broad 157-159 range into year-end is our current view.
One low-probability, high-impact risk for Friday is any announcement from Japan’s GPIF pension on re-allocating funds domestically. One of the most memorable adjustments in those allocations was made on the same day as the BoJ’s policy decision in October 2014.
Reports since the summer have tended to play down the prospects of an allocation shift, and market attention has drifted away from this subject. Any surprise announcements here could trigger a sub-155 move in USD/JPY.
Author

Chris Turner
ING Economic and Financial Analysis
Chris is Head of FX Strategy at ING. Together with his team, he provides short and medium-term FX recommendations for ING’s corporate and institutional client base.