USD/CAD Price Forecast: Sees a sizeable downside below 1.3500
- USD/CAD faces selling pressure as the US Dollar underperforms in the aftermath of the US NFP data.
- Private sector hiring slowed significantly, while public sector hiring proved surprisingly robust.
- The imposition of higher tariffs by the US on Canada will dampen the outlook for the Canadian Dollar.
The USD/CAD pair trades lower to near 1.3570 during the European session on Friday, aiming to revisit the eight-month low around 1.3540. The Loonie pair faces selling pressure as the US Dollar (US) gives back its entire gains in the aftermath of the United States (US) Nonfarm Payrolls (NFP) data for June, released on Thursday.
The US Dollar Index (DXY), which tracks the Greenback’s value against six major currencies, slides below 97.00.
According to the NFP report, strong labor hiring by the public sector led to a sharp increase in the overall job data, while private sector hiring slowed significantly. Overall workers added in June were 147K, higher than estimates of 110K. However, job-seekers hired by private employers were 74K, almost half of 137K recorded in May, and way below if compared to the three-month average of 115K.
Although investors have underpinned the Canadian Dollar (CAD) against the US Dollar, it is underperforming other peers amid uncertainty surrounding the July 9 tariff deadline. The Canadian economy has not yet finalized any trade agreement with the US and is likely to face higher tariffs from next week.
Canadian Dollar PRICE Today
The table below shows the percentage change of Canadian Dollar (CAD) against listed major currencies today. Canadian Dollar was the weakest against the Japanese Yen.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.19% | -0.16% | -0.39% | -0.09% | 0.08% | -0.04% | -0.32% | |
| EUR | 0.19% | 0.06% | -0.17% | 0.14% | 0.16% | 0.15% | -0.09% | |
| GBP | 0.16% | -0.06% | -0.26% | 0.07% | 0.11% | 0.09% | -0.15% | |
| JPY | 0.39% | 0.17% | 0.26% | 0.32% | 0.34% | 0.29% | -0.02% | |
| CAD | 0.09% | -0.14% | -0.07% | -0.32% | 0.01% | 0.01% | -0.22% | |
| AUD | -0.08% | -0.16% | -0.11% | -0.34% | -0.01% | -0.06% | -0.26% | |
| NZD | 0.04% | -0.15% | -0.09% | -0.29% | -0.01% | 0.06% | -0.23% | |
| CHF | 0.32% | 0.09% | 0.15% | 0.02% | 0.22% | 0.26% | 0.23% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Canadian Dollar from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent CAD (base)/USD (quote).
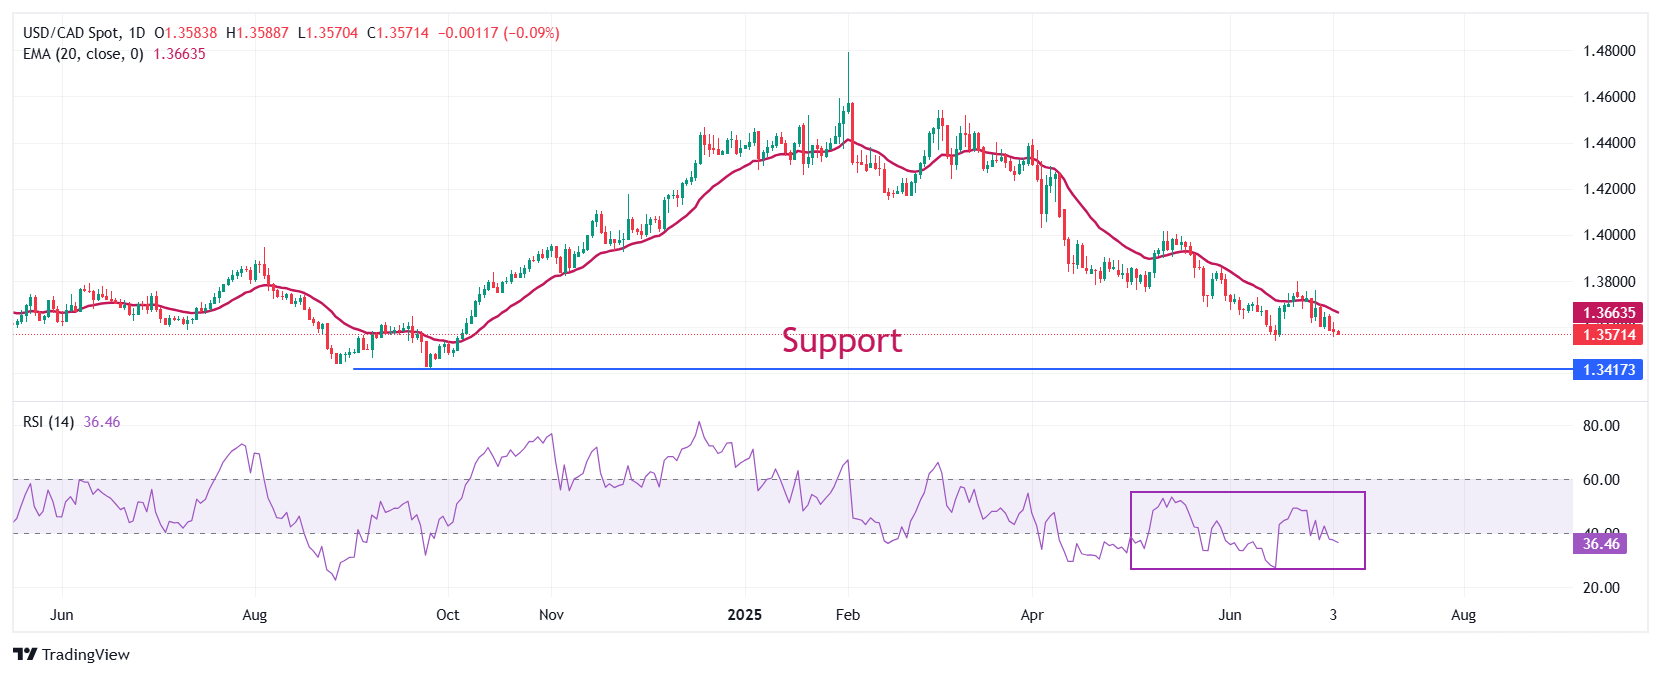
USD/CAD continues to face selling pressure at every attempt above the 20-day Exponential Moving Average (EMA), suggesting a “Sell on Rise” trend. The 14-day Relative Strength Index (RSI) slides below 40.00, suggesting that a fresh bearish momentum has triggered.
Going forward, the asset could slide towards the psychological level of 1.3500 and the September 25 low of 1.3420 if it breaks below the June 16 low of 1.3540.
On the contrary, an upside move by the pair above the May 29 high of 1.3820 would open the door towards the May 21 high of 1.3920, followed by the May 15 high of 1.4000.
USD/CAD daily chart
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.

















