US Treasury yields ease after 30-year hits 19-month high on US deficit fears
- 30-year yield hit 5.15% before pulling back to 5.05% amid deficit worries.
- Trump's budget plan passes House by one vote; Senate showdown next.
- Despite lower yields, US Dollar climbs as markets brace for inflationary risks.
US Treasury yields retreated on Thursday after the 30-year US bond yields reached their highest level in 19 months amid concerns regarding the increase of the US fiscal deficit, as Trump's “One Big Beautiful Bill” passes the US House of Representatives and is on its way to the Senate.
Long-end Treasury yields retreat as Trump’s tax-heavy budget clears House, pushing fiscal concerns to the forefront
The US House of Representatives approved Trump’s budget by one vote on Thursday. The proposal, which will deliver tax breaks on tips and car loans –manufactured in the USA–is expected to increase the deficit by $3.8 billion, according to the Congressional Budget Office (CBO).
The US 30-year Treasury bond yield hit 5.15% during the trading session, its highest level since November 2023, but it has retreated to 5.05% so far, down three points (bps) from its opening level.
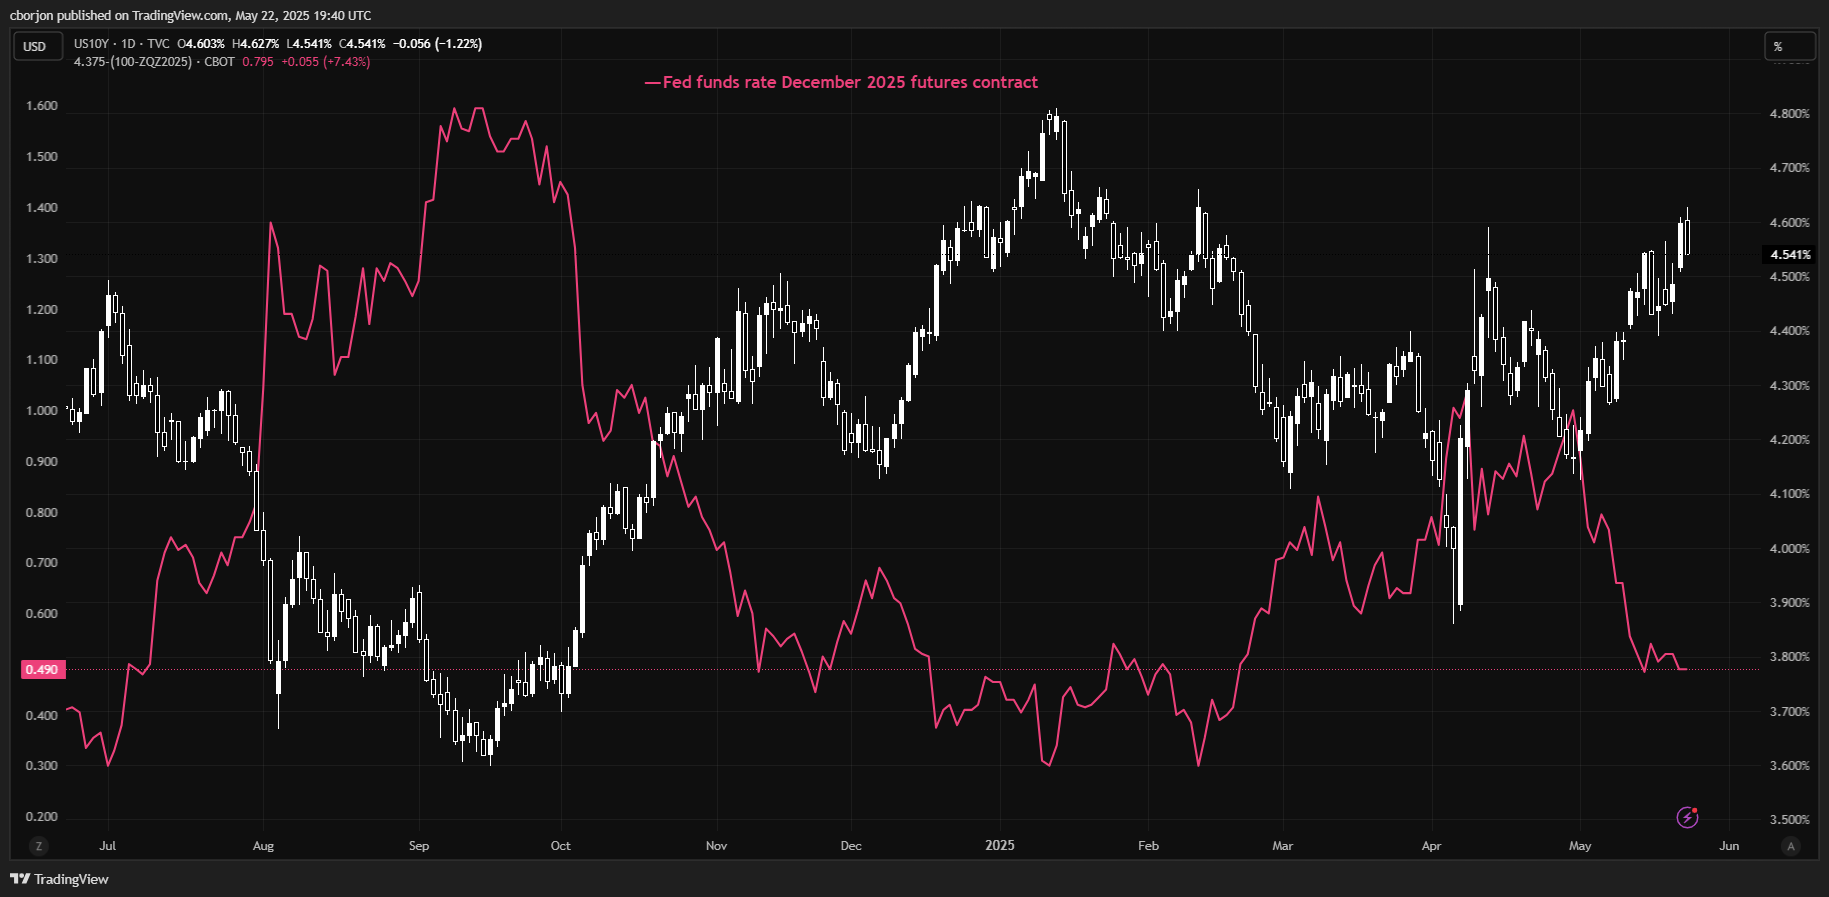
The yield of the US 10-year benchmark note is at 4.545%, down five bps. Nevertheless, the US Dollar Index (DXY), which measures the buck’s value against a basket of six currencies, shrugged off falling US yields and climbed 0.26% to 99.95 at the time of writing.
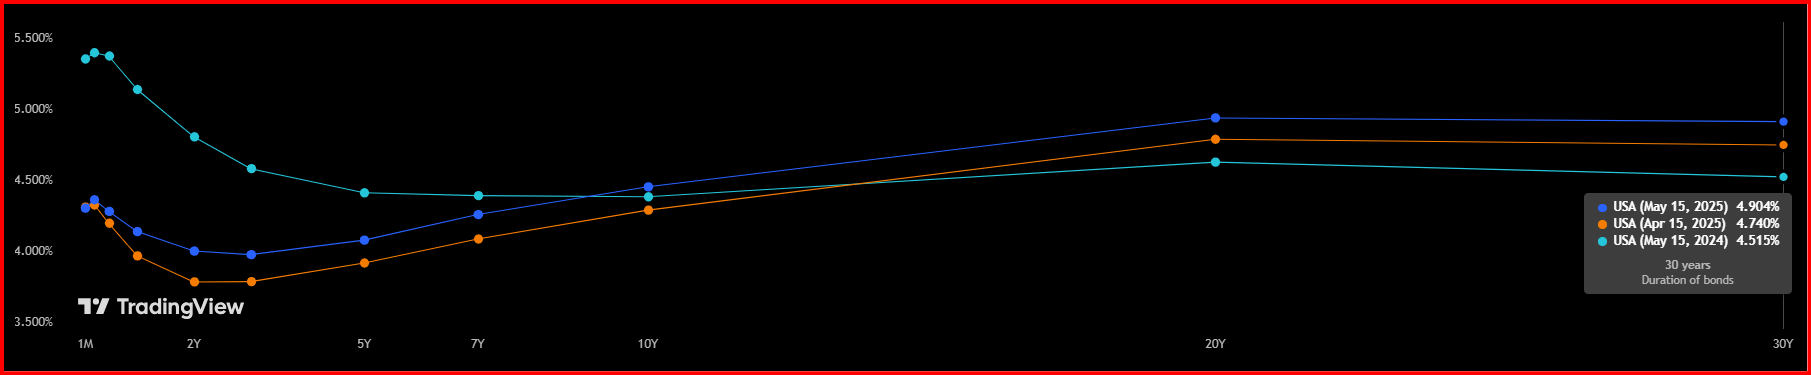
Moody’s downgraded US government debt from AAA negative to Aa1 stable last week, triggering a spike across the US yield curve.
US President Donald Trump's unpredictable economic policies triggered a jump in Treasury yields across the curve. Tariffs are seen as inflation-prone, and the increase in the US fiscal deficit continues to pressure the bond market.
US 10-year yield vs. Fed funds rate December 2025 easing expectations
Source: Tradingview
US Yield curve
Source: Tradingview
Interest rates FAQs
Interest rates are charged by financial institutions on loans to borrowers and are paid as interest to savers and depositors. They are influenced by base lending rates, which are set by central banks in response to changes in the economy. Central banks normally have a mandate to ensure price stability, which in most cases means targeting a core inflation rate of around 2%. If inflation falls below target the central bank may cut base lending rates, with a view to stimulating lending and boosting the economy. If inflation rises substantially above 2% it normally results in the central bank raising base lending rates in an attempt to lower inflation.
Higher interest rates generally help strengthen a country’s currency as they make it a more attractive place for global investors to park their money.
Higher interest rates overall weigh on the price of Gold because they increase the opportunity cost of holding Gold instead of investing in an interest-bearing asset or placing cash in the bank. If interest rates are high that usually pushes up the price of the US Dollar (USD), and since Gold is priced in Dollars, this has the effect of lowering the price of Gold.
The Fed funds rate is the overnight rate at which US banks lend to each other. It is the oft-quoted headline rate set by the Federal Reserve at its FOMC meetings. It is set as a range, for example 4.75%-5.00%, though the upper limit (in that case 5.00%) is the quoted figure. Market expectations for future Fed funds rate are tracked by the CME FedWatch tool, which shapes how many financial markets behave in anticipation of future Federal Reserve monetary policy decisions.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















