US Dollar flat ahead of weekend full of uncertainties over France's budget
- The US Dollar off the lows for this Friday with markets nervous on France's budget talks possibly toppling the government.
- Monday's opening might get choppy if French Prime Minister Michel Barnier is unable to secure a deal with the far-right National Rally party.
- The US Dollar Index is back above 106.00 and is looking for a daily and weekly close above the level to secure more upside into next week.

The US Dollar (USD) is recovering with the US trading session opening on Black Friday. The rally in the Euro which was weighing on the US Dollar and the US Dollar Index (DXY), is fading at the start of the US trading session.
France’s budget talks are not going well, with Prime Minister Michel Barnier having to consent to too many demands from the far-right National Rally from Marine Le Pen. The budget concerns are sending French yields higher, to levels matching weaker European peripheral countries such as Greece, fueling a stronger Euro over the US Dollar.
Meanwhile, US financial markets will close early on Friday after Thanksgiving Day. US equity futures are trading flat while the US bond market opens up under thin liquidity.
Daily digest market movers: France to sink or save Euro on Monday
- Far-right National Rally leader Marine Le Pen, who holds outsize leverage in France’s split parliament, gave Prime Minister Michel Barnier until Monday to kneel to her budget demands before she decides whether to topple the government, Bloomberg reports.
- Prime Minister Barnier already agreed to abandon plans to raise taxes on electricity on Thursday, Reuters reports.
- Equities are set to close off this Friday with some slim gains for both Europe and the US despite thin liquidity this Black Friday.
- The CME FedWatch Tool is pricing in another 25 basis points (bps) rate cut by the Fed at the December 18 meeting by 66.3%. A 33.7% chance is for rates to remain unchanged. The Fed Minutes have helped the rate cut odds for December to move higher.
- The US 10-year benchmark rate trades at 4.19%, falling to this week’s low at the start of this Friday after being closed on Thursday.
US Dollar Index Technical Analysis: DXY gears up for final weeks of 2025
The US Dollar Index (DXY) faces some more selling pressure on Friday, with one of its main components, the Euro, weighing the Index down. With the uprising in French yields and spreads, the rate gap between the US and Europe gets narrower, with the Euro catching up with the US Dollar. Pivotal support levels need to be identified, with the “Trump trade” set to pick up soon again as President-elect Donald Trump takes office in January.
With this week’s decline in the DXY, former support levels have now turned into resistance. On the upside, 106.52 (April 16 high) is the first level to watch. Should the Dollar bulls reclaim that level, 107.00 (round level) and 107.35 (October 3, 2023, high) are back on target for a retest.
If the DXY correction continues, the pivotal level at 105.53 (April 11 high) comes into play on Friday as the last man standing before heading into the 104-region. Should the DXY fall all the way towards 104.00, the big figure and the 200-day Simple Moving Average at 104.03 should catch any falling knife formation.
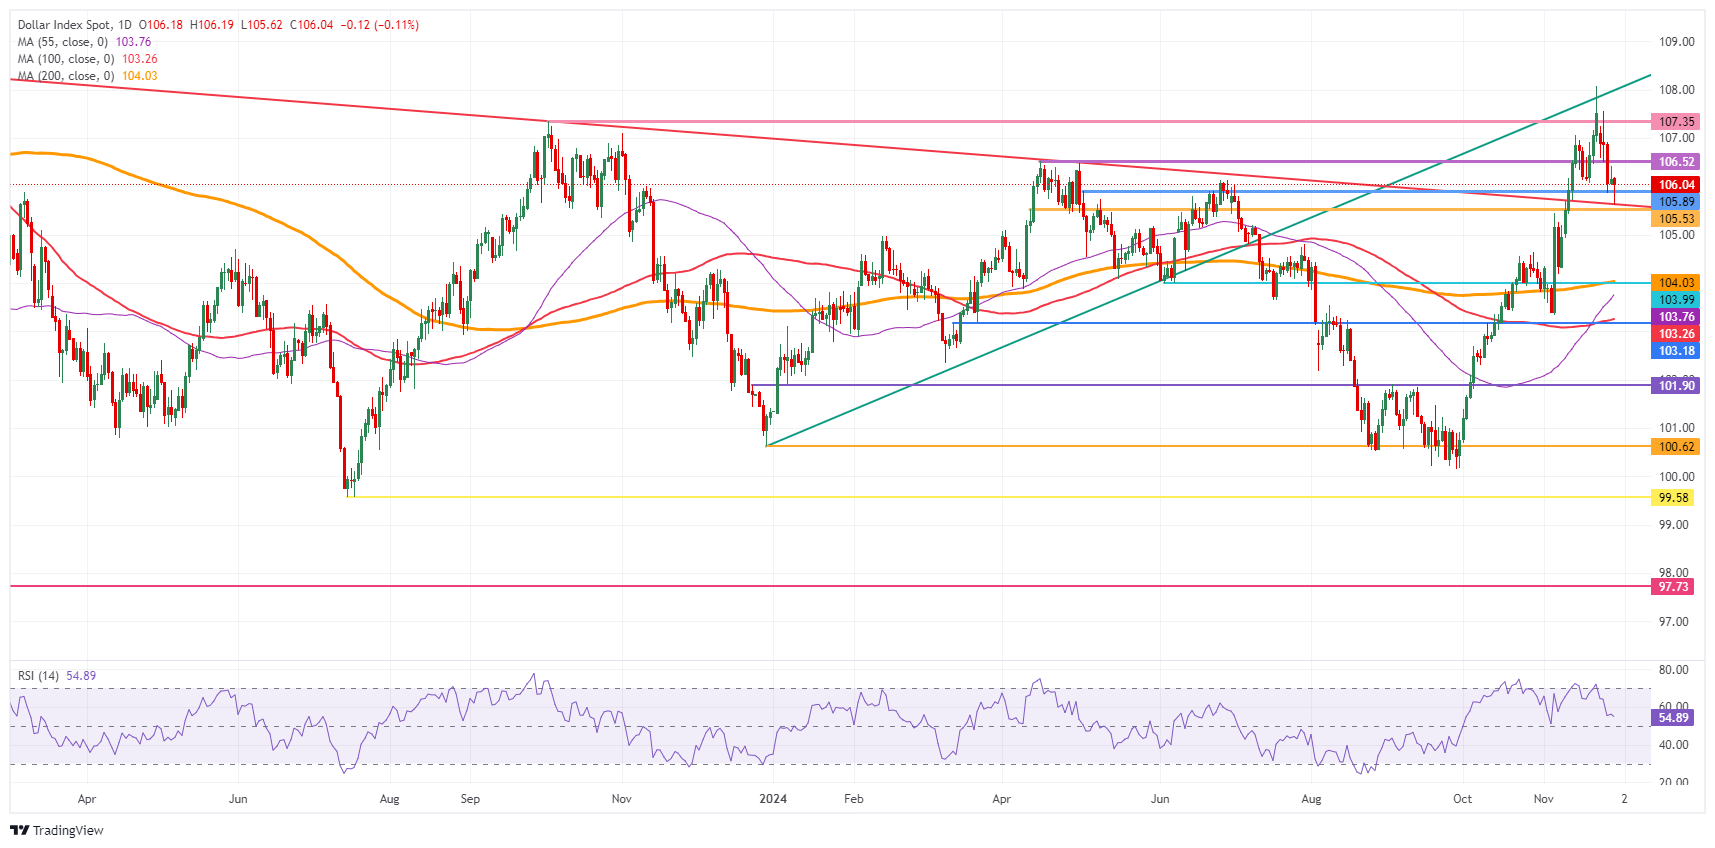
US Dollar Index: Daily Chart
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
Author

Filip Lagaart
FXStreet
Filip Lagaart is a former sales/trader with over 15 years of financial markets expertise under its belt.