US Dollar Index has volatile ride after 10% tariff sticks despite trade deal for UK
- The US Dollar Index turns flat ahead of US trading session with euphoria fading on US-UK trade deal.
- CNN reports that 10% tariffs will remain in place for the UK despite its brokered trade deal with the US.
- The US Dollar Index faces a rejection and turns flat below 100.00 ahead of the US trading session this Thursday.

The US Dollar Index (DXY), which tracks the performance of the US Dollar (USD) against six major currencies, trades flat and dips back below 100.00 before the upcoming announcement by Donald Trump on a “major trade deal” between the United States (US) and, reportedly, the United Kingdom (UK). The euphoria is fading quick now after CNN reported that the 10% tariff for the UK would remain in place, despite President Trump having announced earlier that the trade deal is comprehensive between the two nations.
The Dollar sprinted higher late Wednesday, fueled by the Fed rate decision and comments from Fed Chairman Jerome Powell. The Fed kept its policy rate unchanged at the 4.25%-4.50% range, as expected, while Fed Chairman Powell kept his wait-and-see approach on rates as uncertainty is high and there are risks for a return of inflation. That means the Fed will not cut anytime soon, making the US Dollar stronger with the yield differential between the US and other countries remaining wider in favor of the Greenback as the high-yielder.
Daily digest market movers: Speech awaited
- Several traders and analysts are expressing concerns about the trade deal between the UK and the US. Generally, a solid trade deal on several topics and sectors takes years to negotiate and be ratified by both involved parties’ first. The tail risk here is that this could only be a deal in principle or even a simple exchange of goods without any details or concrete action as of yet, Bloomberg reports. Meanwhile CNN reported as well that the 10% reciprocal tariffs slapped on the UK will remain in place, despite the trade deal.
- The Trump administration is looking into cancelling or ignoring former President Biden’s chip act, which limits US exports of chips from ASML, AMD and Nvidia. The news that the Trump administration is considering overturning the order is seeing a surge in the Nasdaq Futures pre-market.
- President Trump lashed out again at Fed Chairman Powell saying that energy prices and food prices have never been this low and that the Fed is too late in cutting rates while tariff money is pouring into the US, calling Fed Chairman Powell a "fool", on his Truth Social Network.
- The US weekly Jobless Claims this week saw Initial Claims came in at 228,000, below the expected 230,000 against the previous 241,000. The Continuing Claims fell to 1.879 million, below the expected 1.89 million, from 1.916 million.
- At 14:00 GMT, US President Trump will deliver a speech regarding the expected UK trade deal. At the time of writing, the speech has not started yet
- Equities are starting to turn a little from their peak performance after that CNN headline that UK tariffs will remain in place. European equities are up by 0.5%, US equities are showing a similar move and are up by less than 0.50% on the day.
- The CME FedWatch tool shows the chance of an interest rate cut by the Federal Reserve in June’s meeting at 20.2%. Further ahead, the July 30 decision sees odds for rates being lower than current levels at 66.4%.
- The US 10-year yields trade around 4.31%, not really moving much after the Fed and trade deal announcements.
US Dollar Index Technical Analysis: Worst deal ever?
The US Dollar Index (DXY) has quickly sprinted back to above 100.00 in a boost of positivity following the trade deal headlines. First, this is one of the smallest trade deals possible because the UK isn’t the main problem for the large US trade deficit in goods. Secondly, a trade deal with still a lot of blanks to get filled in – or a very minor deal on just one sector or one agricultural item – will raise the question of whether the billions in revenue promised by Trump will actually be received.
On the upside, the DXY’s first resistance comes in at 100.22, a level that supported the Index in September 2024. A firm recovery would be a return to 101.90, which acted as a pivotal level throughout December 2023 and as a base for the inverted head-and-shoulders (H&S) formation during the summer of 2024.
On the other hand, the 97.73 support could quickly be tested on any substantial bearish headline. Further below, a relatively thin technical support comes in at 96.94 before looking at the lower levels of this new price range. These would be at 95.25 and 94.56, meaning fresh lows not seen since 2022.
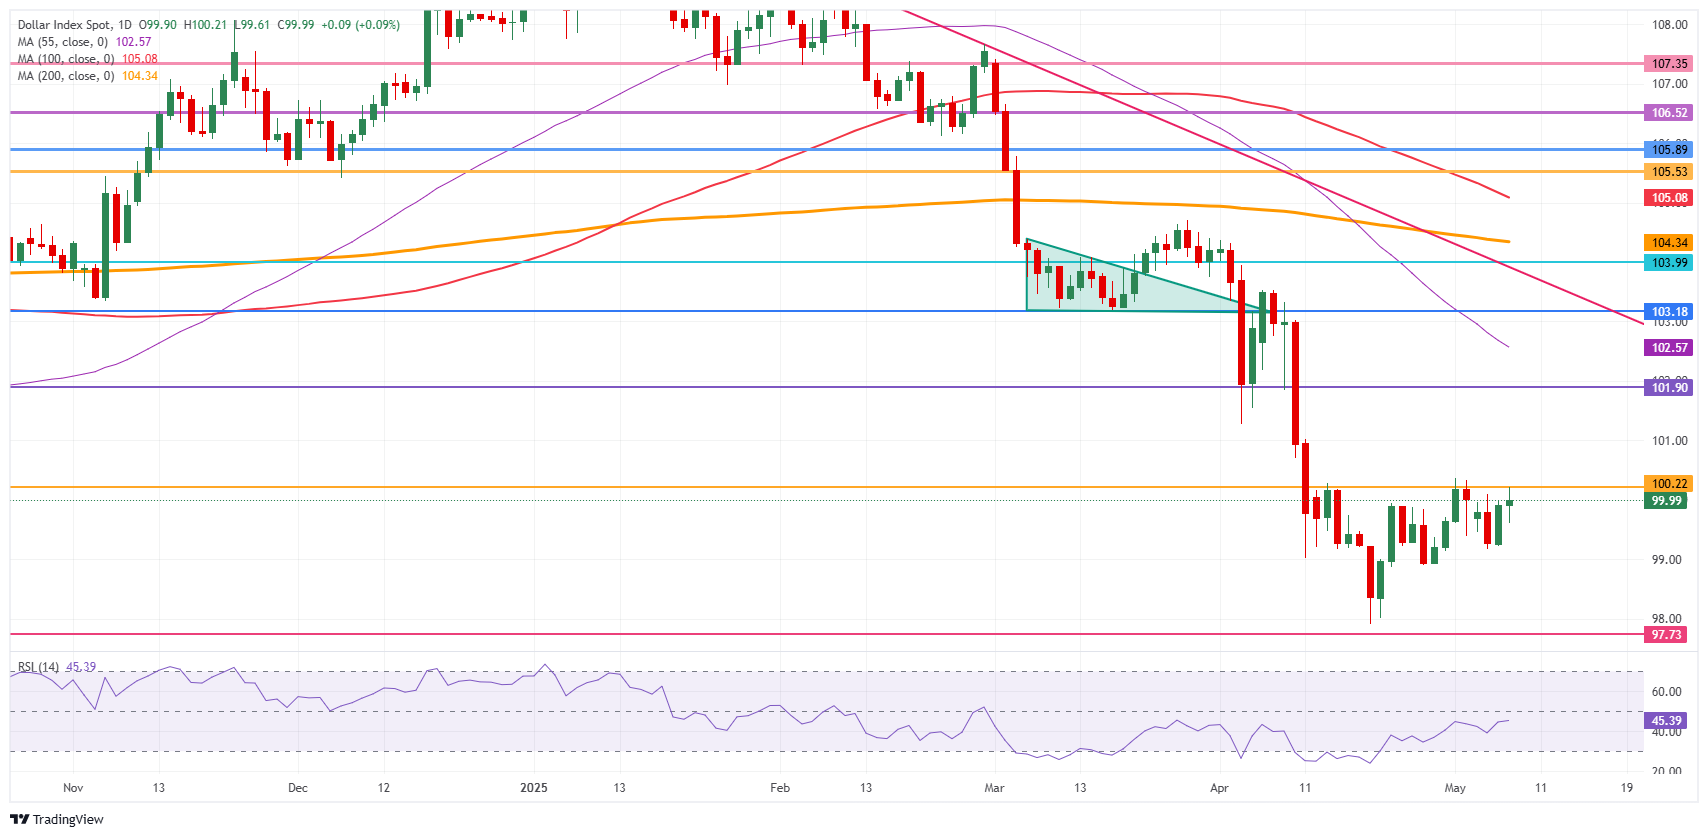
US Dollar Index: Daily Chart
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
BRANDED CONTENT
Finding the right broker for your trading strategy is essential, especially when specific features make all the difference. Explore our selection of top brokers, each offering unique advantages to match your needs.
Author

Filip Lagaart
FXStreet
Filip Lagaart is a former sales/trader with over 15 years of financial markets expertise under its belt.















