US Dollar takes back controle after disappointing first meeting on Ukraine
- The US Dollar sees small jump after NY State Manufacturing grew again for first time in months.
- Comments out of Riyadh this Tuesday are not bearing much positive signs of a quick resolution.
- The US Dollar Index (DXY) pops above 107.00 on the back of US-Russian headlines.
The US Dollar Index (DXY), which tracks the performance of the US Dollar (USD) against six major currencies, is trading above 107.00 on Tuesday after disappointing comments on day one of United States (US) and Russia talks on Ukraine. Several US officials have held a meeting with their Russian counterparts this Tuesday in Riyadh, Saudi Arabia, to try and work out a ceasefire or peace deal for Ukraine. First headlines that came out as the meeting ended, are that Russia is not seeing the need for a meeting between US President Donald Trump and Russian President Vladimir Putin this month, due to the number of demands Russia still has.
The economic calendar is again rather calm on Tuesday. The main event, the New York Empire State Manufacturing Index data for February already came out in surprise and snapped its contraction by turning positive for the first time in a couple of months. Up ahead, Federal Reserve Bank of San Francisco President Mary Daly and Federal Reserve Vice Chair for Supervision Michael Barr are set to speak later this Tuesday.
Daily digest market movers: Trump could get angry with this
- Markets are heading into Gold, US bonds and the Greenback after comments that the US-Russia talks did not go as smooth as hoped for. Russia sticks to its demands and is not looking for a quick solution, rather the long way of negotiations, while it feels that war fatigue at the Ukraine side is creating a positive Russian momentum on the ground. With funding and military equipment quickly being used up, both Europe and US are not really in favor to still write blank cheques for Ukraine to still fight off Russian troops.
- The New York Empire State Manufacturing Index for February came out of contraction by 5.70, beating the -1 expectation and compared to the previous -12.60.
- At 15:00 GMT, the National Association of Home Builders (NAHB) will release its Housing Market Index for February, which is expected to rise steadily by 47, from 47 in January.
- Federal Reserve Bank of San Francisco President Mary Daly and Federal Reserve Vice Chair for Supervision Michael Barr will speak later this Tuesday at 15:20 GMT and 18:00 GMT, respectively.
- Equities are flat to marginally lower with risk assets not performing under the rather disappointing headlines on the first day of talks between Russia and the US.
- The CME FedWatch tool shows a 49.8% chance that interest rates will remain unchanged at current levels in June.
- The US 10-year yield is trading around 4.51% and is ticking higher in some risk off sentiment.
US Dollar Index Technical Analysis: Dark clouds
The US Dollar Index (DXY) is facing too many loose ends to choose a surefooted direction. Plenty of catalysts and headlines are still expected, ranging from headlines on Ukraine and Europe to more details on US President Trump’s reciprocal tariffs, all ahead of this weekend’s German election. The US Dollar could start to outperform if a peace deal is brokered without Europe, missing the opportunity to play an important role in the new world order.
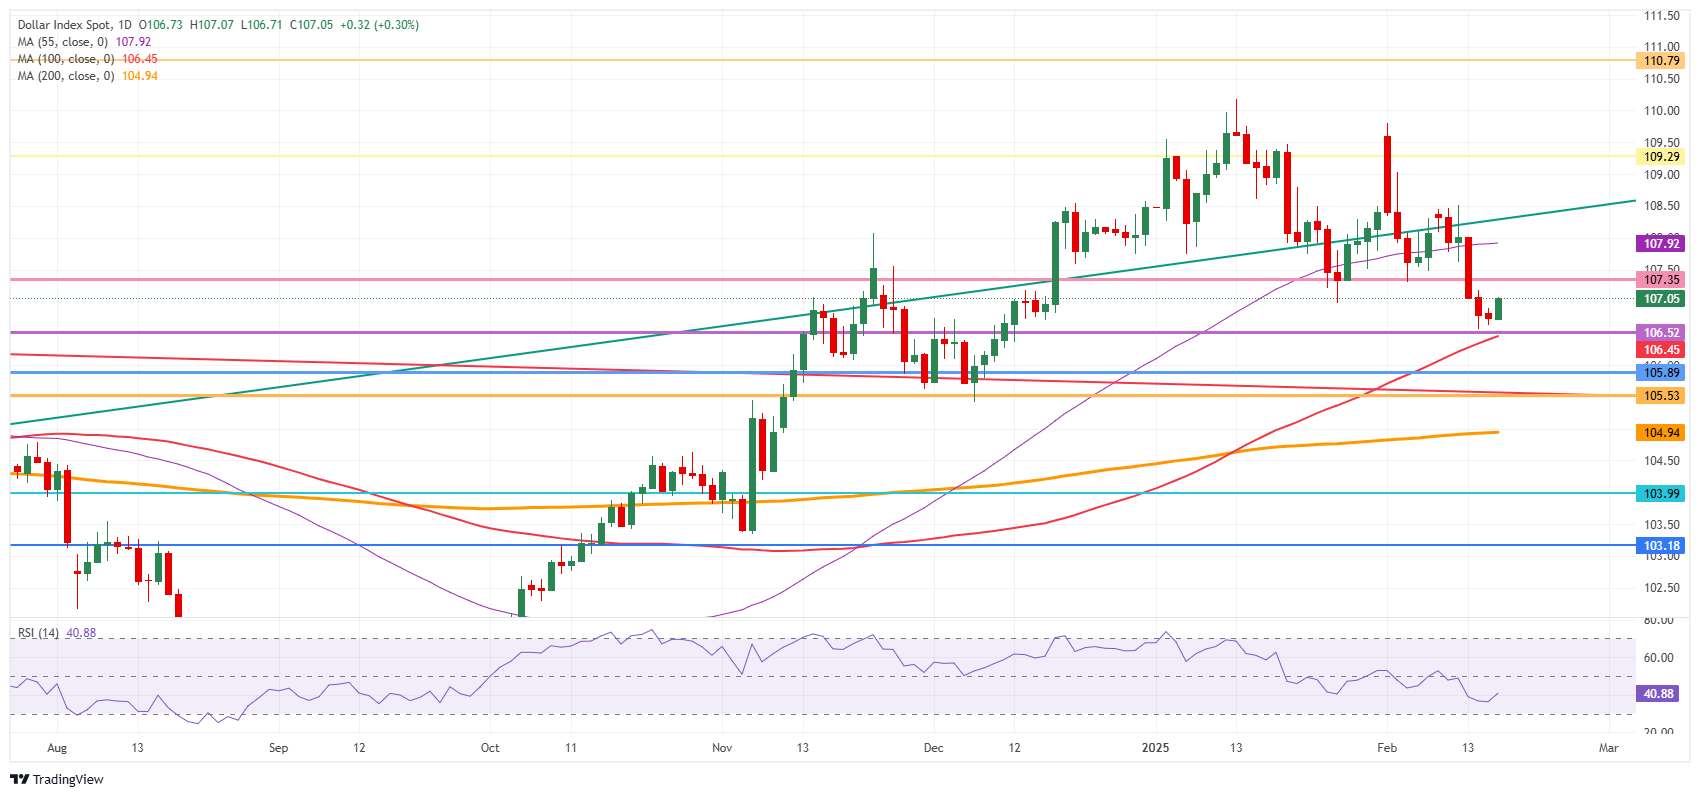
On the upside, the previous support at 107.35 has now turned into a firm resistance. Further up, the 55-day SMA at 107.92 must be regained before reclaiming 108.00.
On the downside, look for 106.52 (April 16, 2024, high), 106.45 (100-day SMA), or even 105.89 (resistance in June 2024) as support levels. As the Relative Strength Index (RSI) momentum indicator in the daily chart shows room for more downside, the 200-day SMA at 104.94 could be a possible outcome.
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
US Dollar Index: Daily Chart
(This story was corrected on February 18 at 13:51 GMT to say that the US bond market is not closed but trading and heading higher due to some risk off.)
Author

Filip Lagaart
FXStreet
Filip Lagaart is a former sales/trader with over 15 years of financial markets expertise under its belt.

















