US Dollar retreats with JOLTS showing substantial decline
- The US Dollar eases after JOLTS slides below 8 million.
- Markets are pricing in even more rate cuts to come from the Fed.
- The US Dollar Index eases further, back to lower levels near 101.00.

The US Dollar (USD) trades lower this Wednesday after the JOLTS Job Openings report comes in softer than expected. The JOLTS report is backward looking and reports on the Job Openings for the month of July. In June, the number of job openings was still above 8 million, though eased substantially in July. The fact that the magic 8 million barrier gets breached with a print of 7.6 million job openings, points to a much bigger cooling in the job market than anticipated.
On the economic data front, this jacks up expectations for the US Jobs Report on Friday. The ADP private payroll number on Thursday come add to more confirmation that the job market is really cooling down. The result will be even more rate cuts being priced in, expected from the US Federal Reserve, starting in September.
Daily digest market movers: JOLTS a kick in the nuts
- During US trading hours on Tuesday, news reported that the US Justice Department has subpoenaed NVIDIA (NVDA) for possible violations of antitrust laws. This triggered a selloff in the broader tech space that spilled over into the Asian and European session.
- At 11:00 GMT, the Mortgage Bankers Association has released its Mortgage Applications Index for the last week of August. The previous number was a slim 0.5% with this time a 1.6% uptick.
- At 12:30 GMT, the US Gods and Trade Balance data came in. For July, a deficit of $78.8 billion got published, after June's deficit of $73.1 billion.
- At 14:00 GMT, the JOLTS Job Openings report for July came in much softer than expected. The June number got revised down from 8,184 million to 7.91 million. The July number fell to 7.673 million, far below the 8.1 million expected.
- Equities are heading in the green with US equities advancing in the assumption the Fed will start to cut more and quicker.
- The CME Fedwatch Tool shows a 59.0% chance of a 25 basis points (bps) interest rate cut by the Fed in September against a 41.0% chance for a 50 bps cut. Another 25 bps cut (if September is a 25 bps cut) is expected in November by 40.0%, while there is a 46.8% chance that rates will be 75 bps (25 bps + 50 bps) below the current levels and a 13.2% probability of rates being 100 (25 bps + 75 bps) basis points lower.
- The US 10-year benchmark rate trades at 3.78% and trades at a fresh low for this week.
US Dollar Index Technical Analysis: JOLTS trips DXY
The US Dollar Index (DXY) looks to be stuck in a tight range, remaining there for now after Tuesday’s data was unable to move the needle. With the JOLTS Job Openings report on Wednesday, the assumption is the same: any number that comes in substantially above or below consensus will move the DXY in either direction. Meanwhile, markets are giving a bigger chance to a 50 basis point rate cut by the Fed this month, while data does not support that stance.
Looking up, the first resistance at 101.90 could easily be broken should JOLTS report come in stronger than expected. Further up, a steep 2% uprising would be needed to get the index to 103.18. Finally, a heavy resistance level near 104.00 not only holds a pivotal technical value, but it also bears the 200-day Simple Moving Average (SMA) as the second heavyweight to cap price action.
On the downside, 100.62 (the low from December 28) holds as support, although it looks rather feeble. Should it break, the low from July 14, 2023, at 99.58, will be the ultimate level to look out for. Once that level gives way, early levels from 2023 are coming in near 97.73.
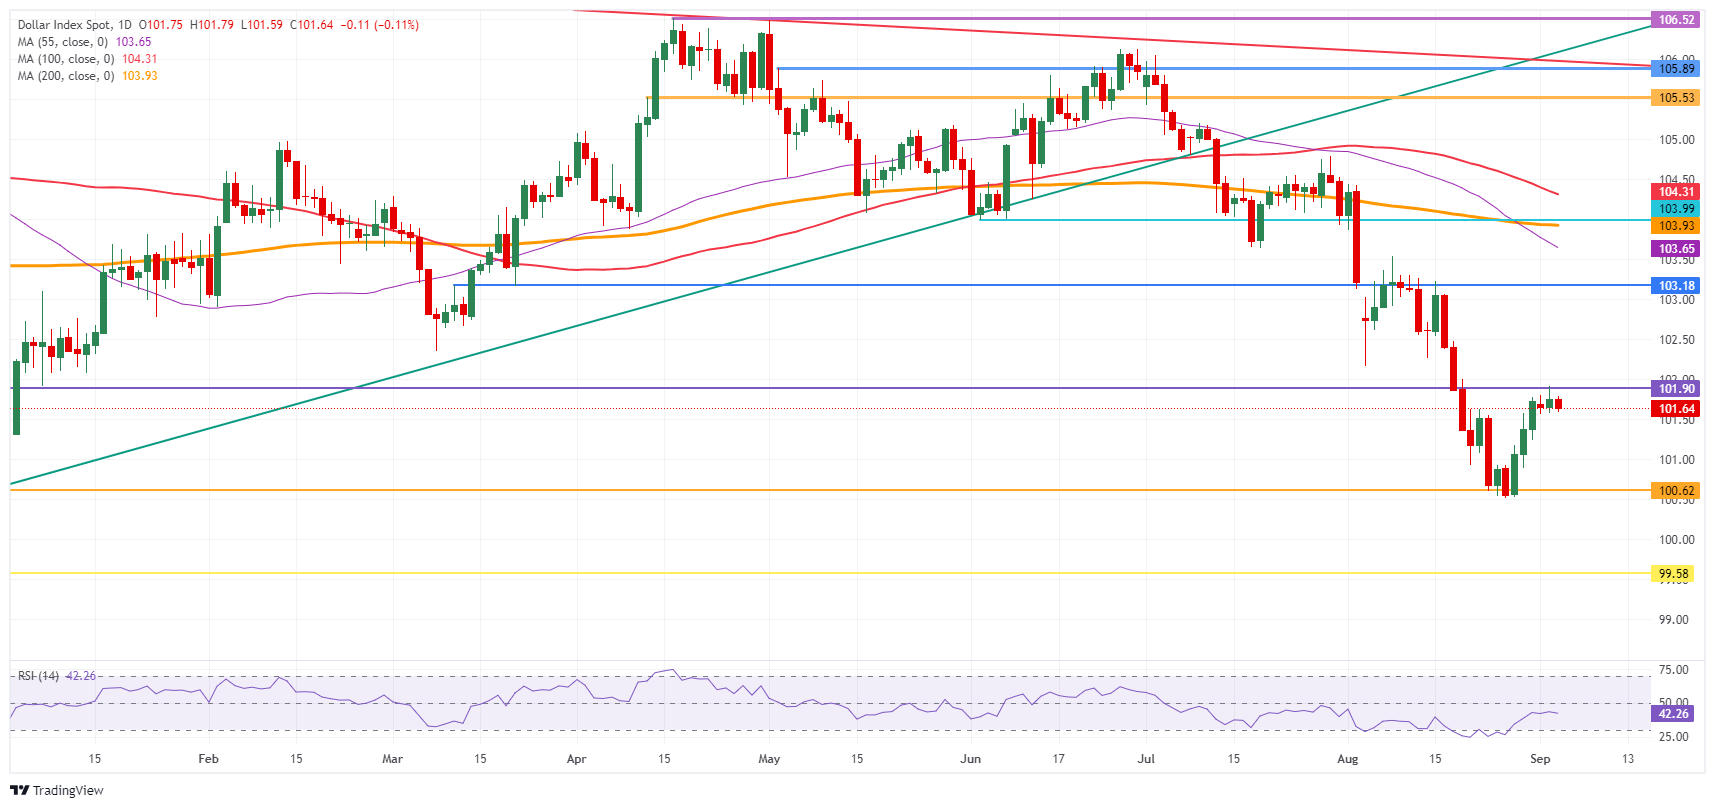
US Dollar Index: Daily Chart
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
Author

Filip Lagaart
FXStreet
Filip Lagaart is a former sales/trader with over 15 years of financial markets expertise under its belt.

















