S&P 500 Week Ahead: Whipsaw Friday, lots of jobs, heavy week of US debt auctions ahead
- Major indices whipsaw post the US Employment report on Friday.
- Nasdaq, S&P, and Dow all end Friday in positive territory.
- Nasdaq declines for the third straight week.

Well what a session that was, indices close up near session highs, having posted a strong recovery in the second half of Friday's trade. The US Employment report surpasses expectations coming in at 379k versus a 200k expectation, and a prior number for February of 166k. Markets initially took the good news as bad news, as fears over inflation resurfaced, and the 10Year yield duly broke back above 1.6%. Halfway through Friday and most indices were sharply lower but thereafter rallied to the close. End-of-week profit-taking and some bargain hunting in large-cap tech names lifted all boats. Microsoft and GOOGL in particular among the mega tech names drove the S&P 500 as it closed over 2% up. Tesla also rallied 8% from its halftime lows!
Sectoral Performance: Again Energy leads the way closing 3.15% higher, boosted by both Brent and WTI Crude prices jumping 4% as OPEC+ decided not to increase supply for April. Most sectors closed 2% higher in line with the broader market but Consumer Discretionary lagged with a less than 1% gain.
Winners and Losers: Devon Energy +8%, Oracle +6.6%, GAP Inc +7.6%, Haliburton +7.9%, Intel +4%, Tesla -4%, DocuSign -3%, Zoom Video -1.6%, Norwegian Cruise Line -12%, Royal Caribean -5%, Carnival -4.8%, American Airlines -3.7%, United Airlines -3%.
Next week inflation is likely to again be the main theme as a continuation in the ascent of global interest rates will focus traders' minds. The US yield curve will take centre stage as numerous debt auctions post. Monday sees US 3 and 6 month Bill auctions, Tuesday brings the 3-year note auction and on inflation super Wednesday we get a US 10 year auction and US CPI to ponder. So clearly inflation concerns to remain centre stage.
The Dollar continued its ascent firmly consolidating its earlier break of 1.20 against the Euro, closing at 1.1915, Oil was pushed higher by OPEC+ with WTI Crude closing at $66.31 and the US 10 Year yield closed at 1.56%, having come off 13-month highs early on Friday, post the jobs report.
S&P 500 Week Ahead News
AMC results are due out on Wednesday with a significant drop in revenue expected due to coronavirus. Outlook will be key.
Oracle releases earnings on Wednesday. Barclays upgraded it on Friday ahead of results.
Adobe will report earnings on Thursday after the close.
JD.com will report earnings on Thursday.
Fisker will report earnings on Tuesday but this is not confirmed.
Chevron is to give an annual update on Tuesday.
Bumble Inc is to report quarterly results on Wednesday, its first since IPO.
Federal Reserve Dallas President Robert Kaplan to speak on Tuesday.
Bank of Canada rate decision on Wednesday. No change from 0.25% expected.
US 3 Year auction on Tuesday and US 10 Year auction on Wednesday. Also on inflation super Wednesday, we get US CPI, with PPI on Friday.
S&P 500 Technical analysis
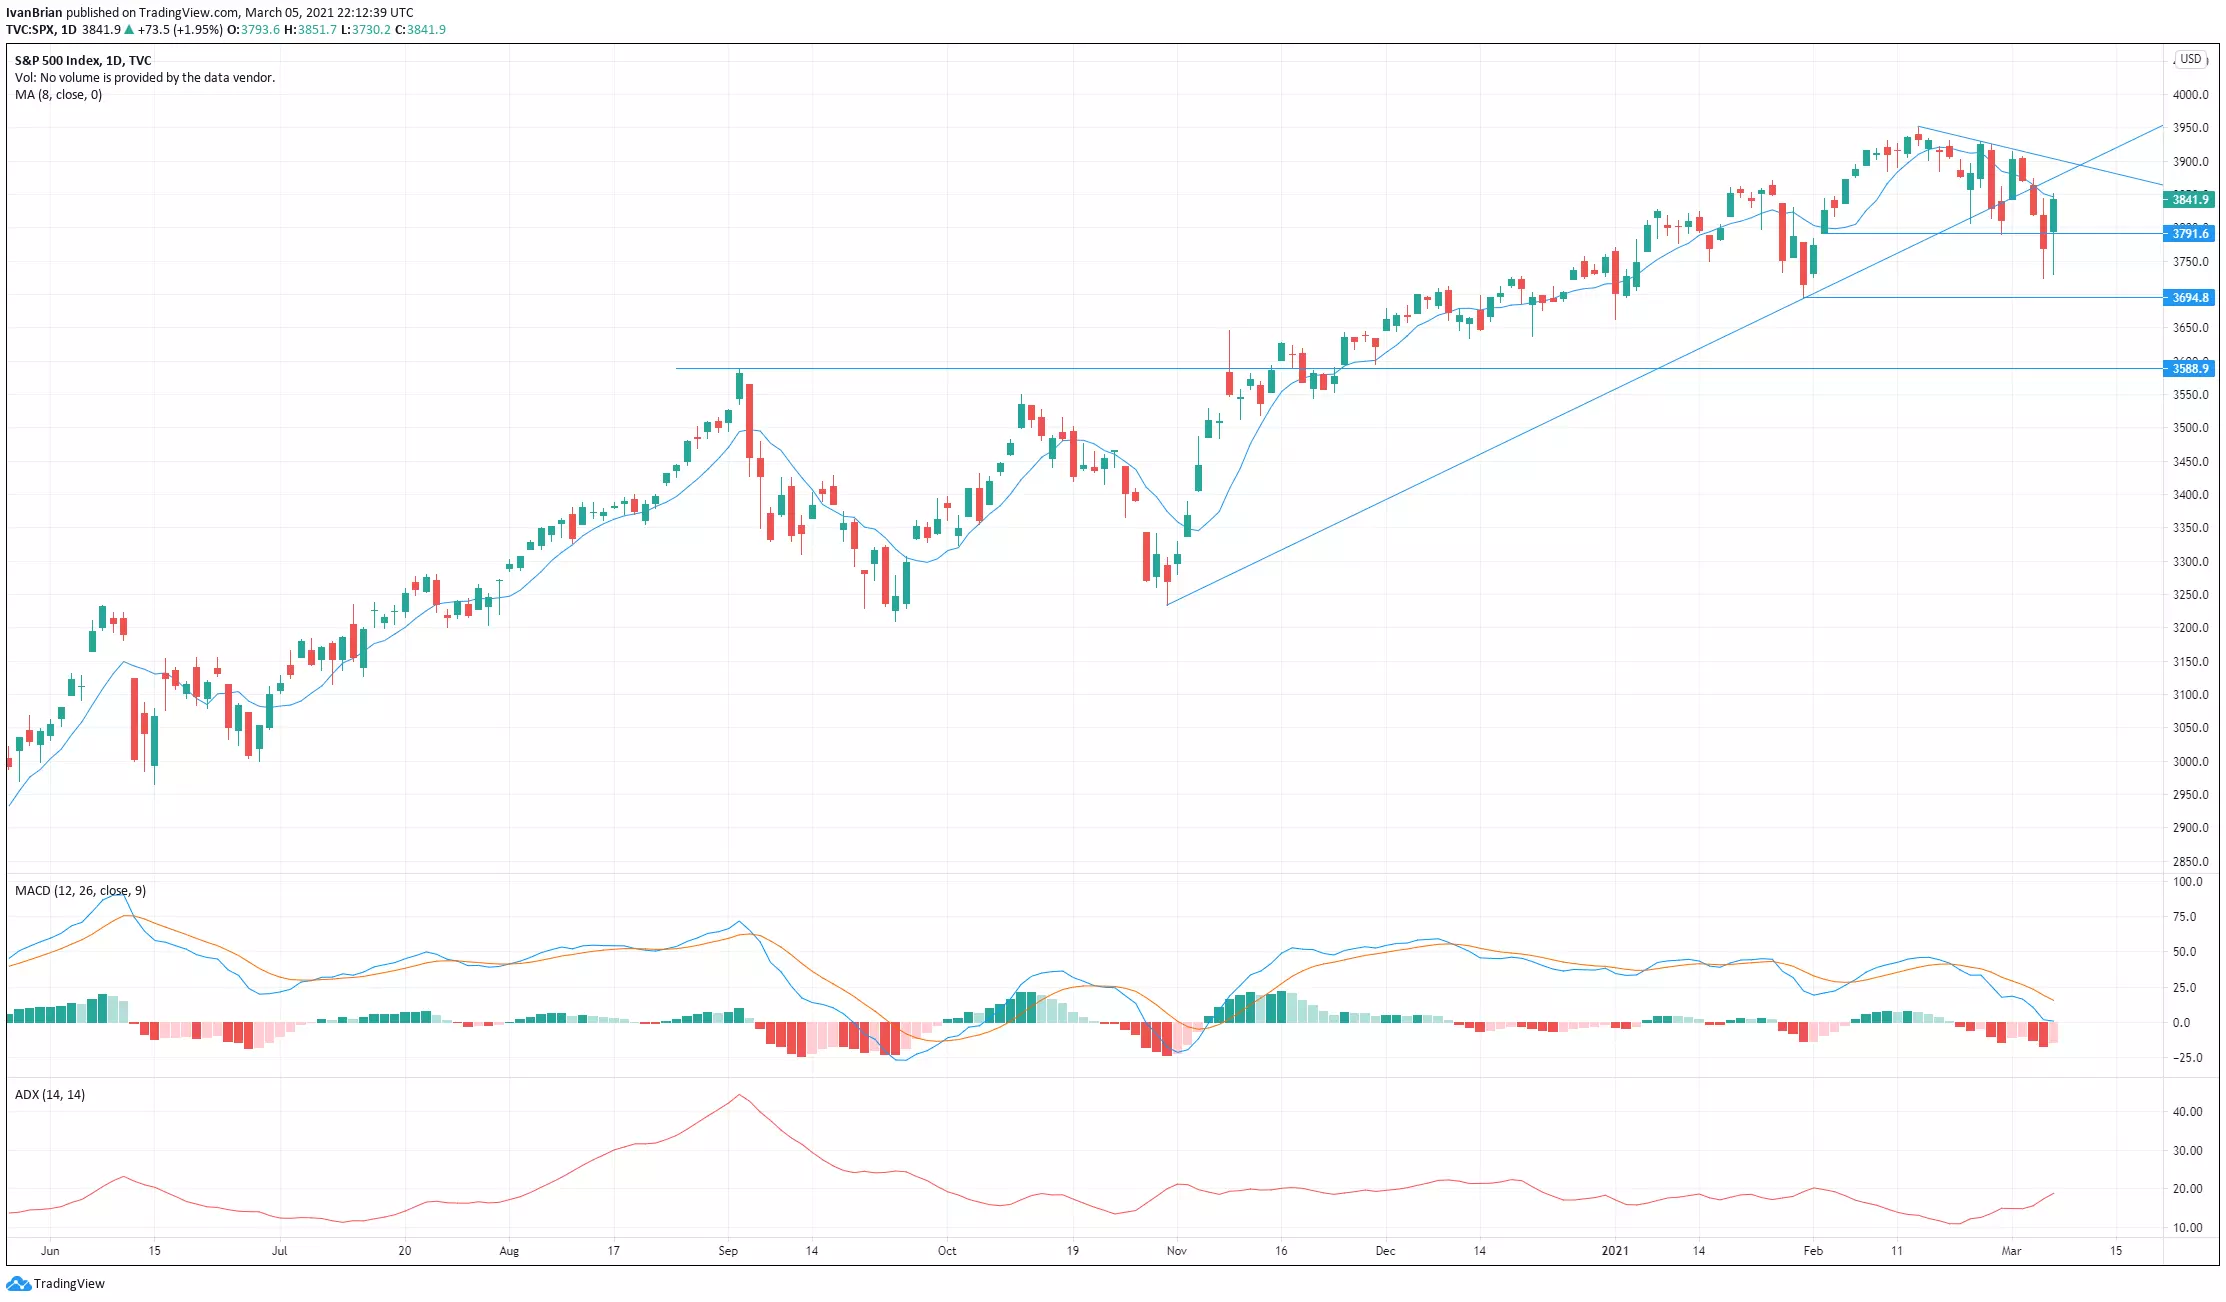
Phew, try and analyze that! Well the S&P did its best to recapture the bullish momentum from early 2021 but stopped just short of breaking above its short term 8-day moving average. However, we still have a nice rejection of yesterdays lows as the market initially looked to probe a move to support at sub 3700 but was sharply rejected. So now Monday's set up will be key. Can we open positively and retake the 8-day moving average and target recent highs above 3900 and ultimately new highs to re establish bullish momentum. Or is this volatility and uncertainty just a staging point for a move lower?
Next week is key with CPI and PPI and debt auctions giving the market the excuses it wants. Markets do what they want irrespective of the data. Traders and investors will make up the narrative to suit their needs. Take today for example, the overly strong jobs report led many to predict runaway inflation, stimulus fueled price rises and so the market sold off. But the narrative changed on the close despite the data remaining the same. So what does the market want to do, where does it want to go?
Clearly, it has been struggling for momentum and direction so waiting for a breakout of strong points is always a good option! To the downside a break of 3694 would be a strong bear signal. The market has been probing these levels to see if they get rejected. The market is jabbing to test levels. Today it got a strong sucker punch back but one feels it will still jab away a bit more at these levels. Remaining below 3791 should lead to a test of 3694. To stay bullish we need to break above 8 and 21-day moving averages, take out trendline resistance at 3898 and then we can target the 3950 high.
The author has no position in any stock mentioned in this article and no business relationship with any company mentioned. The author has not received compensation for writing this article, other than from FXStreet.
This article is for information purposes only. The author and FXStreet are not registered investment advisors and nothing in this article is intended to be investment advice. It is important to perform your own research before making any investment and take independent advice from a registered investment advisor.
FXStreet and the author do not provide personalized recommendations. The author makes no representations as to accuracy, completeness, or the suitability of this information. FXStreet and the author will not be liable for any errors, omissions or any losses, injuries or damages arising from this information and its display or use. The author will not be held responsible for information that is found at the end of links posted on this page.
Errors and omissions excepted.
Author

Ivan Brian
FXStreet
Ivan Brian started his career with AIB Bank in corporate finance and then worked for seven years at Baxter. He started as a macro analyst before becoming Head of Research and then CFO.

















