S&P 500 Forecast: Debt ceiling shenanigans, Nvidia earnings main events this week
- President Biden and House Republican leadership will continue debt negotiations.
- Nvidia will release earnings after the close on Wednesday.
- Zoom Video, Costco, Lowe’s and Snowflake also report.
- FOMC minutes on Wednesday, GDP on Thursday round out the week for data.
The S&P 500 index reversed 1.65% higher last week following two down weeks. Excitement over a possible debt-ceiling solution ushered in a rally on Wednesday and Thursday, but the rebound dissipated somewhat on Friday afternoon when it appeared the parties were at an impasse.
Further debt-ceiling negotiations will continue to take place on Monday and throughout the week, and Wall Street appears sanguine that an agreement will come before the June 1 deadline handed down by Treasury Secretary Janet Yellen.
At the time of writing in Monday’s premarket, both S&P 500 and NASDAQ 100 futures are muted as the market awaits further news on the debt ceiling.
S&P 500 News: Debt ceiling remains the focus for second straight week
This past weekend saw both President Joe Biden and House Speaker Kevin McCarthy trade barbs over the seriousness of the opposing side. Biden spent the weekend in Japan for the G7 summit but held a call with McCarthy before boarding Air Force 1 for Washington.
On Sunday evening, staff members from both sides’ negotiating teams met for initial preparation, and Biden will sit down with McCarthy on Monday afternoon. The White House has chosen Counselor Steve Ricchetti, Office of Management & Budget Director Shalanda Young and White House Legislative Affairs director Louisa Terrell to lead discussions with McCarthy's staff and the Republican side’s leading negotiator Rep. Garret Graves.
Expect headlines from this first meeting of the week to set the direction for the S&P 500 on Monday afternoon. The sticking points at the moment seem to be that McCarthy has refused to raise taxes, close tax loopholes or alter the military budget, while Biden has said that entitlements are mostly off the table. McCarthy and the Republican side are also pushing to cut major provisions of Biden’s signature Inflation Reduction Act.
Wall Street seemed upbeat about the prospect for negotiations for most of last week, but expect stocks to begin selling off toward the end of this week if no deal is in sight. Wall Street executives have told a number of media outlets that even a technical default could send markets reeling. This is because Treasuries are used as collateral in derivative, mortgage and commodity markets. Any disfunction could produce a great deal of volatility throughout markets, but that event would not likely appear until June.
All eyes on Nvidia, FOMC minutes, GDP
Nvidia (NVDA) will release earnings late Wednesday, and Wall Street expects $0.92 in adjusted earnings per share on $6.52 billion in revenue. This would be a major drop-off from a year ago’s $1.36 per share on revenue of $8.29 billion, but the market believes that the worst is already behind Nvidia. In the case of a miss, expect the entire market to sell off.
In the later part of the morning on Wednesday, Federal Open Market Committee (FOMC) minutes will be released to the public. The market is hoping that another hike of the fed funds rate is taken off the table, although a large minority still believes that one more hike is coming before the pause. Worrisome chatter would of course have a negative impact on the S&P 500.
Then on Thursday, the preliminary Q1 GDP number arrives from the US Bureau of Economic Analysis. Expected at 1.1% on an annualized basis, a much lower reading should frighten the market, while a higher number would complicate the issue. Traders may wonder whether a higher reading leads to a bigger chance of another rate hike.
Earnings of the week
Monday, May 22 - Zoom Video Communications (ZM), Global-e Online (GLBE)
Tuesday, May 23 - Lowe’s (LOW), Palo Alto Networks (PANW), AutoZone (AZO), Intuit (INTU)
Wednesday, May 24 - Nvidia (NVDA), Analog Devices (ADI), Snowflake (SNOW), XPeng (XPEV), UiPath (PATH)
Thursday, May 25 - Costco (COST), Workday (WDAY), Medtronic (MDT), Dollar Tree (DLTR)
Friday, May 26 - Big Lots (BIG)
S&P 500 quote: Cyberspace Administration of China
China issued a directive to domestic tech companies to stop buying hardware from Micron (MU). The regulator said that Micron’s memory chips posed a national security threat due to their “serious network security risks”.
"Operators of critical information infrastructure in China should stop purchasing products from Micron Co.”
S&P 500 forecast
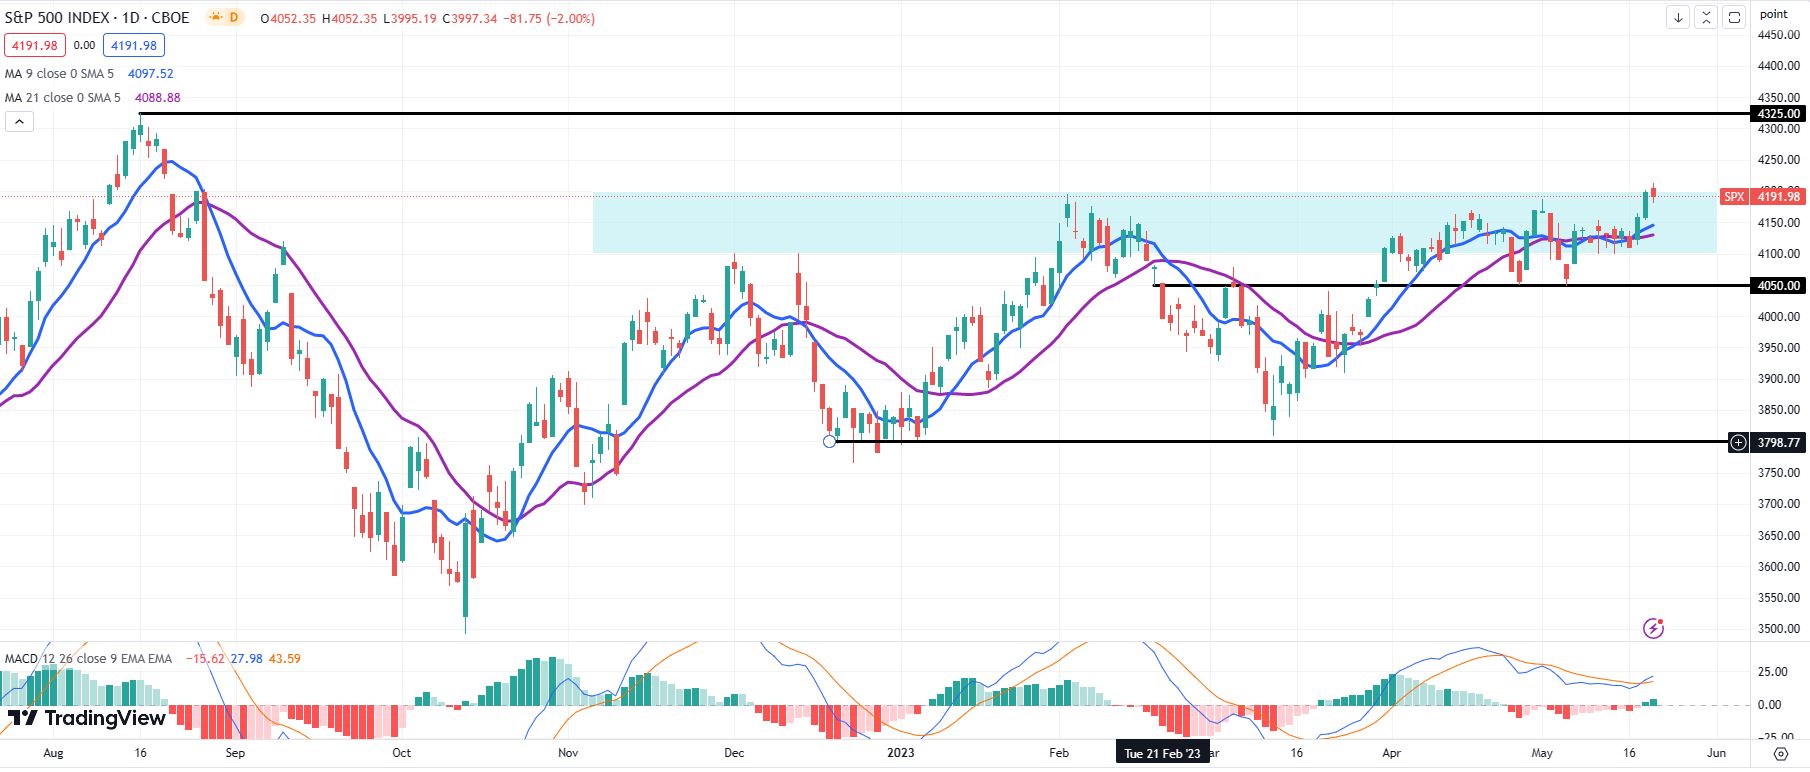
The S&P 500 now looks to be on solid footing for a real rally. If you just looked at the daily chart below, you would be hard pressed to know that a worrisome debt-ceiling standoff was happening. Thursday’s rally pushed the S&P 500 above hard resistance at 4,200 last Thursday. Friday opened above that level, but once again closed below it.
This could mean that 4,200 will not be broken, but two pieces of evidence demonstrate the likelihood of a rally. The Moving Average Convergence Divergence (MACD) indicator crossed over bullishly last Wednesday. Additionally, the 9-day moving average broke away above its 21-day counterpart. Last Friday’s high at 4,212 marked a new high above the range high from February 2. That makes it the highest reading since August of last year. All the S&P 500 needs is a debt ceiling agreement before June 1, and a glide path to 4,325 is in the cards.
Author

Clay Webster
FXStreet
Clay Webster grew up in the US outside Buffalo, New York and Lancaster, Pennsylvania. He began investing after college following the 2008 financial crisis.