Pound Sterling remains on backfoot on firm BoE rate cut hopes
- The Pound Sterling drops as investors expect the BoE to cut rates sooner than expected.
- BoE Bailey said market expectations for two or three rate cuts this year are not unreasonable.
- The main event for this week will be the US core PCE price index data for February.

The Pound Sterling (GBP) falls to near 1.2600 in Wednesday’s early American session. The broader appeal remains weak as investors expect the Bank of England (BoE) will start reducing interest rates sooner than previously anticipated. To a certain extent, the BoE has turned dovish on the interest rate outlook as the United Kingdom’s inflation is softening.
In a recent interview with the Financial Times, BoE Governor Andrew Bailey said market expectations for rate cuts this year are not unreasonable. About the inflation outlook, Bailey said "We are not seeing a lot of sticky persistence."
The US Dollar Index (DXY), which values the Greenback against six foreign currencies, retreats from 104.40. Going forward, the United States core Personal Consumption Expenditure price index (PCE) data for February, which will be published on Good Friday, will guide the major move in the US Dollar.
Daily digest market movers: Pound Sterling advances as US Dollar aims to recapture monthly high
- The Pound Sterling dips to 1.2600 amid the upbeat US Dollar. The US Dollar advances amid caution ahead of the United States core PCE price index data for February. The Federal Reserve’s (Fed) preferred inflation measure could provide some cues about when the central bank could start reducing interest rates.
- Stubborn inflation and a strong economic outlook in the US could allow the Fed to delay its rate cut plans. The Fed’s latest dot plot, released last week, pointed to three rate cuts for this year, but slower progress in inflation declining to the 2% target could also result in fewer cuts.
- Meanwhile, market expectations for the Bank of England’s interest rate outlook will drive the next move in the Pound Sterling. A sharp decline in the UK’s inflation data for February has uplifted expectations for the BoE to begin reducing interest rates early in the June policy meeting. Before the release of the soft inflation data and slightly dovish interest rate guidance from the BoE, rate cuts were majorly expected starting from the August meeting.
- In its last meeting, the BoE was observed as slightly dovish as no policymaker voted for a rate hike for the first time since September 2021. Catherine Mann, who remains a hawk, dropped her rate hike call as she observed that consumers are reluctant to pay higher prices on services such as travel and hospitality, she said in an interview with Bloomberg. Mann added that firms are cutting working hours in times when more employment is required. She further added that the number of workers in the labor market will increase due to the government's cuts to social security rates.
- This week, the UK’s economic calendar is light. Investors will look for revised Q4 2023 Gross Domestic Product (GDP) estimates. Any significant change from preliminary estimates will influence the Pound Sterling. The preliminary estimates showed that the UK economy entered a technical recession in the second half of 2023 after contracting by 0.3% in the October-December quarter.
Technical Analysis: Pound Sterling faces pressure to sustain above 1.2600
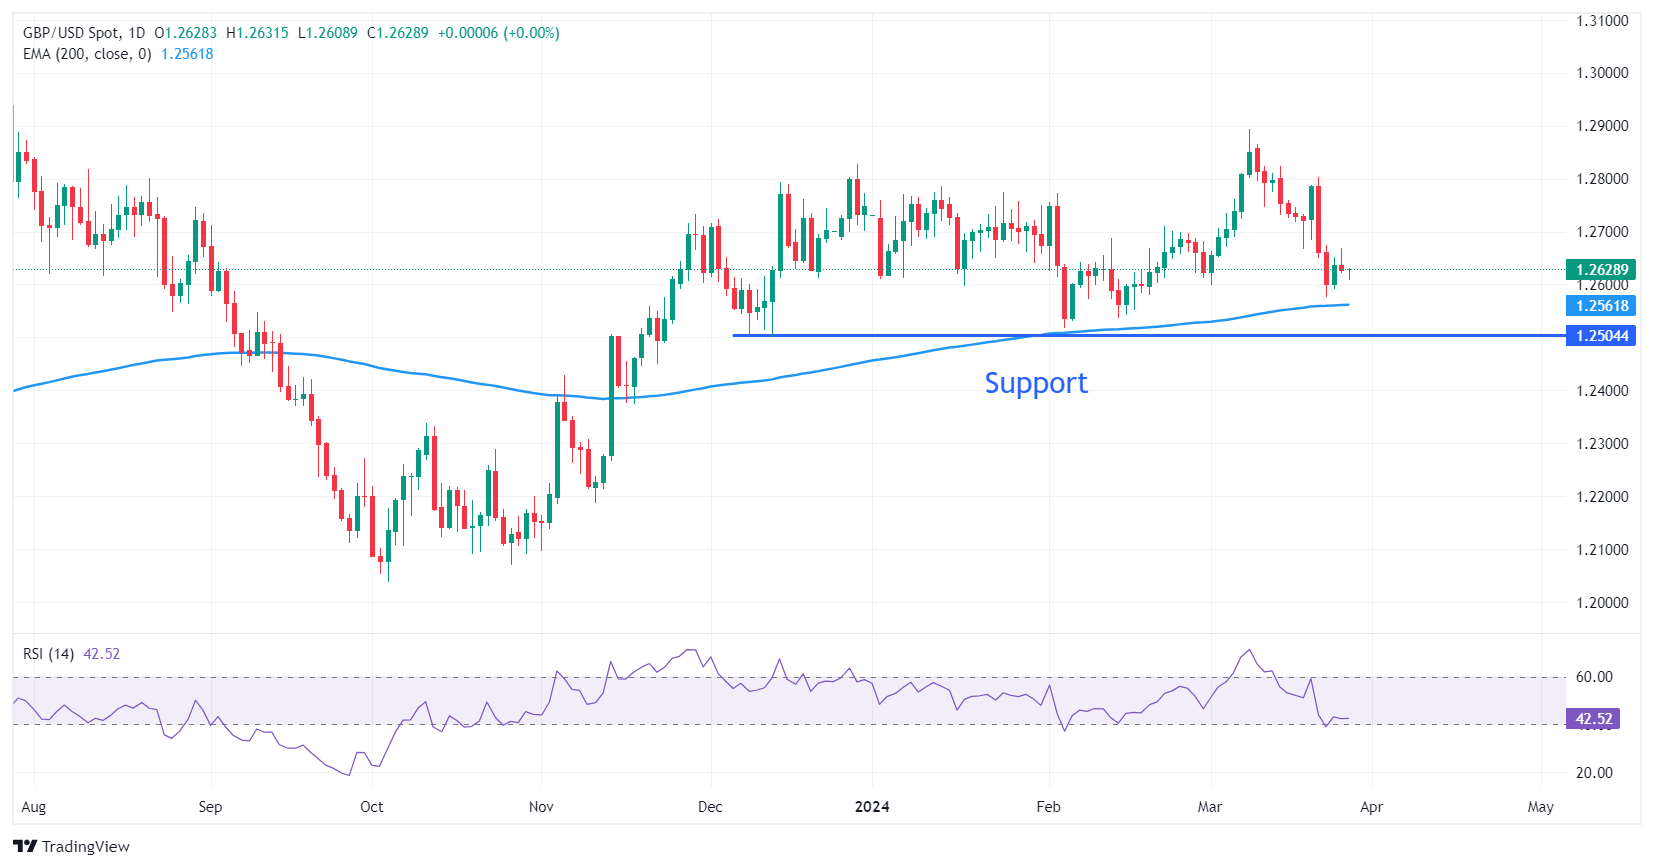
The Pound Sterling discovers some buying interest near the round-level support of 1.2600. The GBP/USD pair falls after facing stiff resistance while extending the upside above the 1.2660 hurdle. The pair trades slightly higher than the 200-day Exponential Moving Average (EMA), placed around 1.2565. The asset would extend its downside if it drops below the 200-day EMA.
The 14-period Relative Strength Index (RSI) slips to near 40.00. If it dips below this level, a bearish momentum will trigger.
Inflation FAQs
Inflation measures the rise in the price of a representative basket of goods and services. Headline inflation is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core inflation excludes more volatile elements such as food and fuel which can fluctuate because of geopolitical and seasonal factors. Core inflation is the figure economists focus on and is the level targeted by central banks, which are mandated to keep inflation at a manageable level, usually around 2%.
The Consumer Price Index (CPI) measures the change in prices of a basket of goods and services over a period of time. It is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core CPI is the figure targeted by central banks as it excludes volatile food and fuel inputs. When Core CPI rises above 2% it usually results in higher interest rates and vice versa when it falls below 2%. Since higher interest rates are positive for a currency, higher inflation usually results in a stronger currency. The opposite is true when inflation falls.
Although it may seem counter-intuitive, high inflation in a country pushes up the value of its currency and vice versa for lower inflation. This is because the central bank will normally raise interest rates to combat the higher inflation, which attract more global capital inflows from investors looking for a lucrative place to park their money.
Formerly, Gold was the asset investors turned to in times of high inflation because it preserved its value, and whilst investors will often still buy Gold for its safe-haven properties in times of extreme market turmoil, this is not the case most of the time. This is because when inflation is high, central banks will put up interest rates to combat it. Higher interest rates are negative for Gold because they increase the opportunity-cost of holding Gold vis-a-vis an interest-bearing asset or placing the money in a cash deposit account. On the flipside, lower inflation tends to be positive for Gold as it brings interest rates down, making the bright metal a more viable investment alternative.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.

















