Mexican Peso slides on recession jitters following Q4 GDP slump
Most recent article: Mexican Peso tumbles as inflation and weak growth supports Banxico rate cuts
- Mexico’s Q4 GDP contracts for the first time since 2021.
- Banxico slashes 2025 growth outlook to 0.6%, well below Finance Ministry projections.
- US data mixed: Manufacturing PMI improves but Services PMI falls into contraction.
The Mexican Peso (MXN) lost some ground against the US Dollar (USD) on Friday as the Mexican economy decelerated in the last quarter of 2024. This indicates that the outlook is not as promising as expected amid an environment of uncertainty linked to United States (US) President Donald Trump's trade policies. USD/MXN trades at 20.41, registering gains of 0.54%.
Mexico’s economy contracted in Q4 2024 for the first time since the third quarter of 2021, revealed the Statistics agency INEGI. Gross Domestic Product (GDP) matched estimates on a quarterly basis and dipped compared to the previous reading and forecasts on a yearly basis.
Banco de Mexico (Banxico) expects growth this year to slow down by 0.6%, as the latest meeting minutes revealed. The Governing Board expects the economy to grow 0.6% in 2025, down from the 1.2% previously foreseen, well below the projections of Mexico’s Finance Ministry of 2.3% and beneath the Citi Expectations Survey of 1%.
Given the backdrop, the USD/MXN pair shows further upside. S&P Global revealed that manufacturing activity in the United States improved. Meanwhile, the Services PMI plunged to contractionary territory for the first time since January 2023.
Other data showed that Existing Home Sales plunged and the University of Michigan (UoM) Consumer Sentiment Final reading for February deteriorated further.
Daily digest market movers: Mexican Peso heavy, economy projected to underperform
- Gross Domestic Product (GDP) shrank by -0.6% QoQ in the fourth quarter of 2024, down from a 1.1% expansion and matched estimates of a Reuters poll.
- On yearly terms, Mexico’s economy grew 0.5% in Q4 compared to 2023 figures. Growth for the whole year hit 1.2%, its worst annual number since 2020.
- Monetary policy divergence between Banxico and the Fed favors further USD/MXN upside. The Fed is expected to keep rates steady, while Banxico is foreseen to cut rates again by 50 basis points at the next meeting.
- At the time of writing, US President Donald Trump reiterated tariffs of 25% on cars, effective on April 2.
- Trade disputes between the US and Mexico remain front and center. Although the countries found common ground previously, USD/MXN traders should know that there is a 30-day pause and that tensions could arise toward the end of February.
USD/MXN technical outlook: Mexican Peso drops as USD/MXN bounces off 20.20
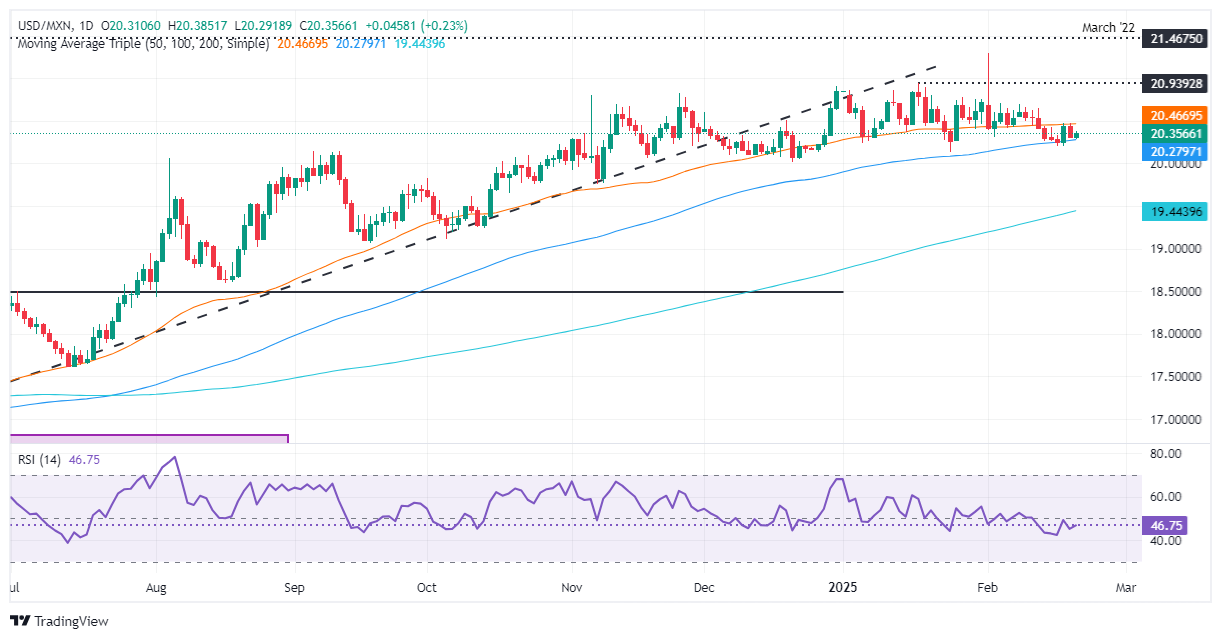
The USD/MXN pair does not present abrupt changes, with the trend slightly tilted to the upside. After bottoming near the 100-day Simple Moving Average (SMA) at 20.23, buyers pushed the pair upwards. Nevertheless, stir resistance near 20.40, maintains the exotic pair trading sideways.
If USD/MXN clears 20.40, the next resistance would be 20.50, followed by the January 17 20.93 mark. On further strength, the next key resistance levels are 21.00 and the year-to-date (YTD) high of 21.28. Conversely, if the pair tumbles below 20.23, the 20.00 figure is up next. A breach of the latter exposes the October 18, 2024, low at 19.64, ahead of the 200-day SMA at 19.37.
Mexican Peso FAQs
The Mexican Peso (MXN) is the most traded currency among its Latin American peers. Its value is broadly determined by the performance of the Mexican economy, the country’s central bank’s policy, the amount of foreign investment in the country and even the levels of remittances sent by Mexicans who live abroad, particularly in the United States. Geopolitical trends can also move MXN: for example, the process of nearshoring – or the decision by some firms to relocate manufacturing capacity and supply chains closer to their home countries – is also seen as a catalyst for the Mexican currency as the country is considered a key manufacturing hub in the American continent. Another catalyst for MXN is Oil prices as Mexico is a key exporter of the commodity.
The main objective of Mexico’s central bank, also known as Banxico, is to maintain inflation at low and stable levels (at or close to its target of 3%, the midpoint in a tolerance band of between 2% and 4%). To this end, the bank sets an appropriate level of interest rates. When inflation is too high, Banxico will attempt to tame it by raising interest rates, making it more expensive for households and businesses to borrow money, thus cooling demand and the overall economy. Higher interest rates are generally positive for the Mexican Peso (MXN) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken MXN.
Macroeconomic data releases are key to assess the state of the economy and can have an impact on the Mexican Peso (MXN) valuation. A strong Mexican economy, based on high economic growth, low unemployment and high confidence is good for MXN. Not only does it attract more foreign investment but it may encourage the Bank of Mexico (Banxico) to increase interest rates, particularly if this strength comes together with elevated inflation. However, if economic data is weak, MXN is likely to depreciate.
As an emerging-market currency, the Mexican Peso (MXN) tends to strive during risk-on periods, or when investors perceive that broader market risks are low and thus are eager to engage with investments that carry a higher risk. Conversely, MXN tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.
















