Mexican Peso slips as USD/MXN reclaims 20 despite tariff exemption hopes
- Mexican Peso pares gains late in session as traders digest Trump’s shifting tariff stance and looming US tomato duties.
- Sheinbaum continues talks to avoid steep tariffs; US to impose 20.91% duty on Mexican tomatoes from July 14.
- Traders eye Mexico’s inflation and retail data, while US Retail Sales and Jobless Claims remain i
The Mexican Peso reversed its course and dropped against the US Dollar late in the North American session, with no catalyst behind the latter move as market participants digest Trump’s tariff rhetoric, which of late hinted at making exemptions on semiconductors and electronics. At the time of writing, the USD/MXN climbs back above the 20.00 figure and gains over 0.12%.
Mexico’s President Claudia Sheinbaum continued negotiating with her US counterpart to avoid Trump's higher tariffs. At the same time, the US Commerce Department announced that tomatoes imported from Mexico to the US would be subject to 20.91% tariffs from July 14.
Meanwhile, Reuters revealed that a report suggested Japan’s Honda is considering relocating some car production to the US to avoid tariffs.
Across the border, the economic docket revealed that US import prices fell in March due to decreasing energy prices, as the US Labor Department showed on Tuesday. According to analysts quoted by Reuters, the effects of tariffs have not been felt.
Ahead in the docket, Mexico will feature Retail Sales, mid-month inflation for April, and Economic Activity for February. In the US, Retail Sales would also be featured on Wednesday, followed by housing and Initial Jobless Claims data.
Daily digest market movers: Mexican Peso hurt by tariffs, retreats
Mexico’s Retail Sales in January were 0.6% MoM and 2.7% YoY. If Wednesday’s data falls below those figures, it would be another signal that the economy is slowing down, as Banco de Mexico (Banxico) Governor Victoria Rodriguez Ceja mentioned.
Before the Senate, Victoria Rodriguez Ceja said the Governing Board is still unsatisfied with the inflation rate, which stood at 3.8% YoY in March, though far from the 3% target. She added that the disinflation process and the economic slowdown justify Banxico’s dovish approach and hinted that the central bank might continue easing policy.
This would keep the USD/MXN underpinned as the interest rate differential between Mexico and the United States will reduce. For the upcoming meetings, Banxico is expected to lower rates by 50 basis points (bps) while the Federal Reserve (Fed) hinted they will keep rates unchanged.
Money market players had priced in 85 bps of easing toward the end of 2025. The first cut is expected in July.
US Retail Sales in March are expected to rise 1.3% Month over Month, up from 0.2% in February. Meanwhile, Industrial Production is projected to contract by 0.2% Month over Month, down from 0.7% expansion for the same period.
USD/MXN technical outlook: Mexican Peso depreciates as USD/MXN surpasses 20.00
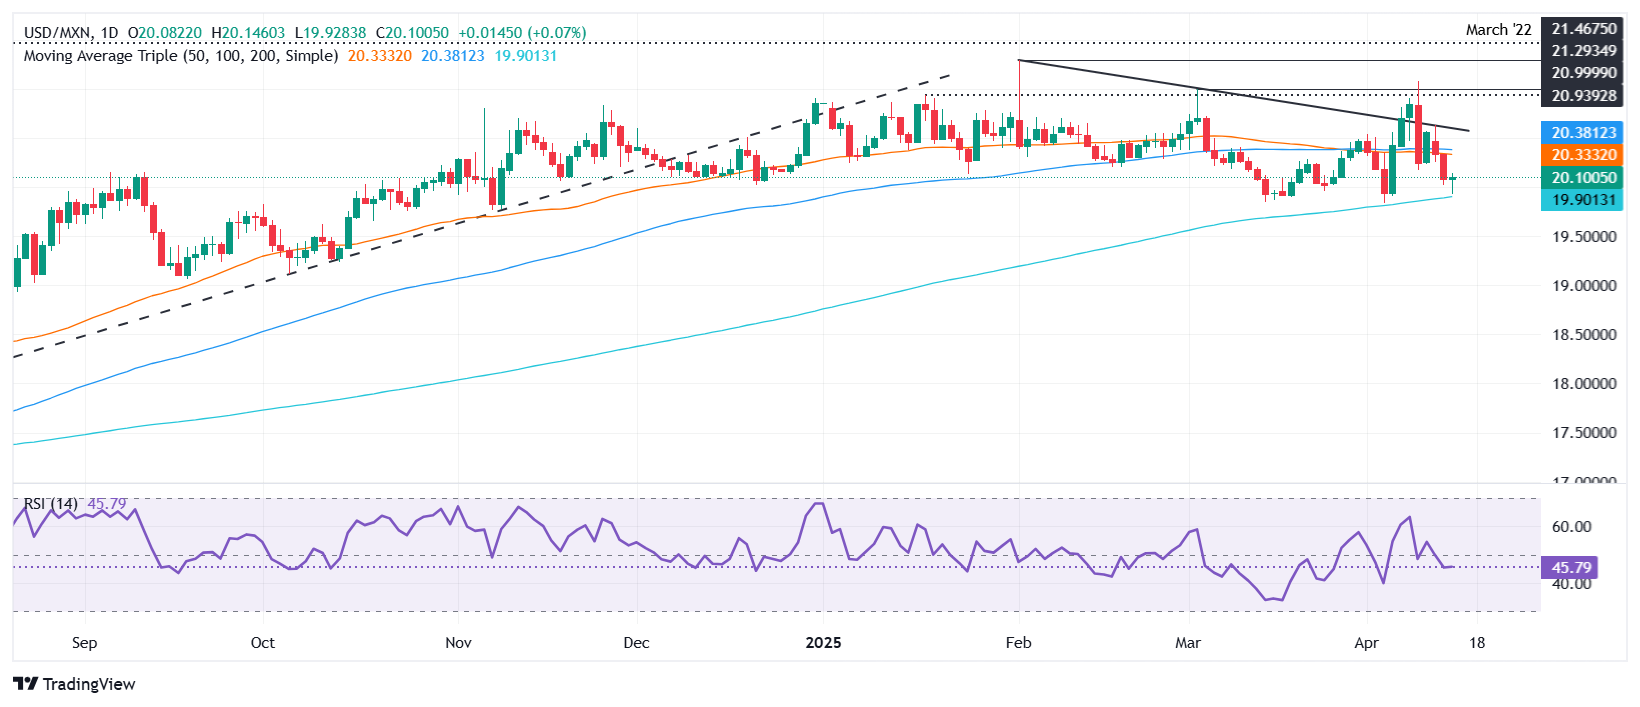
The USD/MXN uptrend stays alive, yet the exotic pair fell briefly below 20.00, near the 200-day Simple Moving Average (SMA) at 19.86. However, it seems poised to close the day above 20.00, paving the way for buyers to push prices higher.
If buyers drive the exotic pair past April 14's high of 20.29, the next resistance would be the confluence of the 50-day and 100-day Simple Moving Averages (SMAs) near 20.30 /36, followed by the 20.50 figure. Once hurdle, the next stop would be the April 9 daily peak of 21.07. Conversely, if USD/MXN tumbles below 20.00, look for a test of the 200-day SMA at 19.86.
Mexican Peso FAQs
The Mexican Peso (MXN) is the most traded currency among its Latin American peers. Its value is broadly determined by the performance of the Mexican economy, the country’s central bank’s policy, the amount of foreign investment in the country and even the levels of remittances sent by Mexicans who live abroad, particularly in the United States. Geopolitical trends can also move MXN: for example, the process of nearshoring – or the decision by some firms to relocate manufacturing capacity and supply chains closer to their home countries – is also seen as a catalyst for the Mexican currency as the country is considered a key manufacturing hub in the American continent. Another catalyst for MXN is Oil prices as Mexico is a key exporter of the commodity.
The main objective of Mexico’s central bank, also known as Banxico, is to maintain inflation at low and stable levels (at or close to its target of 3%, the midpoint in a tolerance band of between 2% and 4%). To this end, the bank sets an appropriate level of interest rates. When inflation is too high, Banxico will attempt to tame it by raising interest rates, making it more expensive for households and businesses to borrow money, thus cooling demand and the overall economy. Higher interest rates are generally positive for the Mexican Peso (MXN) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken MXN.
Macroeconomic data releases are key to assess the state of the economy and can have an impact on the Mexican Peso (MXN) valuation. A strong Mexican economy, based on high economic growth, low unemployment and high confidence is good for MXN. Not only does it attract more foreign investment but it may encourage the Bank of Mexico (Banxico) to increase interest rates, particularly if this strength comes together with elevated inflation. However, if economic data is weak, MXN is likely to depreciate.
As an emerging-market currency, the Mexican Peso (MXN) tends to strive during risk-on periods, or when investors perceive that broader market risks are low and thus are eager to engage with investments that carry a higher risk. Conversely, MXN tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















