Mexican Peso dwindles on recession jitters, awaits Trump’s announcement
- Mexican Peso tumbles for the fourth-straight day as US trade policies damage Mexico’s economy.
- Banxico slashes rates by 50 bps and signals additional cuts amid recession risks.
- US recession odds rise as Chicago PMI remains contractionary despite slight gains.
The Mexican Peso (MXN) begins the week on the back foot against the US Dollar (USD), mainly due to a deteriorating risk appetite as investors brace for the release of US tariffs on April 2, the US Liberation Day. At the time of writing, the USD/MXN trades at 20.45, up 0.50%.
Tariffs continue to drive price action as investors shifted to a risk-averse stance, which also weighs on high-beta currencies like the Mexican Peso. Last week, Banco de Mexico (Banxico) reduced rates by 50 basis points (bps) to 9%, while hinting that a further cut of the same magnitude looms.
Regarding this, JP Morgan supports another 50 bps cut due to the risks of an imminent recession, according to Steven Palacio, an analyst at the bank.
“It's inevitable that Mexico will go through a recession because the tariffs and the uncertainty surrounding their implementation are occurring in an economic context that was already in sharp decline,” Palacio said.
Meanwhile, Banxico’s Governor, Victoria Rodriguez Ceja, said the central bank will remain attentive to US trade policies and their impact on the country, with a primary focus on inflation, as she stated in an interview with El Financiero.
Across the northern border, the Chicago PMI data improved but remained in contractionary territory for the sixteenth consecutive month. The Greenback shrugged off an increase of recession odds in the US, according to Goldman Sachs, with odds rising from 20% to 35% due to pessimism amongst households and businesses. White House comments that the administration will tolerate an economic slowdown did not help.
This week, the Mexican economic schedule will feature Business Confidence, S&P Global Manufacturing PMI, and Gross Fixed Investment figures. In the US, traders are focusing on the April 2 Trump tariff announcement, the ISM Manufacturing PMI for March, JOLTS Job Openings and Nonfarm Payrolls.
Daily digest market movers: Mexican Peso falls as Banxico’s signals more cuts coming
- Mexico’s Business Confidence in February was 50.4. A reading below that level would indicate that companies are becoming pessimistic about the economy, with the result being its lowest level since May 2021.
- S&P Global Manufacturing PMI remained in contractionary territory for eight straight months at 47.6 in February. A March print beneath this would suggest the economic slowdown is deeper than foreseen.
- The Chicago PMI data for March increased by 47.6 points from 45.5 and exceeded the forecast of 45.2.
- Traders had priced the Fed to ease policy by 75 basis points (bps) throughout the year, according to data from the Chicago Board of Trade.
USD/MXN technical outlook: Mexican Peso treads water as USD/MXN bulls target 20.50
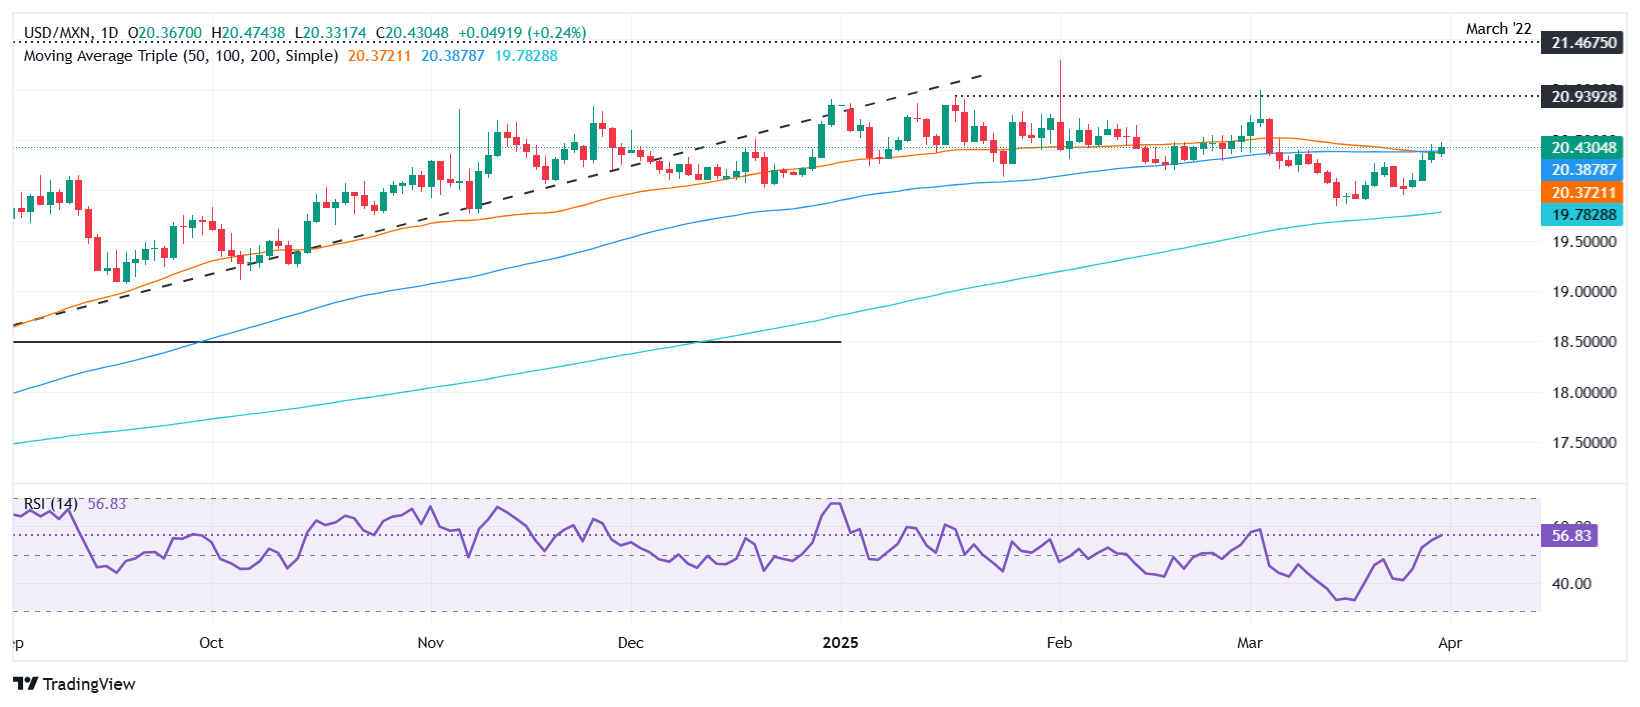
The USD/MXN continues to gather steam after clearing the confluence of the 100 and 50-day Simple Moving Averages (SMAs) near 20.35/36, which paved the way for 20.47, a new two-week high. The Relative Strength Index (RSI) indicates that buyers remain in control, with sufficient room to drive the exchange rate higher.
Therefore, the USD/MXN first resistance would be 20.50. If surpassed, the next ceiling would be the March 4 peak of 20.99, followed by the year-to-date (YTD) high of 21.28. Conversely, a drop below 20.35/36 paves the way to test the 20.00 mark.
Mexican Peso FAQs
The Mexican Peso (MXN) is the most traded currency among its Latin American peers. Its value is broadly determined by the performance of the Mexican economy, the country’s central bank’s policy, the amount of foreign investment in the country and even the levels of remittances sent by Mexicans who live abroad, particularly in the United States. Geopolitical trends can also move MXN: for example, the process of nearshoring – or the decision by some firms to relocate manufacturing capacity and supply chains closer to their home countries – is also seen as a catalyst for the Mexican currency as the country is considered a key manufacturing hub in the American continent. Another catalyst for MXN is Oil prices as Mexico is a key exporter of the commodity.
The main objective of Mexico’s central bank, also known as Banxico, is to maintain inflation at low and stable levels (at or close to its target of 3%, the midpoint in a tolerance band of between 2% and 4%). To this end, the bank sets an appropriate level of interest rates. When inflation is too high, Banxico will attempt to tame it by raising interest rates, making it more expensive for households and businesses to borrow money, thus cooling demand and the overall economy. Higher interest rates are generally positive for the Mexican Peso (MXN) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken MXN.
Macroeconomic data releases are key to assess the state of the economy and can have an impact on the Mexican Peso (MXN) valuation. A strong Mexican economy, based on high economic growth, low unemployment and high confidence is good for MXN. Not only does it attract more foreign investment but it may encourage the Bank of Mexico (Banxico) to increase interest rates, particularly if this strength comes together with elevated inflation. However, if economic data is weak, MXN is likely to depreciate.
As an emerging-market currency, the Mexican Peso (MXN) tends to strive during risk-on periods, or when investors perceive that broader market risks are low and thus are eager to engage with investments that carry a higher risk. Conversely, MXN tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















