Gold slumps on hawkish FOMC minutes, hurt rate cut hopes
- Gold trades down more than 1% after hitting a high of $2,426.
- US Treasury yields rise following hotter-than-expected UK inflation data.
- Wall Street Journal reports central banks in emerging markets added 2,200 tons of Gold since Q3 2022, driven by Western sanctions on Russia.
- Fed minutes reveal willingness to tighten policy further if economic risks materialize.

Gold plunged during the North American session on Wednesday, breaching below the $2,400 barrier, as traders seem to have booked profits ahead of the release of the last Federal Reserve (Fed) Meeting Minutes. Data from the United States (US) showed the housing market continued to show weakness, while Fed officials remained home after a busy week’s start.
The XAU/USD trades at $2,392, losing more than 1% after reaching a high of $2,426. US Treasury bond yields are rising following a hotter-than-expected inflation report from the UK, sending US yields higher. US equities are mixed ahead of NVIDIA’s earnings report release, while the Greenback edges up.
In the meantime, an article by The Wall Street Journal mentioned that Gold rallied due to central bank buying. According to the World Gold Council, central banks in emerging markets added around 2,200 tons of the golden metal since Q3 2022.
The article mentioned that the trigger might be Western sanctions on Russia after its invasion of Ukraine.
Aside from this, US Existing Home Sales plunged in April from 4.22 million to 4.14 million, or a -1.9 % contraction. Despite that, NAR Chief Economist Lawrence Yun said, “Home prices reaching a record high for the month of April is very good news for homeowners.”
Recently, the Fed released its latest meeting minutes, which showed that “Various participants mentioned willingness to tighten policy further should risks to outlook materialize and make such action appropriate.”
Daily digest market movers: Gold price falls as US yields climbed following hawkish Fed Minutes
- Gold prices tumble sharply as US Treasury yields rise and Greenback advances. The US 10-year Treasury bond yield edges up 2 basis points to 4.434%, while the US Dollar Index (DXY), which tracks the Greenback’s performance against a basket of six other currencies, is up 0.19% at 104.82, a headwind for XAU/USD.
- The FOMC Minutes showed that Fed officials remained uncertain about the degree of policy restrictiveness. They added that “it would take longer than previously anticipated to gain greater confidence in inflation moving sustainably to 2%.”
- During the week, speeches by Fed officials laid the ground for the “hawkish tilt” of the FOMC’s Minutes, as most officials commented they would like to be certain that inflation is edging down and that they’re not in a rush to lower the fed funds rate.
- Data from the Chicago Board of Trade shows investors are expecting 31 basis points of Fed easing toward the end of the year.
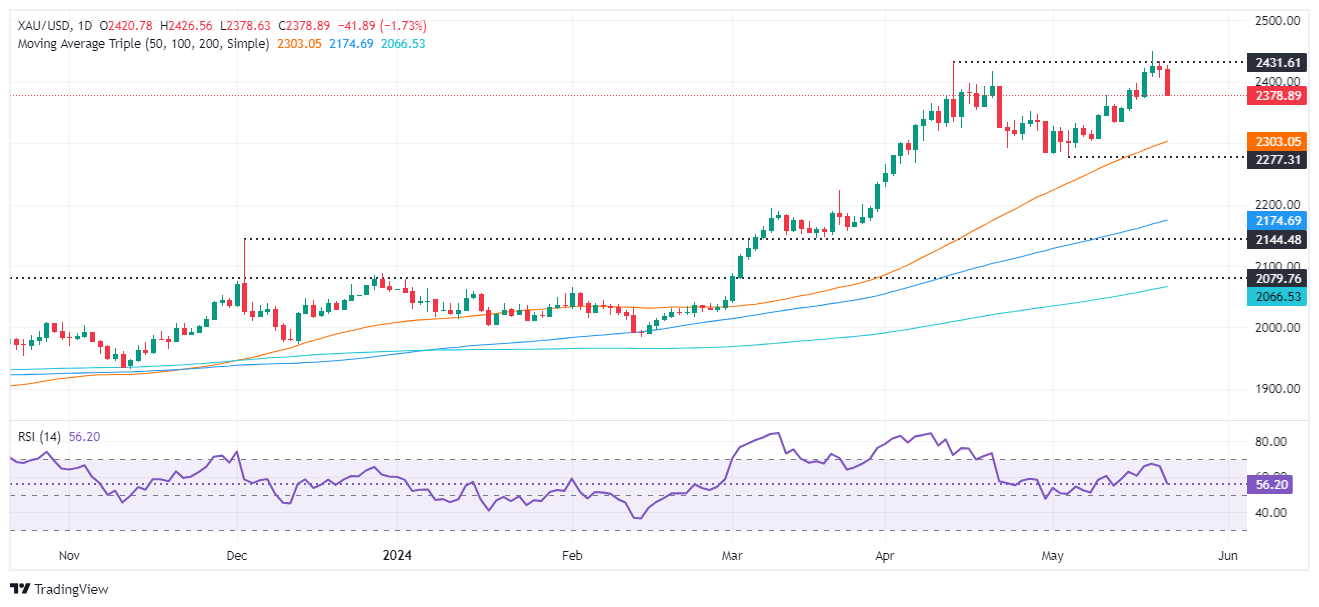
Technical analysis: Gold price slides below $2,400 as bears target $2,330
Gold price’s uptrend remains in place, yet Wednesday’s pullback could pave the way to test lower prices. Momentum is shifting negatively as the Relative Strength Index (RS), despite standing bullish, is aiming downwards. With that said, buying pressure is waning as sellers step in.
That said, the XAU/USD’s first support would be the May 13 low at $2,332, followed by the May 8 low of $2,303. Once those levels are surpassed, the 50-day Simple Moving Average (SMA) at $2,284 will be up next.
On the other hand, if buyers push the Gold price above $2,400, look for a retest of year-to-date highs at $2,450.
Gold FAQs
Gold has played a key role in human’s history as it has been widely used as a store of value and medium of exchange. Currently, apart from its shine and usage for jewelry, the precious metal is widely seen as a safe-haven asset, meaning that it is considered a good investment during turbulent times. Gold is also widely seen as a hedge against inflation and against depreciating currencies as it doesn’t rely on any specific issuer or government.
Central banks are the biggest Gold holders. In their aim to support their currencies in turbulent times, central banks tend to diversify their reserves and buy Gold to improve the perceived strength of the economy and the currency. High Gold reserves can be a source of trust for a country’s solvency. Central banks added 1,136 tonnes of Gold worth around $70 billion to their reserves in 2022, according to data from the World Gold Council. This is the highest yearly purchase since records began. Central banks from emerging economies such as China, India and Turkey are quickly increasing their Gold reserves.
Gold has an inverse correlation with the US Dollar and US Treasuries, which are both major reserve and safe-haven assets. When the Dollar depreciates, Gold tends to rise, enabling investors and central banks to diversify their assets in turbulent times. Gold is also inversely correlated with risk assets. A rally in the stock market tends to weaken Gold price, while sell-offs in riskier markets tend to favor the precious metal.
The price can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can quickly make Gold price escalate due to its safe-haven status. As a yield-less asset, Gold tends to rise with lower interest rates, while higher cost of money usually weighs down on the yellow metal. Still, most moves depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAU/USD). A strong Dollar tends to keep the price of Gold controlled, whereas a weaker Dollar is likely to push Gold prices up.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















