Gold loses its bright amid mixed market mood
- Gold falls 1%, retreating from $2,350, despite typically supportive lower US Treasury yields.
- US economic events, including inflation data and a speech by Fed Chair Powell, are poised to influence markets.
- Fed Vice-Chairman Jefferson was hawkish, stressed importance of driving inflation toward 2% target.

Gold prices retreated sharply on Monday from near $2,350 even though US Treasury yields declined, undermining appetite for the Greenback. Traders brace for a busy economic docket in the United States (US) led by the release of inflation figures, Retail Sales, and the May 14 speech of Federal Reserve (Fed) Chair Jerome Powell.
Earlier on Monday, Fed Vice-Chairman Philip Jefferson addressed the media in a Q&A session at the Cleveland Fed. He said, “We continue to look for additional evidence that inflation is going to return to our 2% target.”
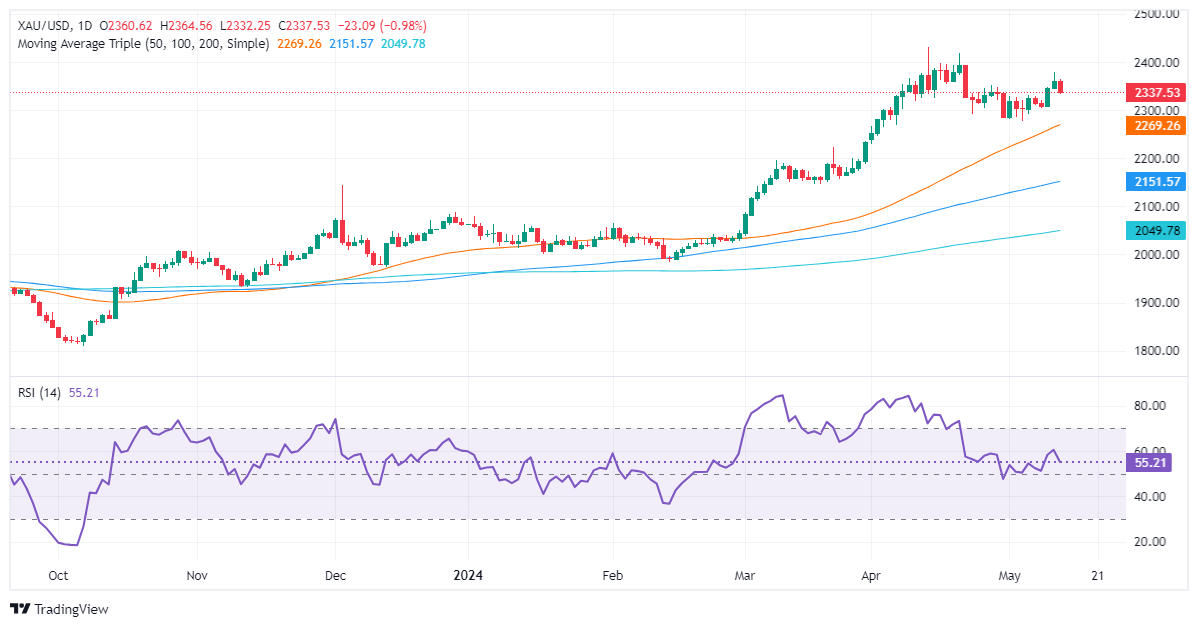
The XAU/USD trades at $2,336, down 1% amid a risk-on impulse. Wall Street continues to post gains. Recent labor market data, such as April’s Nonfarm Payrolls and last week’s Initial Unemployment Claims, could pressure the Fed. In its latest monetary policy statement, officials recognized that the risks to achieving the Fed's dual mandate of fostering maximum employment and price stability have become more balanced over the past year.
Meanwhile, the US Bureau of Labor Statistics (BLS) is expected to release the producer and consumer inflation data for April on May 14 and 15. If price pressures reaccelerate, the Fed can hold rates “higher for longer.”
Daily digest market movers: Gold falls as US data could influence Fed’s rate path
- Gold prices fell amid lower US Treasury yields and a strong US Dollar. The US 10-year Treasury note yields 4.479% and is down two basis points (bps) from its opening level. The US Dollar Index (DXY), which tracks the Greenback's performance against six other currencies, falls 0.10% to 105.20.
- The Producer Price Index (PPI) for April is expected to be at 0.3% MoM, a tenth above the prior month’s number. Core PPI is foreseen at 0.2% MoM, unchanged compared to March.
- April’s Consumer Price Index (CPI) is projected to remain unchanged compared to March’s reading at 0.4% MoM. The Core CPI is expected to resume its lower trend from 0.4% in March to 0.3% MoM.
- Investors are eyeing Fed Chair Jerome Powell's speech on May 14.
- Further data will be featured during the week, led by Retail Sales on May 15, Initial Jobless Claims, and Industrial Production on May 16.
- The New York Federal Reserve released its monthly Survey of Consumer Expectations on Monday, showing that the year's inflation expectations increased to 3.3% vs. 3% in March. The data came after the University of Michigan Consumer Sentiment poll showed that inflation expectations for a one-year outlook rose from 3.2% to 3.5%.
- Interest rate cut expectations toward the end of the year remain at 34 basis points (bps), according to data provided by the Chicago Board of Trade (CBOT).
Technical analysis: Gold price tumbles below $2,350 with bears eyeing $2,300
The uptrend in the Gold price remains intact, even though from a technical perspective the formation of a quasi Shooting Star candlestick pattern followed by a bearish Belt Hold line opened the door for a leg down. Although momentum favors buyers, the short term is aiming lower, meaning they’re losing traction.
Hence, XAU/USD's first support would be the May 9 low of $2,306, followed by the $2,300 figure. Once cleared, the next stop would be the 50-day Simple Moving Average (SMA) at $2,249.
On the other hand, if buyers reclaim $2,359, look for a test of the April 26 high at $2,352. A breach of the latter would expose the $2,400 figure, immediately followed by the April 19 high at $2,417 and the all-time high of $2,431.
Gold FAQs
Gold has played a key role in human’s history as it has been widely used as a store of value and medium of exchange. Currently, apart from its shine and usage for jewelry, the precious metal is widely seen as a safe-haven asset, meaning that it is considered a good investment during turbulent times. Gold is also widely seen as a hedge against inflation and against depreciating currencies as it doesn’t rely on any specific issuer or government.
Central banks are the biggest Gold holders. In their aim to support their currencies in turbulent times, central banks tend to diversify their reserves and buy Gold to improve the perceived strength of the economy and the currency. High Gold reserves can be a source of trust for a country’s solvency. Central banks added 1,136 tonnes of Gold worth around $70 billion to their reserves in 2022, according to data from the World Gold Council. This is the highest yearly purchase since records began. Central banks from emerging economies such as China, India and Turkey are quickly increasing their Gold reserves.
Gold has an inverse correlation with the US Dollar and US Treasuries, which are both major reserve and safe-haven assets. When the Dollar depreciates, Gold tends to rise, enabling investors and central banks to diversify their assets in turbulent times. Gold is also inversely correlated with risk assets. A rally in the stock market tends to weaken Gold price, while sell-offs in riskier markets tend to favor the precious metal.
The price can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can quickly make Gold price escalate due to its safe-haven status. As a yield-less asset, Gold tends to rise with lower interest rates, while higher cost of money usually weighs down on the yellow metal. Still, most moves depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAU/USD). A strong Dollar tends to keep the price of Gold controlled, whereas a weaker Dollar is likely to push Gold prices up.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.















