Gold recovers as US inflation dips, limited by risk-on mood
- XAU/USD climbs toward $3,250 as soft US inflation data boosts sentiment, but Fed stance caps gains.
- April CPI misses slightly, easing US Dollar pressure with limited immediate impact from tariffs.
- Analysts caution inflation may rise as tariffs gradually push up goods prices.
- Fed expected to cut rates twice in 2025; focus shifts to US PPI and Retail Sales for guidance.
Gold prices traded with a positive tone on Tuesday, following Monday’s drop of over 2.70%, exchanged hands at around $3,250, up by 0.42%. A softer-than-expected US inflation report and the trade truce between China and the US may keep Gold prices capped beneath the $3,300 figure.
US inflation data for April was slightly softer than expected by market participants on a monthly basis. Annual basis figures were aligned with projections, indicating that the tariff effect has not been reflected so far in the “hard data.”
Meanwhile, analysts at a major US commercial bank revealed that tariffs have boosted goods prices, “but larger increases are in the pipeline.”
Money market participants are still seeing a restrictive Federal Reserve (Fed). The December 2025 fed funds rate futures contract estimates the US central bank will ease 52 basis points of easing. This implies two rate cuts as Fed officials projected since last year’s December meeting, further confirmed by the latest Summary of Economic Projections in March.
Ahead this week, traders are eyeing the release of the Producer Price Index (PPI) and US Retail Sales data.
Daily digest market movers: Gold price edged up, still capped by high US Treasury yields
- US Treasury bond yields are climbing with the US 10-year Treasury note yield edging up 1.5 basis points to 4.489%. Meanwhile, US real yields are also steady at 2.199% as indicated by the US 10-year Treasury Inflation-Protected Securities yields.
- The US CPI in April expanded by 0.2% MoM, below forecasts of 0.3%, but up from March’s -0.1% number. Core CPI rose by 0.2% MoM, up from the previous month but beneath estimates of 0.3%.
- On an annual basis, the US CPI increased by 2.3% YoY, a tenth below estimates and the previous month's reading, and core metrics remained unchanged at 2.8% YoY.
- The announcement of a tariff agreement between the US and China improved risk appetite and sent Bullion prices plunging. Nevertheless, traders should be aware of recent developments regarding US trade policies and geopolitics as new catalysts could emerge and push Gold prices in either direction.
- The World Gold Council revealed that the People’s Bank of China added 2 tonnes to its Gold reserves in April – for the sixth consecutive month. The National Bank of Poland increased by 12 tonnes in April to 509 tonnes; while the Czech National Bank increased its reserves by 2.5 tonnes in April.
XAU/USD technical outlook: Gold price advances steadily with buyers eyeing $3,250
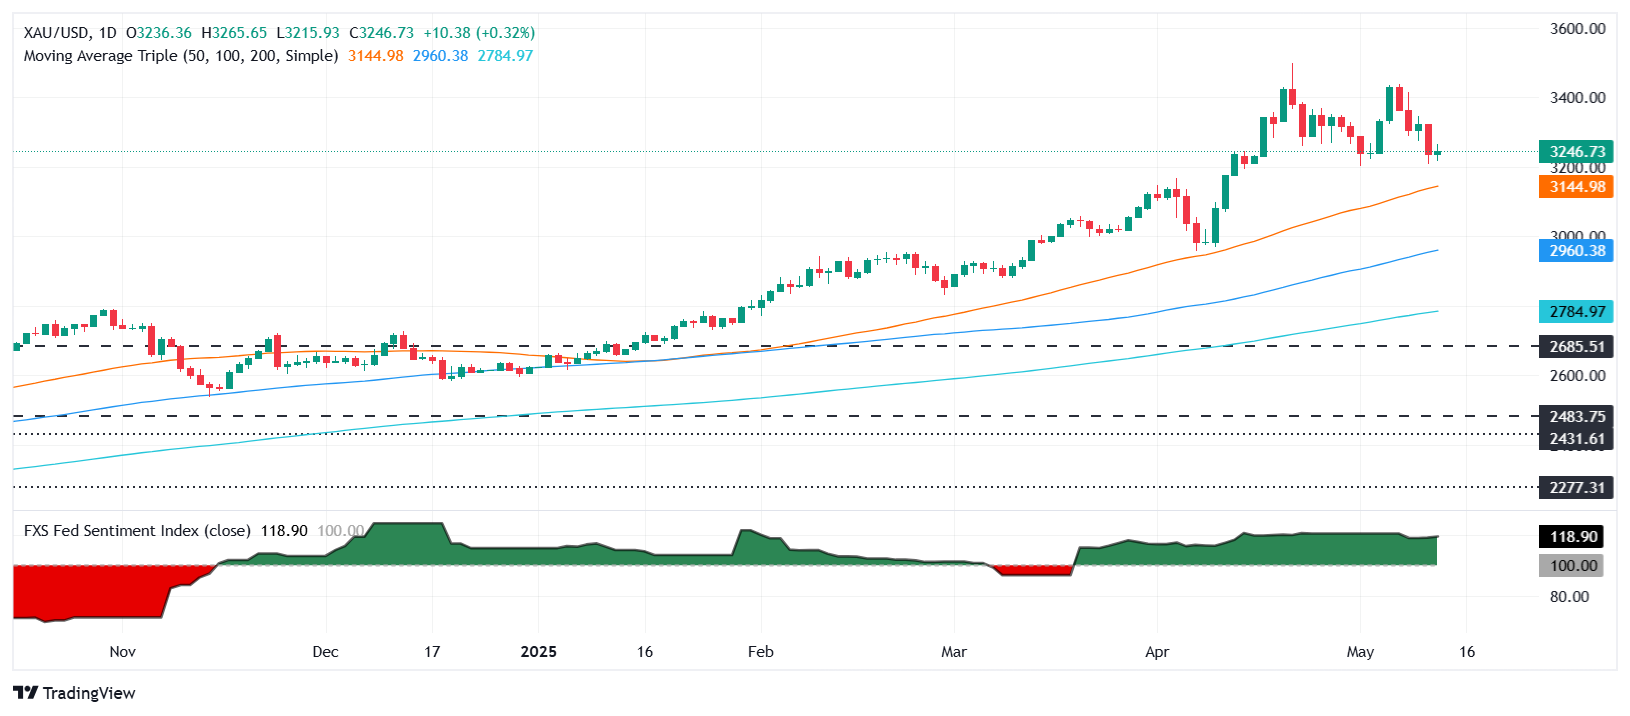
The Gold price rally has stalled, yet a “double-top” candle chart appears to be emerging, which could send XAU/USD prices toward the $3,000 figure and beyond. Momentum shows that buyers' strength is fading and that sellers are stepping in.
For a double-top confirmation, sellers must clear the May 1 low of $3,202. Once surpassed, the next stop would be $3,100, $3,000, and the minimum objective at $2,950.
Conversely, If XAU/USD edges back above $3,300, buyers will face the next resistance at $3,350. If surpassed, the next ceiling level would be $3,400 and beyond.
Inflation FAQs
Inflation measures the rise in the price of a representative basket of goods and services. Headline inflation is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core inflation excludes more volatile elements such as food and fuel which can fluctuate because of geopolitical and seasonal factors. Core inflation is the figure economists focus on and is the level targeted by central banks, which are mandated to keep inflation at a manageable level, usually around 2%.
The Consumer Price Index (CPI) measures the change in prices of a basket of goods and services over a period of time. It is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core CPI is the figure targeted by central banks as it excludes volatile food and fuel inputs. When Core CPI rises above 2% it usually results in higher interest rates and vice versa when it falls below 2%. Since higher interest rates are positive for a currency, higher inflation usually results in a stronger currency. The opposite is true when inflation falls.
Although it may seem counter-intuitive, high inflation in a country pushes up the value of its currency and vice versa for lower inflation. This is because the central bank will normally raise interest rates to combat the higher inflation, which attract more global capital inflows from investors looking for a lucrative place to park their money.
Formerly, Gold was the asset investors turned to in times of high inflation because it preserved its value, and whilst investors will often still buy Gold for its safe-haven properties in times of extreme market turmoil, this is not the case most of the time. This is because when inflation is high, central banks will put up interest rates to combat it. Higher interest rates are negative for Gold because they increase the opportunity-cost of holding Gold vis-a-vis an interest-bearing asset or placing the money in a cash deposit account. On the flipside, lower inflation tends to be positive for Gold as it brings interest rates down, making the bright metal a more viable investment alternative.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















