GBP/JPY Price Forecast: Holds near 206.00 after refreshing yearly high
- GBP/JPY trades at 205.85, up 0.49%, after touching a new yearly high of 206.86 before easing lower.
- RSI remains in overbought territory, signaling buyers retain control despite rejection from the 207.00 region.
- Key resistance sits at 206.00 and 206.86, while support lies at 205.00 and 204.23 ahead of the 204.00 zone.
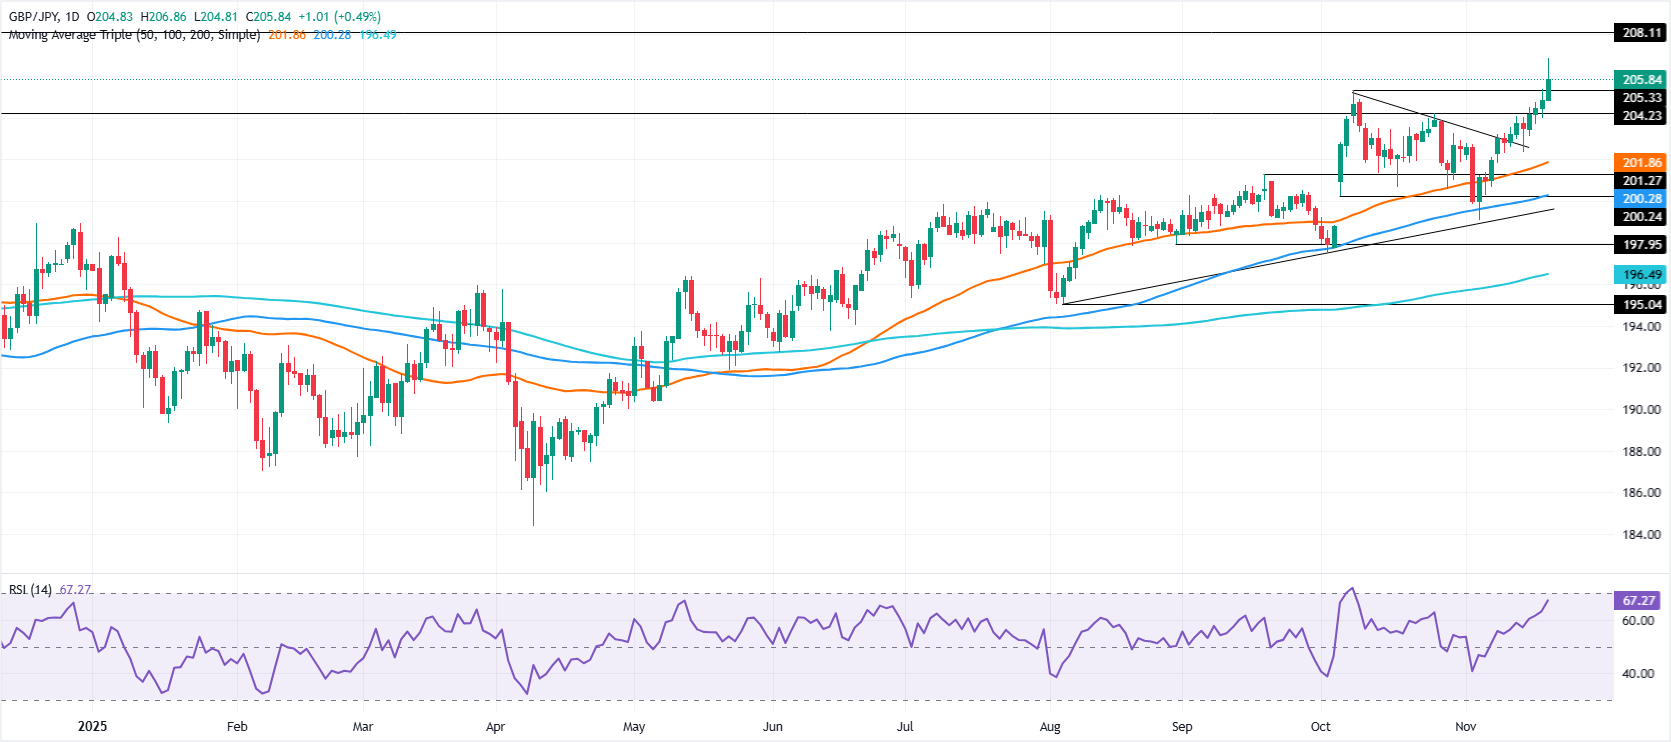
The GBP/JPY extended its rally for the fourth straight day, yet it trades below the 206.00 figure after refreshing yearly highs at 206.86 on Thursday. At the time of writing, the cross-pair trades at 205.85 up 0.49%.
GBP/JPY Price Forecast: Technical outlook
The technical picture remains upward biased, but the GBP/JPY faced 207.00 but failed to clear the latter, retreating more than 100 pips toward the current exchange rate. Despite this, the mood remains positive as depicted by the Relative Strength Index (RSI) closing in overbought territory, an indication that buyers are in charge.
As of writing, GBP/JPY first key resistance would be 206.00, followed by November’s 20 peak at 206.86. A breach of the latter will expose 207.00 and the July 11, 2024, peak at 208.11.
Support is seen at 205.00. Below here, the next stop would be July 19, 2024, high turned support at 204.23, before aiming towards 204.00.
GBP/JPY Price Chart – Daily
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















