EUR/USD struggles to find room to move
- EUR/USD waffled on Monday, stuck near 1.0400 ahead of the midweek holiday.
- Global markets are set to go dark during the New Year’s holiday session.
- Mid-tier German labor figures, US ISM PMI data are the key releases this week.

On Monday, EUR/USD dipped below the 1.0400 mark as the market navigates the year-end holiday period. Trading volumes are low, and investors are hesitant to make significant moves, leading to a decline in risk appetite, affecting most asset classes and pushing them to the lower end of their recent ranges.
German stock markets will close on Tuesday and Wednesday for the New Year’s Eve and New Year’s Day holidays. The final HCOB Manufacturing Purchasing Managers Index (PMI) data for Germany is expected on Thursday; however, the final figures are not likely to generate significant momentum for the Euro. Additionally, labor statistics for Germany, including a projected increase in December's Unemployment Change to 15K from 7K, will be released on Friday.
The primary data to watch this week will be the US ISM PMI figures for December, scheduled for release on Friday. The ISM Manufacturing PMI is forecasted to decrease slightly to 48.3 from 48.4. Throughout the latter half of the week, several Federal Reserve policymakers are expected to speak, aiming to clarify and reassure the market regarding the Fed’s recent adjustments to anticipated rate cuts in 2024.
EUR/USD price forecast
As EUR/USD rebounds to the lower end of 1.0400, the recent price floor around 1.0350 becomes crucial. The price has gradually decreased since the Fiber began its decline from the September highs just above 1.1200.
While it has not yet dropped below the mid-November low of 1.0332, EUR/USD is on track to finish in the negative for a fifth straight week. Observers focusing on longer timeframes will notice that the Fiber has closed lower in all but two of the last 13 weeks.
EUR/USD daily chart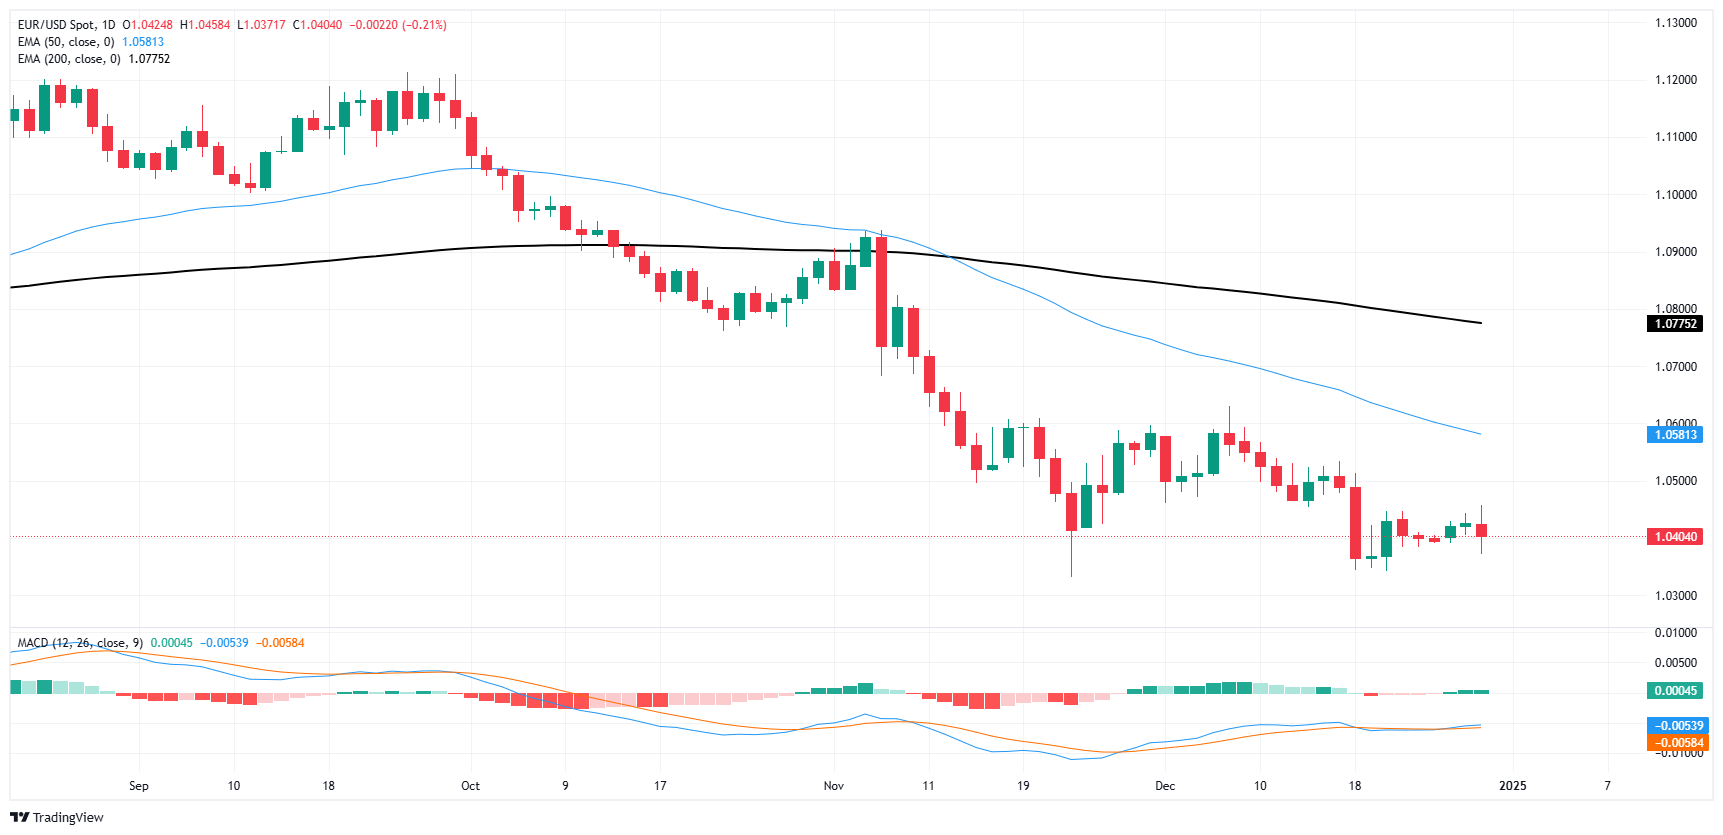
Euro FAQs
The Euro is the currency for the 19 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















