Canadian Dollar trudges higher after key US jobs data sparks further risk appetite
- The Canadian Dollar outpaced the US Dollar on Thursday.
- Market-thumping US NFP jobs data muscled the Loonie over the Greenback.
- Rebounding market sentiment is keeping the US Dollar under pressure and bolstering CAD.
The Canadian Dollar (CAD) caught further lift on Thursday, rising against the US Dollar (USD) after US Nonfarm Payrolls (NFP) job gains wiped out market fears of a weakening US labor sector. ADP job gains teased a possible contraction in headline job creation in June, but a sweltering uptick in government hiring across the US at the state and local levels obliterated an overall slower pace of job gains elsewhere.
The Canadian side of the economic calendar remains a limited affair, at least until the next batch of key Canadian inflation figures due mid-month. The Bank of Canada’s (BoC) latest rate call is also slated for far off at the end of the month. Loonie traders continue to twist around will-they-won’t-they bets of another rate cut from the BoC, and odds are expected to whipsaw as the calendar grinds down to July 30.
Daily digest market movers: Canadian Dollar gains ground on upbeat NFP print.
- US NFP net job gains surged in June, rising to 147K on a seasonally-adjusted basis, bolstered by a strong uptick in education hiring at the state and local government levels.
- Despite the strong surge in hiring, analysts are warning it could be a one-off; governments are unlikely to maintain a strong pace of hiring.
- Meanwhile, tariff knock-on effects are still gripping the ‘real’ US economy: manufacturing, wholesale, and resource extraction jobs all posted declines.
- The upbeat headline jobs print helped the market to shrug off this week’s labor sector fears after the ADP jobs preview failed to measure government hiring, and overstated potential declines in net labor.
- Canada’s own iteration of headline net job growth is slated to release next week on Friday, with the Federal Reserve’s (Fed) latest Meeting Minutes due next Wednesday.
Canadian Dollar price forecast
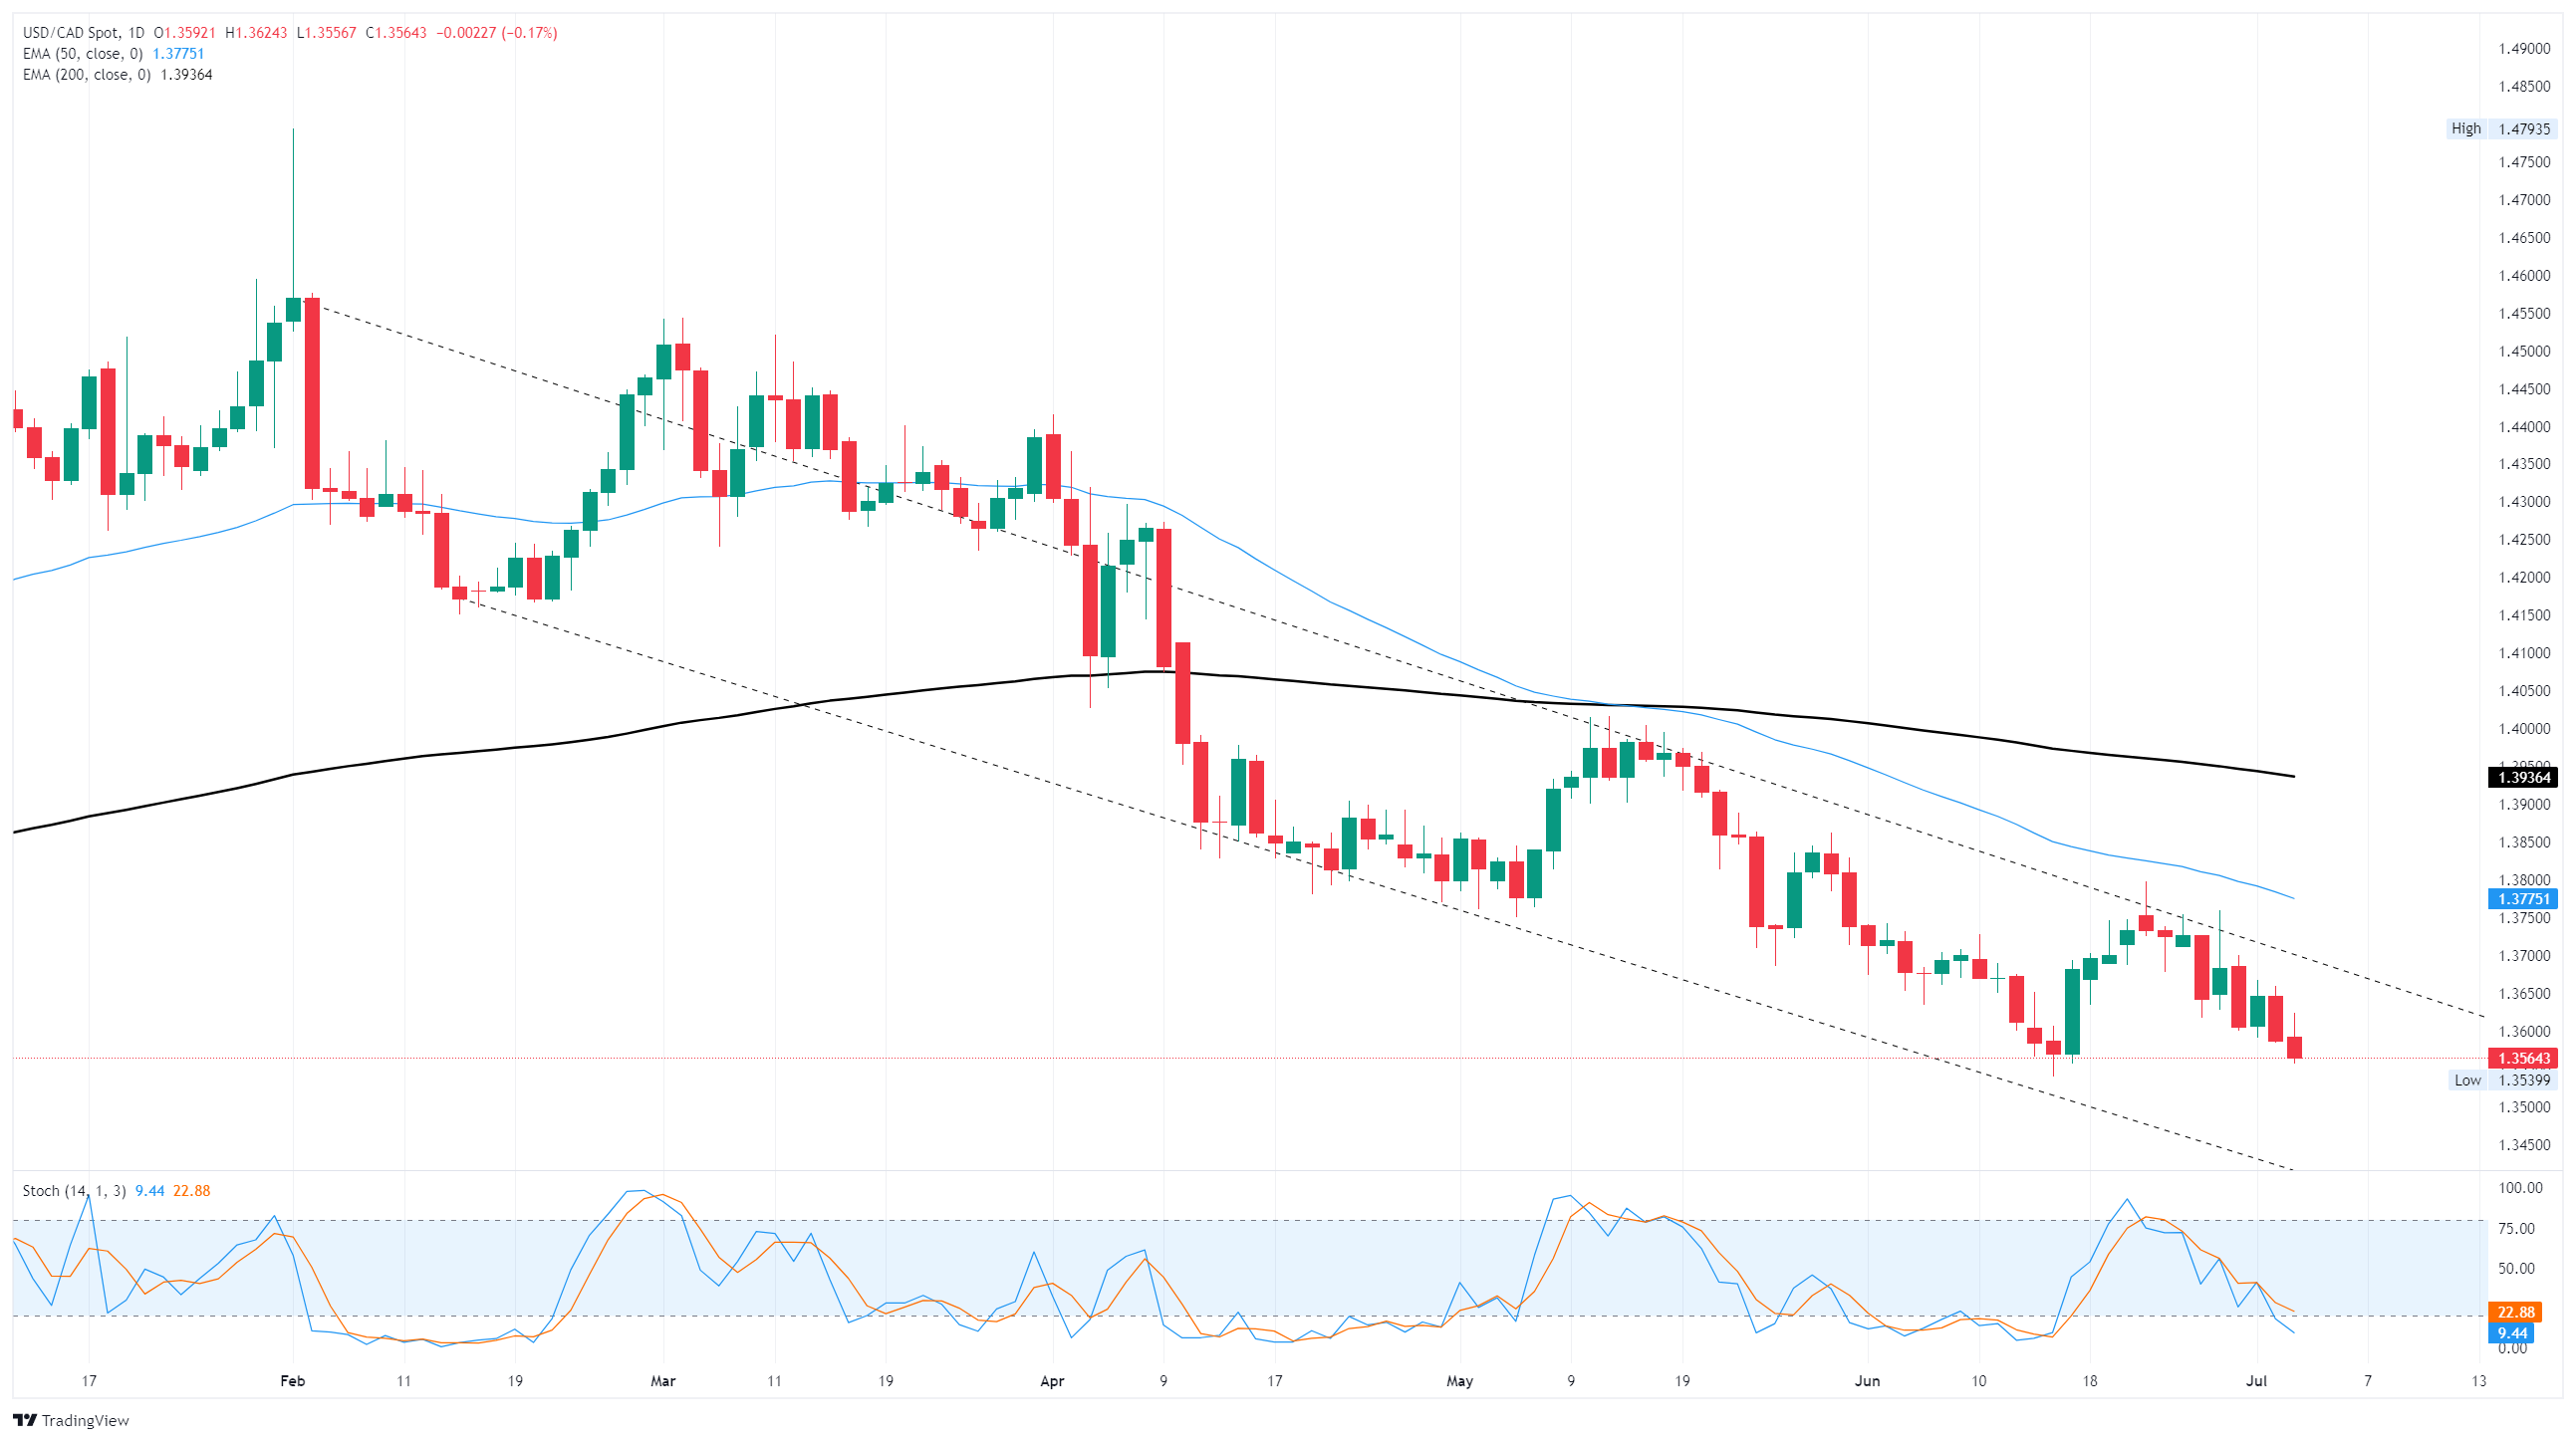
The Canadian Dollar is continuing its march higher against the US Dollar, driving the USD/CAD pair even closer to multi-month lows below 1.3540. The Loonie’s day-on-day gains against the Greenback have been halting, but the US Dollar’s ongoing weakness on the back of rising general market sentiment is still sending USD/CAD steadily lower.
USD/CAD has been on a steady decline ever since posting multi-decade highs in early February. Daily candlesticks are getting pushed lower by descending trendlines, and the pair continues to churn further into bear country below the 50-day Exponential Moving Average (EMA) near 1.3775.
USD/CAD daily chart
Canadian Dollar FAQs
The key factors driving the Canadian Dollar (CAD) are the level of interest rates set by the Bank of Canada (BoC), the price of Oil, Canada’s largest export, the health of its economy, inflation and the Trade Balance, which is the difference between the value of Canada’s exports versus its imports. Other factors include market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – with risk-on being CAD-positive. As its largest trading partner, the health of the US economy is also a key factor influencing the Canadian Dollar.
The Bank of Canada (BoC) has a significant influence on the Canadian Dollar by setting the level of interest rates that banks can lend to one another. This influences the level of interest rates for everyone. The main goal of the BoC is to maintain inflation at 1-3% by adjusting interest rates up or down. Relatively higher interest rates tend to be positive for the CAD. The Bank of Canada can also use quantitative easing and tightening to influence credit conditions, with the former CAD-negative and the latter CAD-positive.
The price of Oil is a key factor impacting the value of the Canadian Dollar. Petroleum is Canada’s biggest export, so Oil price tends to have an immediate impact on the CAD value. Generally, if Oil price rises CAD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Oil falls. Higher Oil prices also tend to result in a greater likelihood of a positive Trade Balance, which is also supportive of the CAD.
While inflation had always traditionally been thought of as a negative factor for a currency since it lowers the value of money, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Higher inflation tends to lead central banks to put up interest rates which attracts more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in Canada’s case is the Canadian Dollar.
Macroeconomic data releases gauge the health of the economy and can have an impact on the Canadian Dollar. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the CAD. A strong economy is good for the Canadian Dollar. Not only does it attract more foreign investment but it may encourage the Bank of Canada to put up interest rates, leading to a stronger currency. If economic data is weak, however, the CAD is likely to fall.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















