Why central banks are loading up on Gold during the current 30% correction
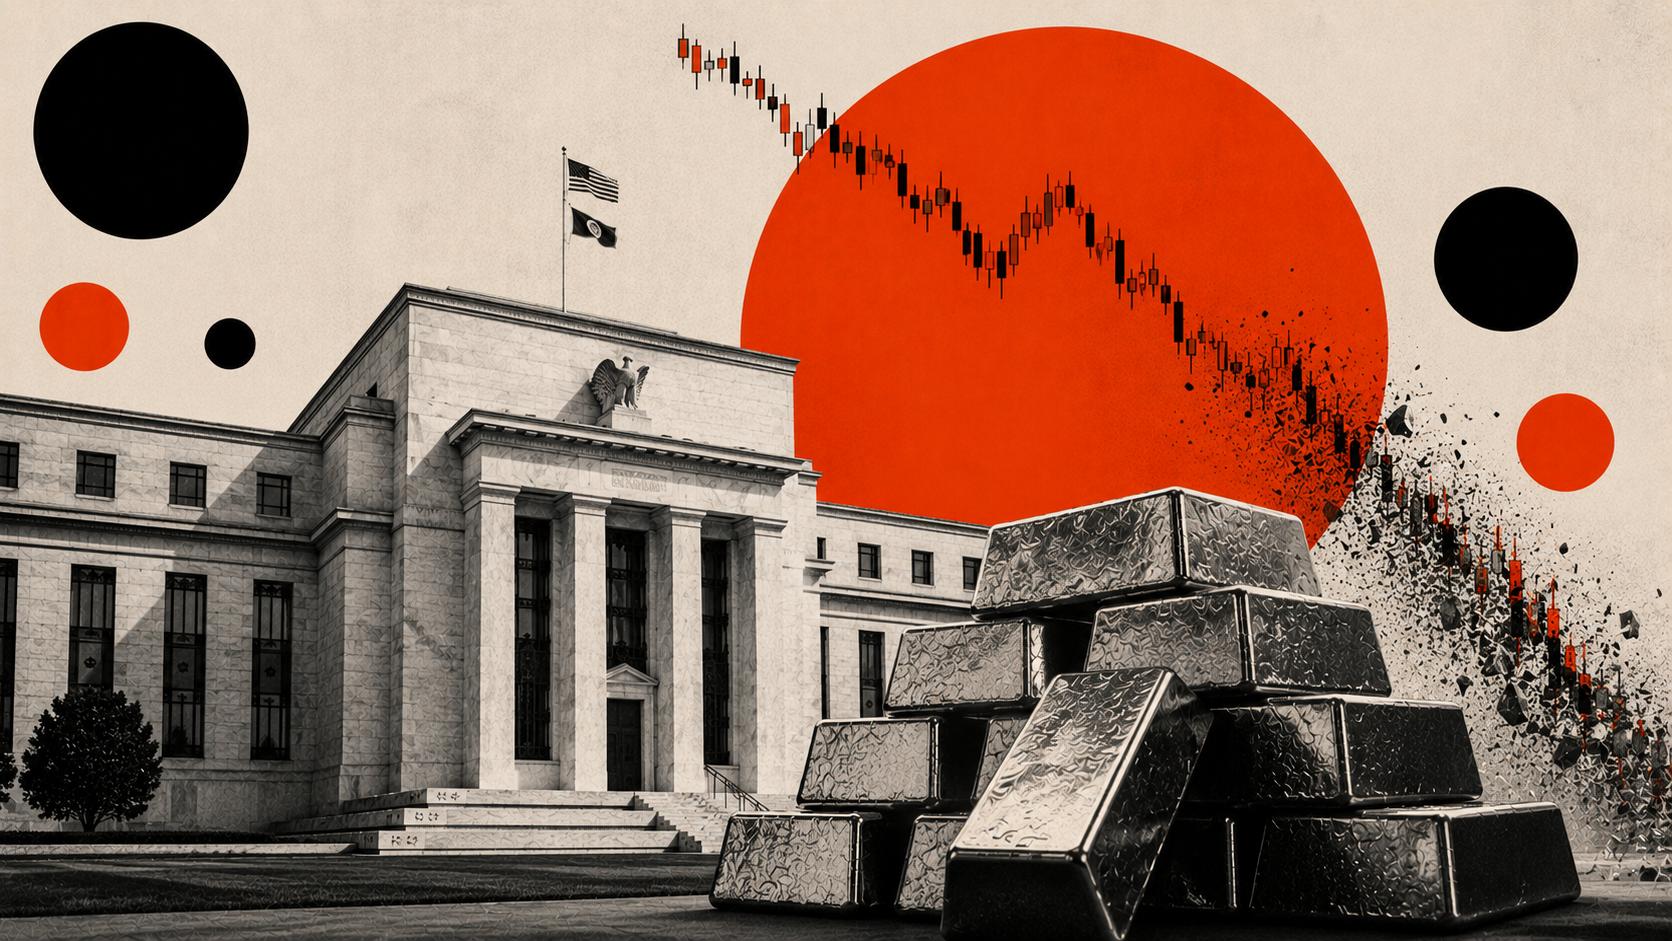
Gold has crashed from $5,500 to $4,000 in five months, marking a decline of almost 30% that has triggered widespread retail panic. However, this correction could present a significant opportunity, driven by an unprecedented market indicator: central bankers and the world's largest asset managers are aggressively buying. With the Chinese central bank logging its 19th straight month of purchases, institutional big money is loading up, suggesting that panic-selling the dip might be the wrong approach.
Understanding Gold's relationship with real interest rates
Historically, Gold has maintained a long-term inverse correlation with real interest rates. The real return on holding a 10-Year US Treasury note, meaning the yield payout discounted for the inflation rate in the United States, has traditionally moved in the opposite direction of Gold prices.
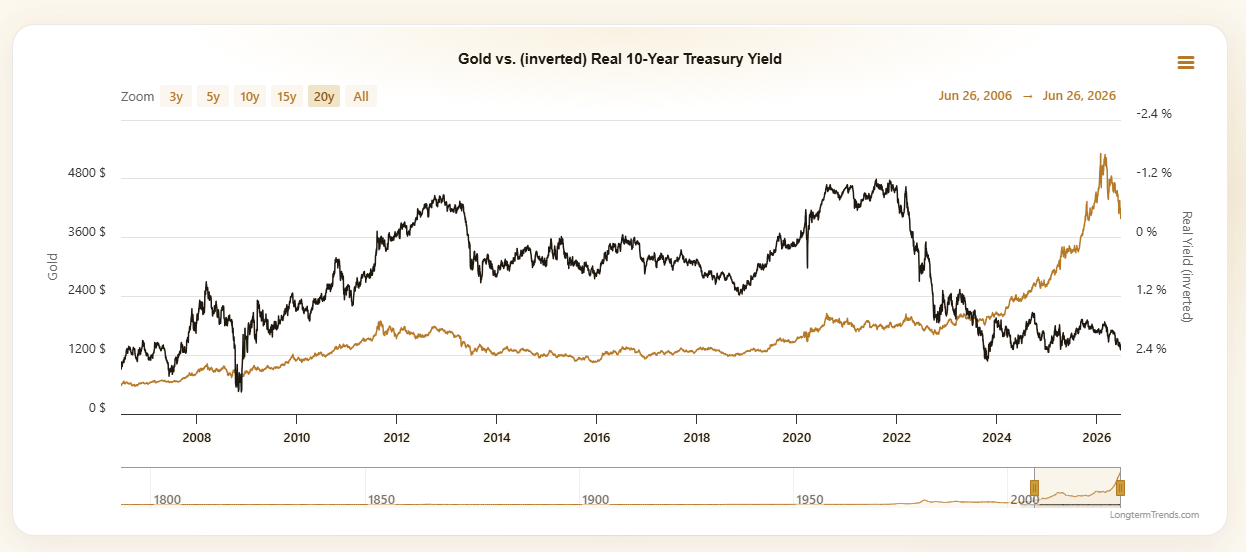
That relationship worked predictably for ages: when real rates rise, Gold falls, and vice versa; when real rates fall, Gold rises. This occurs because holding Gold pays no yield, making the bullion highly attractive to investors when government bonds, a safe-haven alternative, offer meager real returns.
The paradigm shift: Central banks ditch US Treasuries for Gold
This correlation had been working perfectly until 2024, when Donald Trump was elected again as US President and immediately enacted an America-first agenda, applying tariffs on the rest of the world.
Asset managers changed course and started dropping US Treasuries to buy Gold. Central bankers, who act as the world's largest asset managers, drove this massive shift. Central banks not only set interest rates and monetary policy but also manage foreign exchange reserves by buying and selling other currencies, bonds, and Gold.
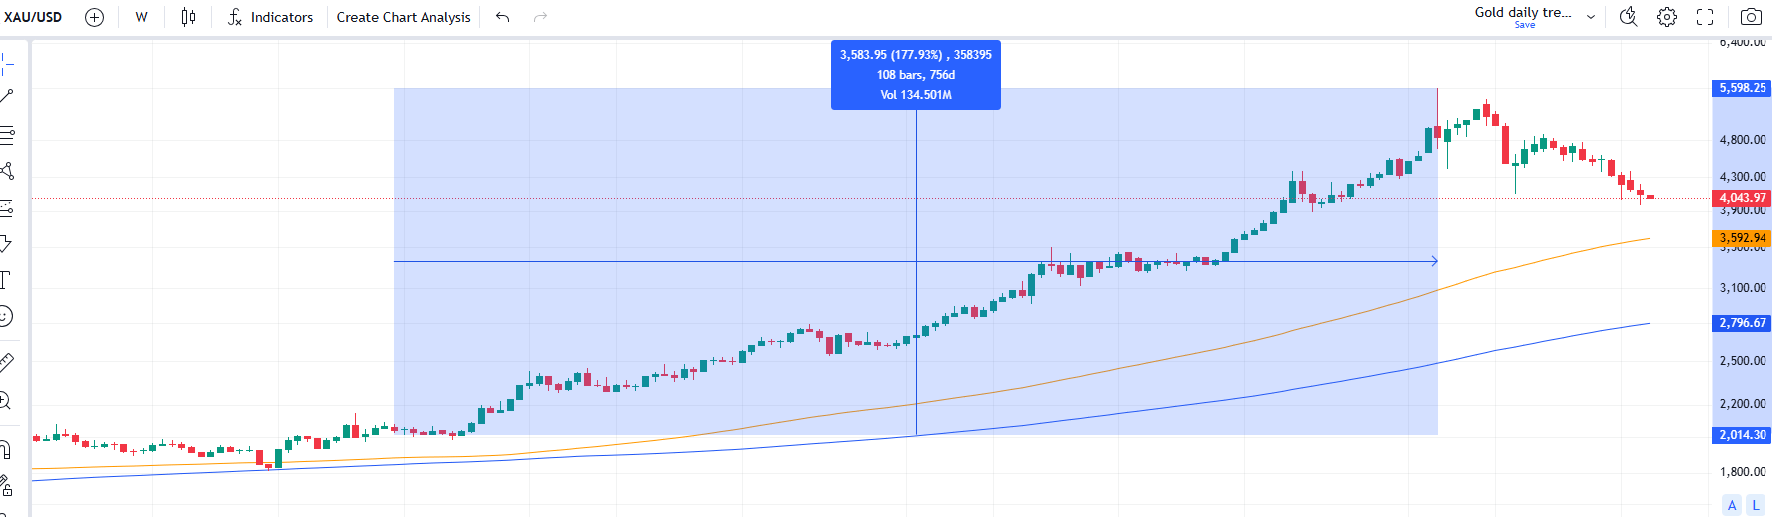
This intervention triggered the biggest Gold rally in history. In just over two years, from the start of 2024 to the peak in January 2026, Gold rallied from around $2,000 to $5,500, a 175% gain. For decades, central banks treated US Treasuries as the ultimate reserve asset, but that structural preference has fundamentally changed.
A historic shift in global reserve allocations
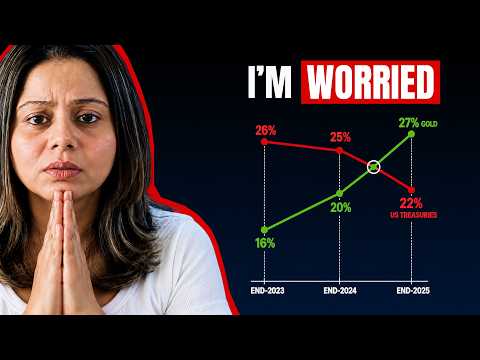
According to the latest ECB reserve report, Gold has officially overtaken US Treasuries in global reserve allocations. This is a key indicator of a development never seen before: the share of Gold in total official foreign reserves, comprising both foreign exchange and Gold holdings, increased to 27% at the end of 2025, surpassing US Treasuries at 22%.
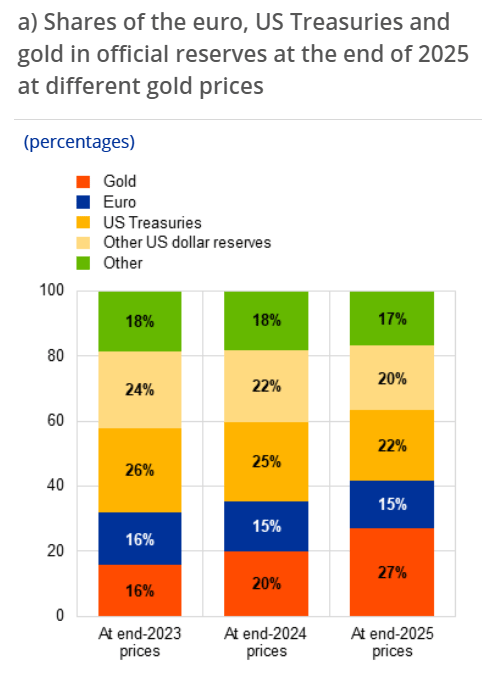
This historic shift demonstrates that central banks are becoming less dependent on sovereign debt and increasingly willing to hold an asset with no credit risk and no political liability. This is not speculative buying by short-term traders; it is a strategic change in how countries manage their currency reserves, playing out over years.
As proof of this trend, the People's Bank of China (PBoC), the largest holder of foreign exchange reserves in the world, added another 320,000 ounces of Gold in May, marking its 19th straight month of increasing its Gold reserves.
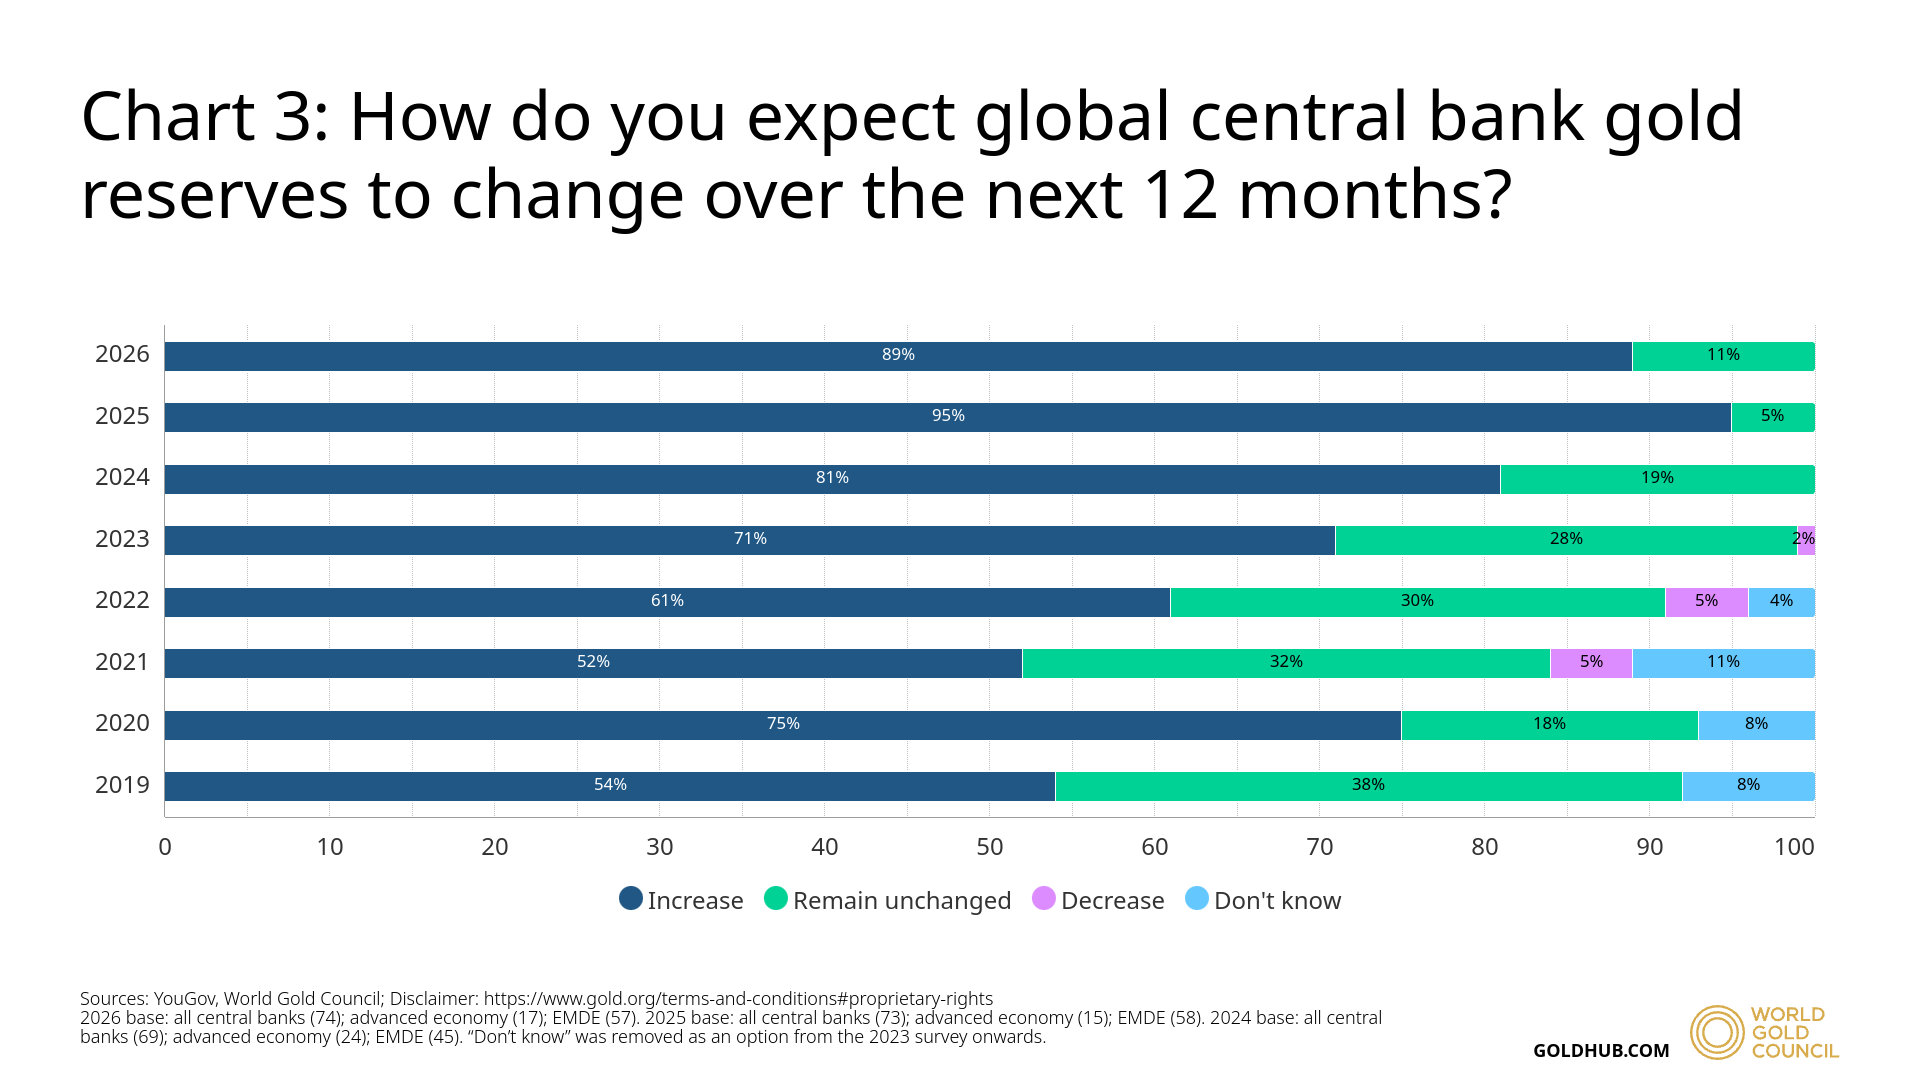
Furthermore, a recent World Gold Council survey on central bank gold reserves revealed that almost 90% of respondents expect global central bank gold reserves to increase over the next year, while the role of the US Dollar gradually declines. These are central bankers themselves confirming they will continue to buy Gold while diversifying away from US Dollar-backed assets.
Institutional strength vs. profit-taking
While central banks continue buying, investment funds have been doing the opposite recently.
Gold pulled back to around $4,000 after having peaked at $5,500 in late January. Throughout this correction, Gold ETF holdings have fallen to a 7.5-month low after reaching multi-year highs earlier this year, signaling that short-term investors are taking profits.
Despite the pullback, several banks, including JPMorgan, continue to argue that Gold's long-term fundamentals remain constructive. They cite the same persistent factors: steady central bank demand, geopolitical uncertainty, and diversification away from traditional reserve assets. This creates a fascinating divergence in which long-term buyers remain strong and committed, while short-term traders are becoming cautious.
What the options market signals for Gold
The options market provides additional insights, suggesting it is bracing for significant moves ahead.
December 2026 Gold options show heavy activity in both puts and calls. Market data show significantly higher Call Open Interest (92K contracts) than Put Open Interest (44K contracts), yielding a Put-Call Open Interest ratio of roughly 0.50.
Put-Call ratios below 0.7 typically reflect bullish markets. While they can sometimes be viewed as contrarian indicators when an asset is overbought, the Gold chart is currently in a bearish correction, meaning option traders are actively identifying a buying opportunity here.
However, this heavy activity also tells us professional traders are preparing for a wide range of possible outcomes. Implied volatility remains above 23%, suggesting expectations of large price swings ahead as the market hedges against macro uncertainty.
Conclusion
Gold is sending two very different messages: fast money is reducing exposure, but central banks, the world's longest-term investors, continue to accumulate. This is why panic-selling every dip may be the wrong approach.
Instead, market participants should continue to monitor key indicators: central bank purchases, real interest rates, ETF flows, and options positioning. If ETF selling starts reversing while central bank buying remains strong, Gold's next major leg higher could arrive much faster than many expect.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
Author

Dhwani Mehta
FXStreet
Residing in Mumbai (India), Dhwani is a Senior Analyst and Manager of the Asian session at FXStreet. She has over 10 years of experience in analyzing and covering the global financial markets, with specialization in Forex and commodities markets.

















