GBP/USD Forecast: Sellers to retain control while 1.2750 stays intact as resistance
- GBP/USD extended its slide after breaking below 1.2800 on Thursday.
- 1.2750 aligns as immediate resistance for the pair.
- An improving risk mood ahead of the weekend could help the pair find a foothold.

GBP/USD lost its traction and continued to push lower as the technical selling pressure ramped up after it broke below 1.2800 on Thursday. The pair fluctuates in a tight range below 1.2750 early Friday and the technical picture suggests that the bearish bias stays intact.
Rising US Treasury bond yields provided a boost to the US Dollar (USD) on Thursday and caused GBP/USD to turn south.
After the US data showed that the Producer Price Index (PPI) rose 1.6% in February, at a much stronger pace than the 1% increase recorded in January, the benchmark 10-year US Treasury yield climbed to 4.3% as investors reassessed the timing of the Federal Reserve (Fed) policy pivot. According to the CME FedWatch Tool, the probability of the Fed policy rate staying unchanged at 5.25%-5.5% range in June climbed to 40% from below-30% before the data release.
Pound Sterling price this week
The table below shows the percentage change of Pound Sterling (GBP) against listed major currencies this week. Pound Sterling was the weakest against the US Dollar.
| USD | EUR | GBP | CAD | AUD | JPY | NZD | CHF | |
| USD | 0.50% | 0.87% | 0.43% | 0.97% | 1.32% | 1.38% | 0.69% | |
| EUR | -0.50% | 0.37% | -0.07% | 0.48% | 0.83% | 0.89% | 0.18% | |
| GBP | -0.88% | -0.37% | -0.44% | 0.11% | 0.47% | 0.53% | -0.18% | |
| CAD | -0.43% | 0.06% | 0.44% | 0.55% | 0.87% | 0.95% | 0.25% | |
| AUD | -0.98% | -0.48% | -0.11% | -0.55% | 0.36% | 0.41% | -0.28% | |
| JPY | -1.32% | -0.84% | -0.22% | -0.91% | -0.33% | 0.08% | -0.65% | |
| NZD | -1.39% | -0.90% | -0.53% | -0.97% | -0.41% | -0.06% | -0.71% | |
| CHF | -0.68% | -0.18% | 0.19% | -0.24% | 0.30% | 0.63% | 0.71% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Euro from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent EUR (base)/JPY (quote).
Later in the day, the Import Price Index data from the US will be watched closely by market participants. Although this data is not usually a big market-mover, investors could react to it due to its potential impact on inflation. In January, the Import Price Index declined by 1.3% on a yearly basis. A positive print in February could help the USD gather strength ahead of the weekend. On the other hand, a decline similar to the one in January could weigh on the currency and help GBP/USD rebound.
In the meantime, US stock index futures turned marginally positive on the day after staying in the red during the Asian trading hours. In case the risk mood continues to improve and Wall Street's main indexes open higher, the USD could struggle to find demand in the American session.
GBP/USD Technical Analysis
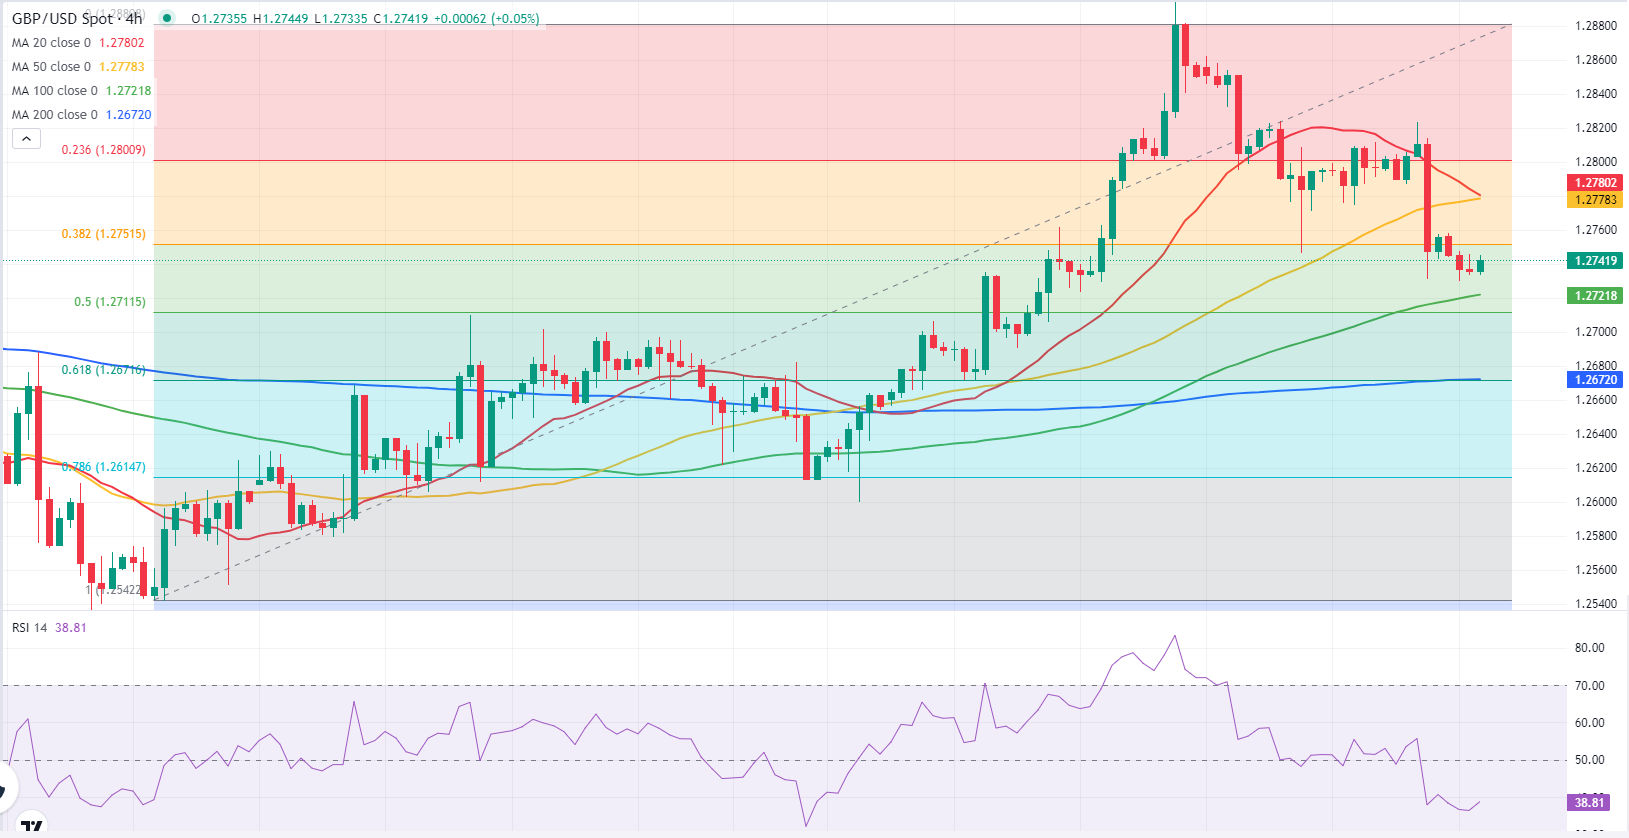
The Relative Strength Index (RSI) indicator on the 4-hour chart stays below 40 and the 20-period Simple Moving Average (SMA) is close to making a bearish cross with the 50-period SMA, reflecting the bearish bias.
The Fibonacci 38.2% retracement of the latest uptrend aligns as key resistance at 1.2750. If GBP/USD fails to reclaim this level, sellers could look to retain control. In this scenario, 1.2720-1.2710 (Fibonacci 50% retracement, 100-period SMA) could be seen as the next support area before 1.2670 (200-period SMA, Fibonacci 61.8% retracement).
In case GBP/USD manages to stabilize above 1.2750, 1.2780 (20-period SMA, 50-period SMA) and 1.2800 (Fibonacci 23.6% retracement) could be seen as next recovery targets.
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, aka ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Eren Sengezer
FXStreet
As an economist at heart, Eren Sengezer specializes in the assessment of the short-term and long-term impacts of macroeconomic data, central bank policies and political developments on financial assets.

















