EUR/USD Weekly Forecast: US Dollar persistent demand hints at a test of 1.1000
- The Middle East conflict remains the main driver of the market.
- United States Consumer Price Index taking center stage after FOMC Minutes.
- EUR/USD remains on the back foot, with speculative interest eyeing a test of 1.1000.
The EUR/USD pair maintained its bearish route, edging lower for a fifth consecutive week. The pair traded as low as 1.1161 before trimming some losses, settling on Friday at around 1.1210. Financial markets were once again all about US Dollar (USD) momentum and risk aversion, with government bond yields stealing the limelight while hitting multi-decade highs.
Risk aversion sets the tone
Demand for government bonds has multiple causes, although risk aversion generally adds the major weight. Investors are looking to hedge against uncertainty, the latter coming from the Middle East crisis and the resulting inflation and energy shocks. Governments also have to compete for funding with corporations, particularly seeking capital to expand the AI frenzy. How all these will end remains unclear, which adds to the risk-averse momentum dominating financial boards.
Middle East back and forth
The Persian Gulf crisis had some ups and downs in the last few days. United States (US) President Donald Trump stated mid-week that a deal with Iran is not something he wants to do, and market talks escalated over a potential attack on Iran. Concerns cooled a bit after President Trump noted he will not attack Iran before mid-term elections, scheduled for November 3.
And of course, that’s not enough for the American voter, who is continuously dealing with higher gas prices denting consumers’ sentiment. Public support for the war has declined, and Republicans risk losing control of Congress as the mood sours.
Meanwhile, crude Oil prices remain much higher than pre-war levels, with the barrel spiking above $100 after President Trump announced his unwillingness to reach a deal with Tehran. Americans are paying roughly 40% more to fill their tanks, despite supply from the Gulf being near pre-war levels. Around four out of ten barrels of crude now exit the region without going through the Strait of Hormuz, while traffic through the latter has improved significantly.
Then, what’s happening? Well, the simplest answer is higher transportation costs. Lingering disruption in the Middle East is forcing major exporters to take up costly means for delivering crude Oil. Such costs are passed on to consumers.
Hawkish Federal Reserve
Other than that, the US published the September ISM Services Purchasing Managers’ Index (PMI), which eased to 54.9 from the previous 55.4, also missing the expected 55. The report shows that inflationary pressures remain high, as the Prices Paid Index edged higher to 74 from 72.6 in August. The report, despite being mildly discouraging, did not affect the dominant USD strength.
Also, the Federal Open Market Committee (FOMC) published the Minutes of its September meeting. The document showed all voting members supported the 25-basis-points (bps) rate hike, while leaning hawkish, as most members judged that another hike would probably be appropriate by the end of the year. Officials remain concerned about elevated inflation, while seeming more confident about the labor market, considering it is close to full employment.
Europe stays afloat
The reasons beyond Euro weakness seem less clear. Still, political turmoil is part of the list. Protests spread in France and Spain amid housing, fiscal, and educational discomfort. The global surge in energy prices amid the Middle East conflict is also affecting the Old Continent alongside the migration situation.
The far right gains ground ahead of French elections next year, while Spanish Prime Minister Pedro Sanchez dissolved the Parliament and called for early elections. Also, German Chancellor Friedrich Merz faces record-low approval ratings, which also results in surging right-wing parties.
Political tensions steal the focus from the economy, which anyway is barely holding afloat. Despite the European Central Bank (ECB) early decision to tighten monetary policy, inflation holds well above the central bank’s 2% goal. Economic progress remains tepid, and while a recession is out of the picture, the situation is far from optimal. As a result, the EUR's attractiveness is pretty much null.
What’s next on the docket
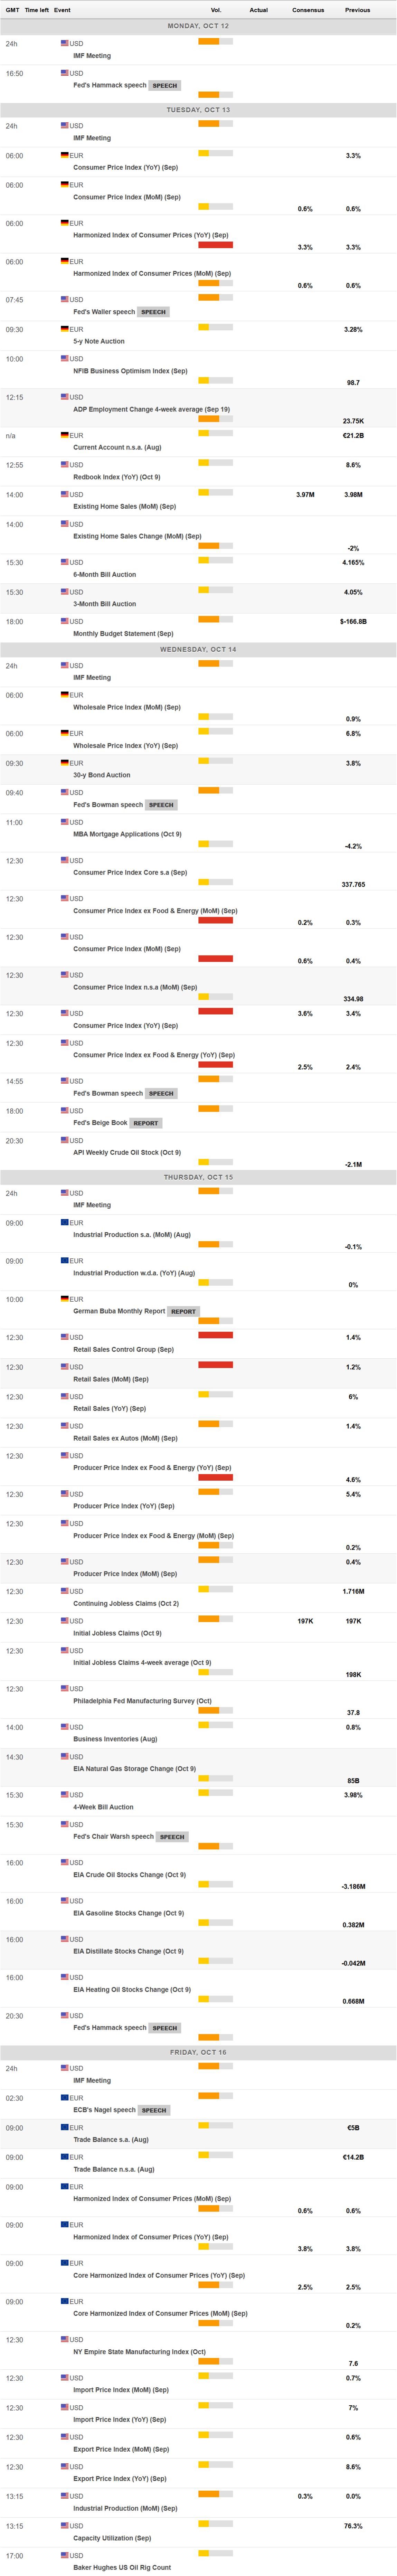
During the upcoming days, data-wise, the focus will be on inflation. Germany will release the final estimate of the September Harmonized Index of Consumer Prices (HICP) on Tuesday, while the US will publish Consumer Price Index (CPI) data for the same month on Wednesday. US September Retail Sales and Producer Price Index (PPI) figures will be out on Thursday, while the Eurozone HICP is scheduled for Friday.
Investors will also be keeping an eye on the upcoming US elections and how the odds move. And of course, Oil prices will continue to dictate the market’s sentiment.
EUR/USD Technical Outlook:
In the daily chart, EUR/USD extends its bearish phase as spot remains decisively below the 20-day, 100-day, and 200-day Simple Moving Averages (SMAs) clustered between 1.1361 and 1.1596. This alignment of short- and long-term SMAs above price suggests persistent downside pressure. The Momentum indicator stays negative although directionless, while the Relative Strength Index (RSI) indicator turns lower around 25 reflecting the prevalent downward trend rather than suggesting selling exhaustion.
Bigger time frames also support the bearish case. In the weekly chart, EUR/USD sits below the 100-week SMA at 1.1364 and the 20-week SMA at 1.1486, while holding only modestly above the 200-week SMA at 1.1099. The same chart shows the RSI indicator aiming lower at around 34, and Momentum gaining downward traction below its midline, reinforcing the idea of lower lows ahead.
On the topside, initial resistance emerges at the 20-day SMA near 1.1361, which converges with the 100-week SMA a couple of pips above it, making the area an interesting selling point should profit-taking push the pair higher. Further gains could see the pair reaching the 1.1470 region, a strong static area. On the downside, immediate support is aligned with the current market area around 1.1190, ahead of the more significant structural floor at the 200-week SMA near 1.1099; a weekly close below this latter level would open the door to a deeper bearish extension towards the 1.1000 psychological threshold.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Author

Valeria Bednarik
FXStreet
Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.
















