EUR/USD Weekly Forecast: Buyers cautious amid tepid EU progress, US political chaos
- Concerns about the United States economy deepen as the government shutdown extends.
- The Eurozone may be in a good place, but economic progress is yet to be seen.
- EUR/USD bounced from a fresh multi-week low, not yet out of the woods.
The EUR/USD pair ends the week with modest gains at around 1.1580 after falling to 1.1468, its lowest in over three months. The US Dollar (USD) maintained its positive tone throughout the first half of the week, but changed course on Thursday, although with modest downward strength. Price action was quite limited, with the pair confined to a roughly 100-pip range.
United States political stalemate taking its toll
The focus stayed on the United States (US) and the Greenback, with investors struggling to assess the Federal Reserve (Fed) hawkish shift, the government shutdown, and macroeconomic data.
Concerns about US economic progress grew as the federal shutdown extended, now officially the longest in the country’s history. And there are no signs the stalemate will end anytime soon: House Speaker Mike Johnson held a press conference on Thursday and noted that he is less optimistic about the shutdown ending, triggering a fresh wave of USD selling.
A consequence of the shutdown is the absence of US official data, which left market participants as clueless as Fed officials. The Federal Open Market Committee (FOMC) decided to trim the benchmark interest rate when it met late October, but quickly cooled down expectations for a similar move in December.
The little data published since October 1 showed a weakening labor market and stubborn inflation. The latest Consumer Price Index (CPI) report available showed that annual inflation rose to 3% in September from 2.9% in the previous month. The figure was better than the 3.1% anticipated by market participants, while still well above the Fed’s 2% goal.
Also, the country released this week the October Challenger Job Cuts report, which showed that US-based employers announced 153,074 job cuts in October, up from the 55,597 cuts announced in October 2024, and higher than the 54,064 job cuts announced in September. That adds to the temporary furloughs related to the shutdown. On positive news, the ADP Employment Change survey showed that the private sector added 42,000 new job positions in the same month, following a revised loss of 29,000 in the previous month.
Nevertheless, the extension of the stalemate is clearly taking its toll on the economy. Before the shutdown, the US economy was doing pretty well beyond the tepid employment-related figures, growing at a steady pace. That would likely change once the government finds its way to fresh funding.
And there are already some hints on that: the ISM Manufacturing Purchasing Managers’ Index eased to 48.7 in October from 49.1 in September, also missing the expected 49.5. The Services PMI in the same period, on the contrary, ticked higher to 52.4 from the 50 posted in September.
Finally, the preliminary estimate for the November Michigan Consumer Sentiment Index fell to 50.3 from the previous 53.6, reflecting households' nervousness and weighing on the USD ahead of the weekly close.
Modest European progress, optimistic ECB
European news maintained the upside capped for the EUR. The Eurozone released the September Producer Price Index (PPI), which contracted by 0.1% in the month, after falling 0.4% in August. The annual PPI fell by 0.2% as expected, and improved from the previous -0.6%. Also, Retail Sales in the Eurozone fell by 0.1% MoM in September, worse than the 0.2% advance anticipated. The August figure was downwardly revised to -0.1%, while the September annualized figure printed at 1%, below the 1.6% posted in the previous month.
More optimistic data came from the Hamburg Commercial Bank (HBOC), which published the final estimates of the European Services and Composite PMIs, upwardly revising most figures. German services output was confirmed at 54.6, while the Composite PMI was reported at 53.9. The final Eurozone Services PMI printed at 53, up from the previous estimate of 52.6, while the Composite PMI was reported at 52.5. Manufacturing output was confirmed at 50, as previously estimated.
Other than that, German Factory Orders were up 1.1% in September, improving from -0.4% in the previous month, although the annual reading printed at -4.3%, much worse than the previous 2.1% gain.
It is worth remembering that the European Central Bank (ECB) has trimmed interest rates multiple times throughout the year and has reached a good place, according to President Christine Lagarde. Officials will remain vigilant, but on the monetary policy front, the ECB has nothing more to do.
Data in the docket
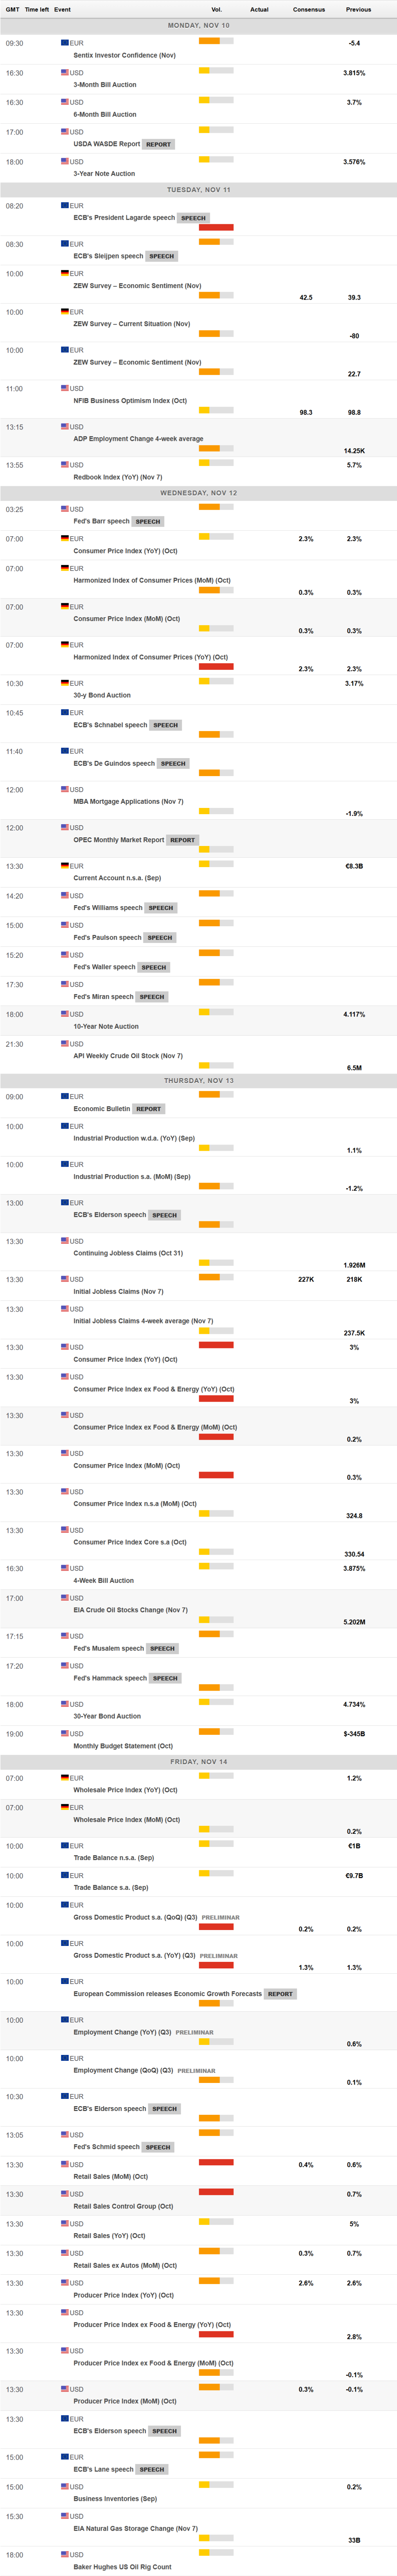
As long as the US government shutdown continues, there won’t be official releases. The country should publish in the upcoming days fresh CPI and Producer Price Index (PPI) figures, but it is highly unlikely. The same goes for official employment-related figures. Other than that, ADP will start releasing Employment Change figures on a weekly basis, with a 4-week average schedule for next Wednesday.
Across the pond, things will be a bit more interesting, as Germany will publish the November ZEW Survey on Economic Sentiment and the final estimate of the October Harmonized Index of Consumer Prices (HICP). The Eurozone will offer November Sentix Investor Confidence, September Industrial Production, and a preliminary estimate of the Q3 Gross Domestic Product (GDP).
EUR/USD technical outlook
The EUR/USD pair is not yet out of the woods, with the technical picture skewing the risk to the downside. According to the daily chart, the short-term tone is capped by a bearish 20-day Simple Moving Average (SMA) that stands at 1.1594, aims south, and sits below the 100-day SMA at 1.1166, suggesting sellers still hold the near-term grip. Meanwhile, the 200-day SMA continues to advance at 1.1342, underpinning the broader backdrop and offering dynamic support. At the same time, the Momentum indicator has firmed over recent sessions, indicating the bearish impulse is losing traction, while the Relative Strength Index (RSI) indicator also recovered but remains below the 50 threshold, consistent with a neutral-to-bearish bias.
In the weekly chart, a flat 20 SMA remains well above the current level, providing resistance at around 1.1678. The longer moving averages remain below the current level, with a bullish 100 SMA at 1.1070 and the 200 SMA rising to 1.0837. Finally, technical indicators paint a more cautious picture: the Momentum indicator has flattened around its midline, underscoring the absence of directional impetus and capping immediate follow-through. Meanwhile, the RSI ticked marginally higher above its midline, yet without hinting at follow-through. A weekly close back above the 20 SMA at 1.1678 would be needed to reassert upward momentum, while failure to reclaim it risks an extended consolidation phase above the 1.1017-1.0837 support area defined by the rising 100- and 200-week SMAs.
(This content was partially created with the help of an AI tool)
GDP FAQs
A country’s Gross Domestic Product (GDP) measures the rate of growth of its economy over a given period of time, usually a quarter. The most reliable figures are those that compare GDP to the previous quarter e.g Q2 of 2023 vs Q1 of 2023, or to the same period in the previous year, e.g Q2 of 2023 vs Q2 of 2022. Annualized quarterly GDP figures extrapolate the growth rate of the quarter as if it were constant for the rest of the year. These can be misleading, however, if temporary shocks impact growth in one quarter but are unlikely to last all year – such as happened in the first quarter of 2020 at the outbreak of the covid pandemic, when growth plummeted.
A higher GDP result is generally positive for a nation’s currency as it reflects a growing economy, which is more likely to produce goods and services that can be exported, as well as attracting higher foreign investment. By the same token, when GDP falls it is usually negative for the currency. When an economy grows people tend to spend more, which leads to inflation. The country’s central bank then has to put up interest rates to combat the inflation with the side effect of attracting more capital inflows from global investors, thus helping the local currency appreciate.
When an economy grows and GDP is rising, people tend to spend more which leads to inflation. The country’s central bank then has to put up interest rates to combat the inflation. Higher interest rates are negative for Gold because they increase the opportunity-cost of holding Gold versus placing the money in a cash deposit account. Therefore, a higher GDP growth rate is usually a bearish factor for Gold price.
Author

Valeria Bednarik
FXStreet
Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.

















