Dollar Catches a Bid, But Can the Gains Last?

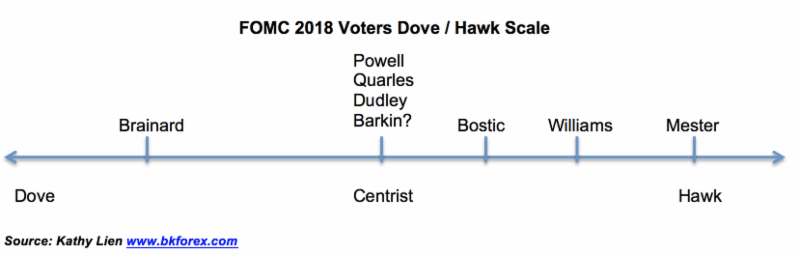
The U.S. dollar finally caught a bid today as it rose against most of the major currencies. Treasury yields, which started the day in negative territory turned positive by the end of the NY session and the move coincided with USD/JPY's rise back above 113. No U.S. economic reports were released today and by all counts, the beginning of the week rally is modest but after 3 weeks of declines, the greenback is itching for a recovery. The front of the week will be dominated by Fed speak and it won't be until the end of the week that data comes into focus with the release of U.S. retail sales and consumer prices. Atlanta Fed President Bostic spoke today and as a 2018 FOMC voter, his views now carry increased significance. He's typically one of the more hawkish members of the central bank so it is slightly out of character for him to say that the Fed may not need as many as 3 or 4 rate hikes per year. His base case is for 2 to 3 hikes in 2018. While he sees tax cuts providing a modest boost and upside risk to growth, he did not feel that 2018 would be a breakout year and he worries that the Fed could miss their inflation goals. In calling for slow tightening, Bostic is aligning with the doves. San Francisco Fed President Williams who is also a 2018 FOMC voter only said low rates are a problem in most advanced economies and the Fed's goal is to return inflation to 2% over the next few years. Later this week, we'll hear from Rosengren, Kashkari, Evans, Kaplan, Dudley, Harker and Rosengren. Of these policymakers, Dudley is the only voter and plans to retire mid 2018. The makeup of the FOMC changes significantly this year with the 2 most dovish FOMC members (Kashkari and Evans) rotating out and replaced by hawks. There are also 4 vacancies in addition to Dudley's replacement. Here's an updated dove - hawk scale that goes in effect after Yellen steps down this month. Barkin will be Lacker's replacement but with zero monetary policy experience, it is not clear where he stands on policy. The same is true of Quarles who has only voted with the majority. As for whether the dollar's gains can last, we are bullish dollars this year and see near term strength against the euro and commodity currencies but do not rule out another slide before the greenback finally bottoms.
The worst performing currency today was the euro, which dropped well below 1.20.The single currency had been under pressure throughout the NY trading session and ended the day near its lows. This suggests that we could see a deeper slide down to 1.19. The sell-off was driven by the recovery in the U.S. dollar and the slide in German yields. Data was mixed with the decline in German factory orders offset by a pick in Eurozone retail sales and confidence. These reports tell us that while the recent improvements in the economy have boosted confidence, the momentum is beginning to slow as the gains in the euro pose a risk to growth. Looking ahead, we anticipate additional near term losses for the euro and the scope of the move will hinge on tomorrow's German industrial production and trade balance reports. Economists are looking for stronger numbers all around given the improvement in the manufacturing PMI index but the drop in factory orders raises the risk of a downside surprise.
In contrast to the euro, sterling rebounded against the U.S. dollar during the North American trading session shrugging off a decline in house prices. Although U.K. yields fell today, they rebounded off their lows, helping sterling recover earlier losses. We believe that GBP will trade higher this year but worry about near term political risks. Prime Minister May is in the process of reshuffling her cabinet and rather than reaffirm her authority, has cast doubt on it as she left many of her top ministers in place. Calls for the removal of Boris Johnson and Phillip Hammond were ignored and she lost one of her key allies James Brokenshire who resigned for health reasons. Her attempt at a fresh start on domestic issues has been stymied by the lack of material changes, leaving her political future in doubt and Brexit in central focus. Technically, EUR/GBP appears poised for further losses but the outlook for GBP/USD is less clear.
Meanwhile there was very little consistency in the performance of the commodity currencies today. AUD/USD fell for the first time in 15 trading days, USD/CAD stabilized after last week's losses while the New Zealand dollar extended its gains.The Australian dollar fell victim to weaker data as construction activity slowed materially in December. We've seen manufacturing and construction activity ease into year end while service sector activity advanced ever so slightly. These reports show economic activity waning and if this week's retail sales report also falls short of expectations, we could see a more material correction in the currency. No economic data was released from New Zealand but the currency continues to power higher on momentum alone. While there's resistance at 72 cents, the more significant barrier is closer to 74 cents. The Canadian dollar stabilized but further losses are likely following the Bank of Canada's positive winter business outlook survey. The BoC saw a healthy sales outlook, stronger capacity and labor pressures, broad based plans by firms to boost investment and widespread plans to increase hiring. They also felt that production capacity pressure is the highest since the recession. These positive views along with last week's hot employment report has the market pricing in an 86% chance of a Bank of Canada rate hike next week, up from 70% on Friday. These expectations should fuel further gains in the Canadian dollar and take USD/CAD down to at least 1.23.
Author

Kathy Lien
BKTraders and Prop Traders Edge
Having graduated New York University’s Stern School of Business at the age of 18, Ms. Kathy Lien has more than 13 years of experience in the financial markets with a specific focus on currencies.

















