Auto & Student Loan Bubbles

The markets have reversed some the recent trends where the Trump trade was unwinding. This could mean there will be a pause or a continuation of the Trump trade into the spring. The S&P 500 is up less than 1% from the lows of the mini-correction. There are many dip-buyers who are praying for a 5% correction to put their money to work. The dip-buyers have usually preempted 5% corrections, thus preventing any from occurring. I think if stocks fell more than 5%, the initial dip-buyers would vanish as that group is merely a bunch of speculators who ignore the fundamentals of the economy and valuations. The dollar index also rebounded from the downturn it has been in as it returned to above par (100).
I have repeated many times that pension funds have taken more risk because bond yields are so low. Putting numbers behind this explanation, in 1952 96% of pension funds’ assets were in cash and bonds. Now only 27% of their assets are in cash and bonds. They have spurred a remarkable run in stocks by taking more risk, but now there’s not much more risk they can take. The problem for pension funds specifically is that even though they can’t take much more risk, they need much better returns. Underfunded pension obligations rose from $292 billion in 2007 to $1.9 trillion now. It could be good news for stocks that pension funds may be taking more risk in the future, but it spells a disaster for the funds themselves when stocks fall back down to earth. A stock market crash could crash the pension fund system which may end up being bailed out.
Besides the pension fund chaos which will occur in the next few years, the two biggest bubbles in the economy today are the student loan bubble and the auto loan bubble. The total household debt is now above the late-2008 record high as it has reached over $12.5 trillion. This is why I don’t take consumer sentiment surveys seriously. It takes a bipolar group of people to claim they are the most confident in years while having the most debt ever. An uptick in unemployment will cause consumer sentiment to crash as consumers can’t afford to service their enormous pile of debt.
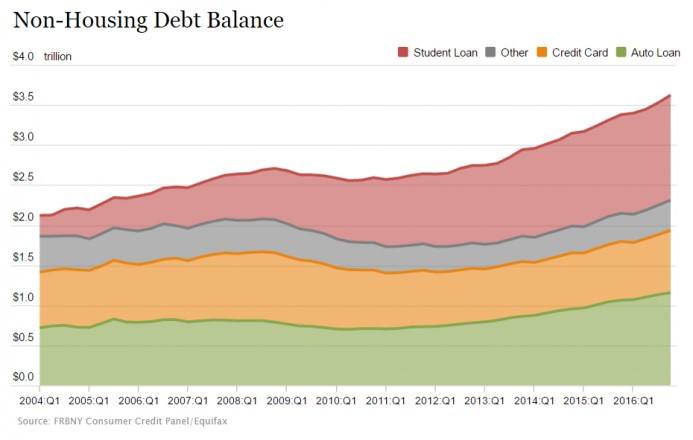
The record debt isn’t fueled by housing like the last cycle. Housing debt has barely increased from the cycle low in 2013 and its down about $1 trillion from the $10 trillion peak in 2008. The driver of this cycle’s debt bubble is non-housing debt as you can see below. Student loans and auto loan debt increases are the drivers of record debt. The student loan bubble has been a long time in the making as government guaranteed loans boosted the demand for the product. Colleges have responded to this increase in demand by increasing the majors they offer. When I was looking at NYU a few years ago, I remember them telling us a student was majoring in “evil.” I’m not sure what job he/she will be getting with that degree. It shows the insanity which has prevailed.
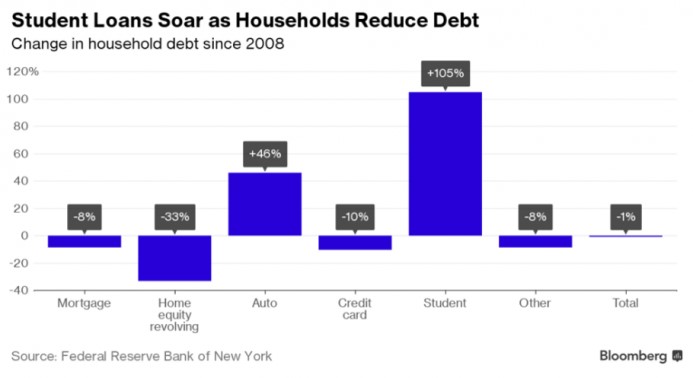
The only thing crazier than majoring in “evil” is the price increases colleges have implemented. For some, considering the costs and benefits of going to college, it no longer makes sense to do so. A rise in interest rates would send many graduated students into bankruptcy. It’s not a loan you can default on which is going to complicate the matter when the bubble bursts. After the bubble bursts, either colleges will lower their tuitions or alternative online education courses will become more heavily relied upon. Spending two years taking classes which have nothing to do with your major doesn’t seem bad when you’re having a good time in college, but a $20,000 bill isn’t worth it. The chart below shows the 105% explosion in student debt since 2008. I can almost guarantee that, that debt increase speed will not continue for the next nine years.
I think of the auto loan bubble like a mini housing bubble. The damage to the economy won’t be as large because when customers buy a new car they expect it lose value after it leaves the lot. This compares to the expected increase in prices in real estate. The real trouble came about when people would borrow against their home equity. A similar situation to these home equity loans which flopped when the loan became larger than the value of the house is when vehicle trade-ins become larger than the value of the car. In the first nine months of 2016, 32 percent of U.S. vehicle trade-ins carried outstanding loans larger than the worth of the car which was a record high.
Like the housing market, the auto market has a large jobs producing industry behind it. The reason Chrysler and GM were bailed out was because of the number of workers they employ. If they were bailed out in the last crisis, one can only imagine how bad it will be when they are at the epicenter of the bubble burst.
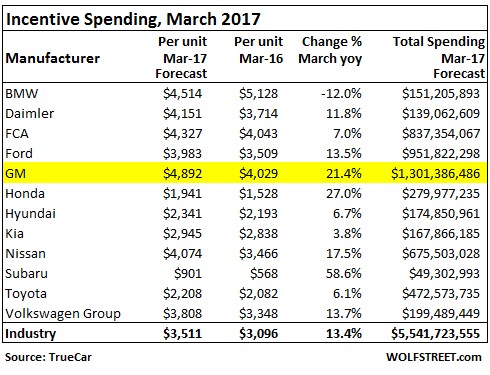
The two ways to tell the auto loan bubble is about to burst is the size of the incentives given to new car buyers and the loan delinquencies. The chart below shows the March 2017 forecasted incentive spending. With the 13.2% increase in incentives, TrueCar is expecting only a 1% increase in retail deliveries of cars and light trucks. Even though incentives are up 13.4% from last year, they’re down 2.1% from February which may signal the end of the incentive spending increases.
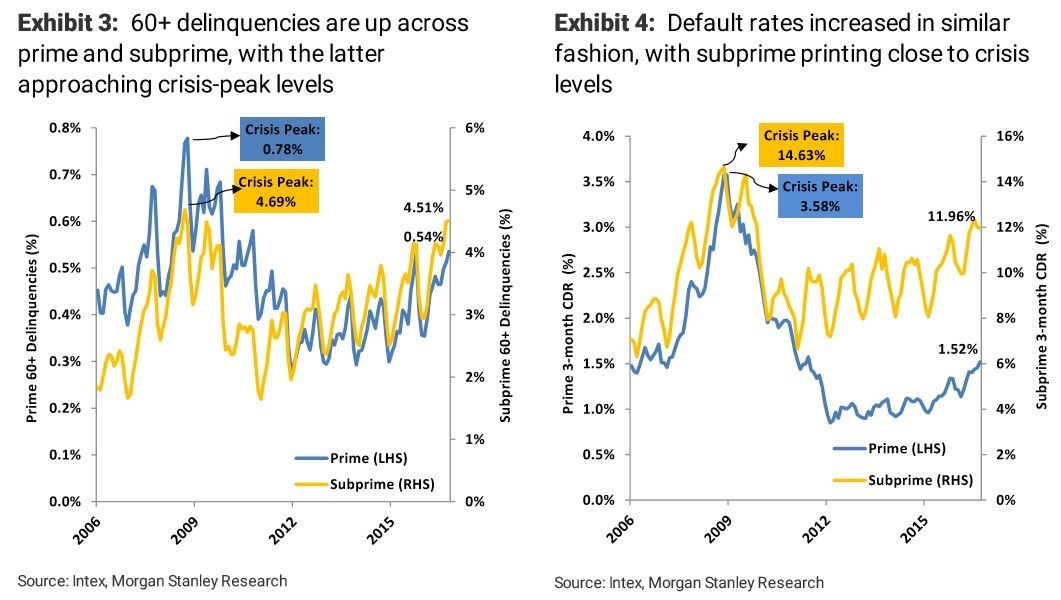
The auto loan bust is almost here according to the chart of 60+ day delinquencies. At the crisis peak of late-2008 the subprime delinquency rate was 4.69% and now it’s 4.51%. It shows how weak the economy is even though the labor market is supposedly as strong as it can get. The subprime default rate is also near its late-2008 peak as it was 14.63% then and it’s 11.96% now. It’s surprising to see such an increase in default rates without a sharp slowdown in demand. That sharp slowdown will be here shortly.
Don Kaufman: Trade small and Live to trade another day at Theotrade.
Don Kaufman: Trade small and Live to trade another day at Theotrade.
Author

TheoTrade Analysis Team
TheoTrade, LLC
Don Kaufman, Co-Founder, Chief Derivatives Instructor (Trader Stocks, Options, Futures) Don is one of the industry's leading financial strategists and educational authorities.

















