Australian Dollar Price Forecast: 0.7000 will be a tough one
- AUD/USD fades the recent bounce and recedes to the low 0.6900s.
- The US Dollar resumes its uptrend to hit new two-day peaks.
- The Consumer Inflation Expectations will be the salient event on Thursday.
The Australian Dollar (AUD) has come under renewed selling interest on Wednesday, motivating AUD/USD to set aside three daily upticks in a row and refocus on the downside and another potential challenge to the 0.6900 contention zone.
The resumption of the downside impulse in the pair comes in tandem with a marked advance in the US Dollar (USD) vs. its global peers, always amid steady risk aversion sentiment and further concerns over the fiscal scenario in France. In addition, tensions in the Middle East remain far from abated, which also collaborates with the upside bias in the Greenback.
Back to spot, it is worth mentioning that, following the September tops near 0.7250, AUD/USD has given away more than 3 cents when it flirted with the 0.6900 contention zone at some point during last week.
In the meantime, the pair remains vulnerable to further losses as long as it continues to trade below its 200-day SMA. However, the Reserve Bank of Australia’s (RBA) hawkish policy bias, combined with still elevated inflation at home, should cushion against any deep and sustained corrections for now.
Australia’s resilience meets signs of slowing momentum
Australia’s economy continues to compare favourably with many of its G10 peers, supported by domestic demand and positive economic growth. Persistent inflation also supports the RBA’s cautious, data-dependent policy stance.
However, business activity seems to have lost some momentum after final data showed the Purchasing Managers’ Index (PMI) for Manufacturing cooling to 49.6 in September and easing to 51.9 when it comes to Services, from 52.0 and 53.2, respectively.
Trade data provided another positive, albeit humble, signal after August’s trade surplus came in at just A$0.495 billion, adding to the A$1.351 billion surplus registered in the previous month (revised from A$1.923 billion).
Growth figures were less encouraging, however. Indeed, the Gross Domestic Product (GDP) expanded by 0.4% QoQ in the second quarter of 2026, up from 0.3%, while annual growth came in at 2.1%, down from the previous 2.5% yearly expansion.
The labour market also showed mixed signs in August, with the Unemployment Rate rising to 4.6% and Employment Change increasing by 39.5K, reversing July’s nearly 16K drop.
Inflation seems to have lost some impulse after the most-watched Trimmed Mean came in at 3.6% over the last twelve months, despite the headline CPI ticking higher to 4.0% from a year earlier.
The Melbourne Institute’s Consumer Inflation Expectations measure reinforced those figures after holding steady at 4.9% in September.
The figures leave the RBA’s inflation task incomplete. Policymakers expect inflation to return to target only in early 2028, keeping the emphasis on patience rather than an imminent policy pivot.
China offers stability, but little fuel for the Aussie
China is providing stability for the Australian economy, but not the growth impulse that has supported the Australian Dollar during previous expansions.
The Chinese economy grew by 4.3% YoY in the April-June period, while Industrial Production growth regained traction, expanding by 5.2% YTD, and the trade surplus widened to $119.1 billion in July, supported by decent increases in both imports and exports. However, on the downside, consumer spending remained sluggish after Retail Sales rose by only 0.4 % from a year earlier.
In addition, business surveys presented a promising picture: the National Bureau of Statistics reported that the Manufacturing PMI improved to 50.1 in September (from 49.8), while the Services PMI improved to 50.2 (from 49.0). In the same direction, private measures like RatingDog remained in expansionary territory, with Manufacturing at 52.1 (from 51.5) and Services at 51.6 (from 51.4).
Disinflationary pressures seem to have taken a breather in August, with the CPI gaining 0.8% YoY, up from 0.5%, while prices rose by 0.4% on a monthly basis. Producer Prices rose by 3.8% over the previous twelve months, down from the 3.5% increase recorded in the previous month.
The People’s Bank of China (PBoC) left its Loan Prime Rates unchanged early on Monday, maintaining the one-year rate at 3.00% and the five-year rate at 3.50%.
China is therefore neither providing a major boost nor creating a significant drag. Unless the data reveal a clearer acceleration or deterioration, its influence on AUD/USD is likely to remain limited.
The RBA hikes again as inflation refuses to cooperate
In a unanimous decision, the RBA hiked its OCR by 25 basis points to 4.60% at its meeting on Tuesday.
The statement said the Middle East conflict had pushed global energy prices well above the assumptions in its August forecasts, while inflation had proved stronger than expected, and short-term inflation expectations remained elevated. Although policy has been tightening since the start of the year, which had slowed the economy, the Board judged that further restraint was needed to return inflation to its target within a reasonable timeframe.
At her press conference, Governor Michele Bullock said domestic capacity pressures remained the main driver of inflation and warned that a prolonged Middle East conflict could lead businesses to pass higher costs on to consumers. While financial conditions were already restrictive, the Board concluded that another rate increase was warranted, stressing that policy would continue to tighten in a measured way.
Bullock added that policymakers would need to see quarterly core inflation slow to around 0.6% before they could gain greater confidence that inflation was moving back towards its goal.
Conclusion
The RBA delivered a hawkish hike, reflecting a deterioration in the inflation outlook driven by persistent domestic price pressures, elevated inflation expectations and higher energy costs. While further tightening remains possible, future decisions will continue to depend on incoming inflation data.
AUD/USD recovery runs into the 200-day SMA
Baseline outlook
The medium-term outlook has deteriorated in the last few weeks, as the pair remains unable to regain upside traction in a sustained manner. While below the 200-day SMA (0.7030), the pair should face an increasing chance of further losses. Against this backdrop, the continuation of the current sell-off could extend toward the June floor near 0.6860 (June 30).
Of note, the daily Relative Strength Index (RSI) has bounced off the oversold zone, although it remains close to it.
The resumption of the bullish bias will likely require a strong catalyst, namely a sustained improvement in risk appetite trends or renewed and persistent US Dollar weakness.
Upside scenario
A stronger risk-on environment should face the initial barrier at the 200-day SMA, prior to the weekly top at 0.7140 (September 21). North from here, a test of the 2026 high near 0.7280 should come into view.
Downside scenario
An additional deterioration in global risk sentiment, persistent strength in the Greenback, or renewed weakness in Chinese data could further fuel the ongoing selling mood.
Initial support is at the September floor of 0.6947 (September 30). A breach below the latter would increase the likelihood of a retest of the weekly low at 0.6922 (July 29) ahead of the June base.
Options and CFTC positioning keep the pressure on the Aussie
Options and positioning continue to reinforce a bearish AUD backdrop, although the latest data suggest that demand for immediate downside protection has begun to stabilise. AUD/USD one-month 25-delta risk reversals stood at −0.995 on October 6, leaving puts at a volatility premium over equivalent calls. The skew improved slightly over the latest week, with the RR rising 0.035 vol points, but the broader repricing remains decisively negative: the one-month change of −0.536 vol points ranks in just the 10.9th percentile of comparable moves over the past five years.
That repricing has also been stronger than the decline in spot would normally imply. Spot has fallen markedly over the past month, while its historical relationship would have suggested a risk reversal deterioration of around −0.305 vol points. The actual −0.536 move leaves a −0.231 vol-point negative excess, indicating that options traders remain more defensive toward the Australian Dollar than the spot move alone would justify.
Commodity Futures Trading Commission (CFTC) positioning reinforces that signal. Speculators increased net AUD shorts in the week to September 29, prompting a significant drop in the 4-week change. Importantly, despite that aggressive bearish flow, positioning remains far from historically crowded, while open interest sits in the 97.7th percentile of its five-year distribution. That combination points to fresh bearish participation rather than an exhausted short trade.
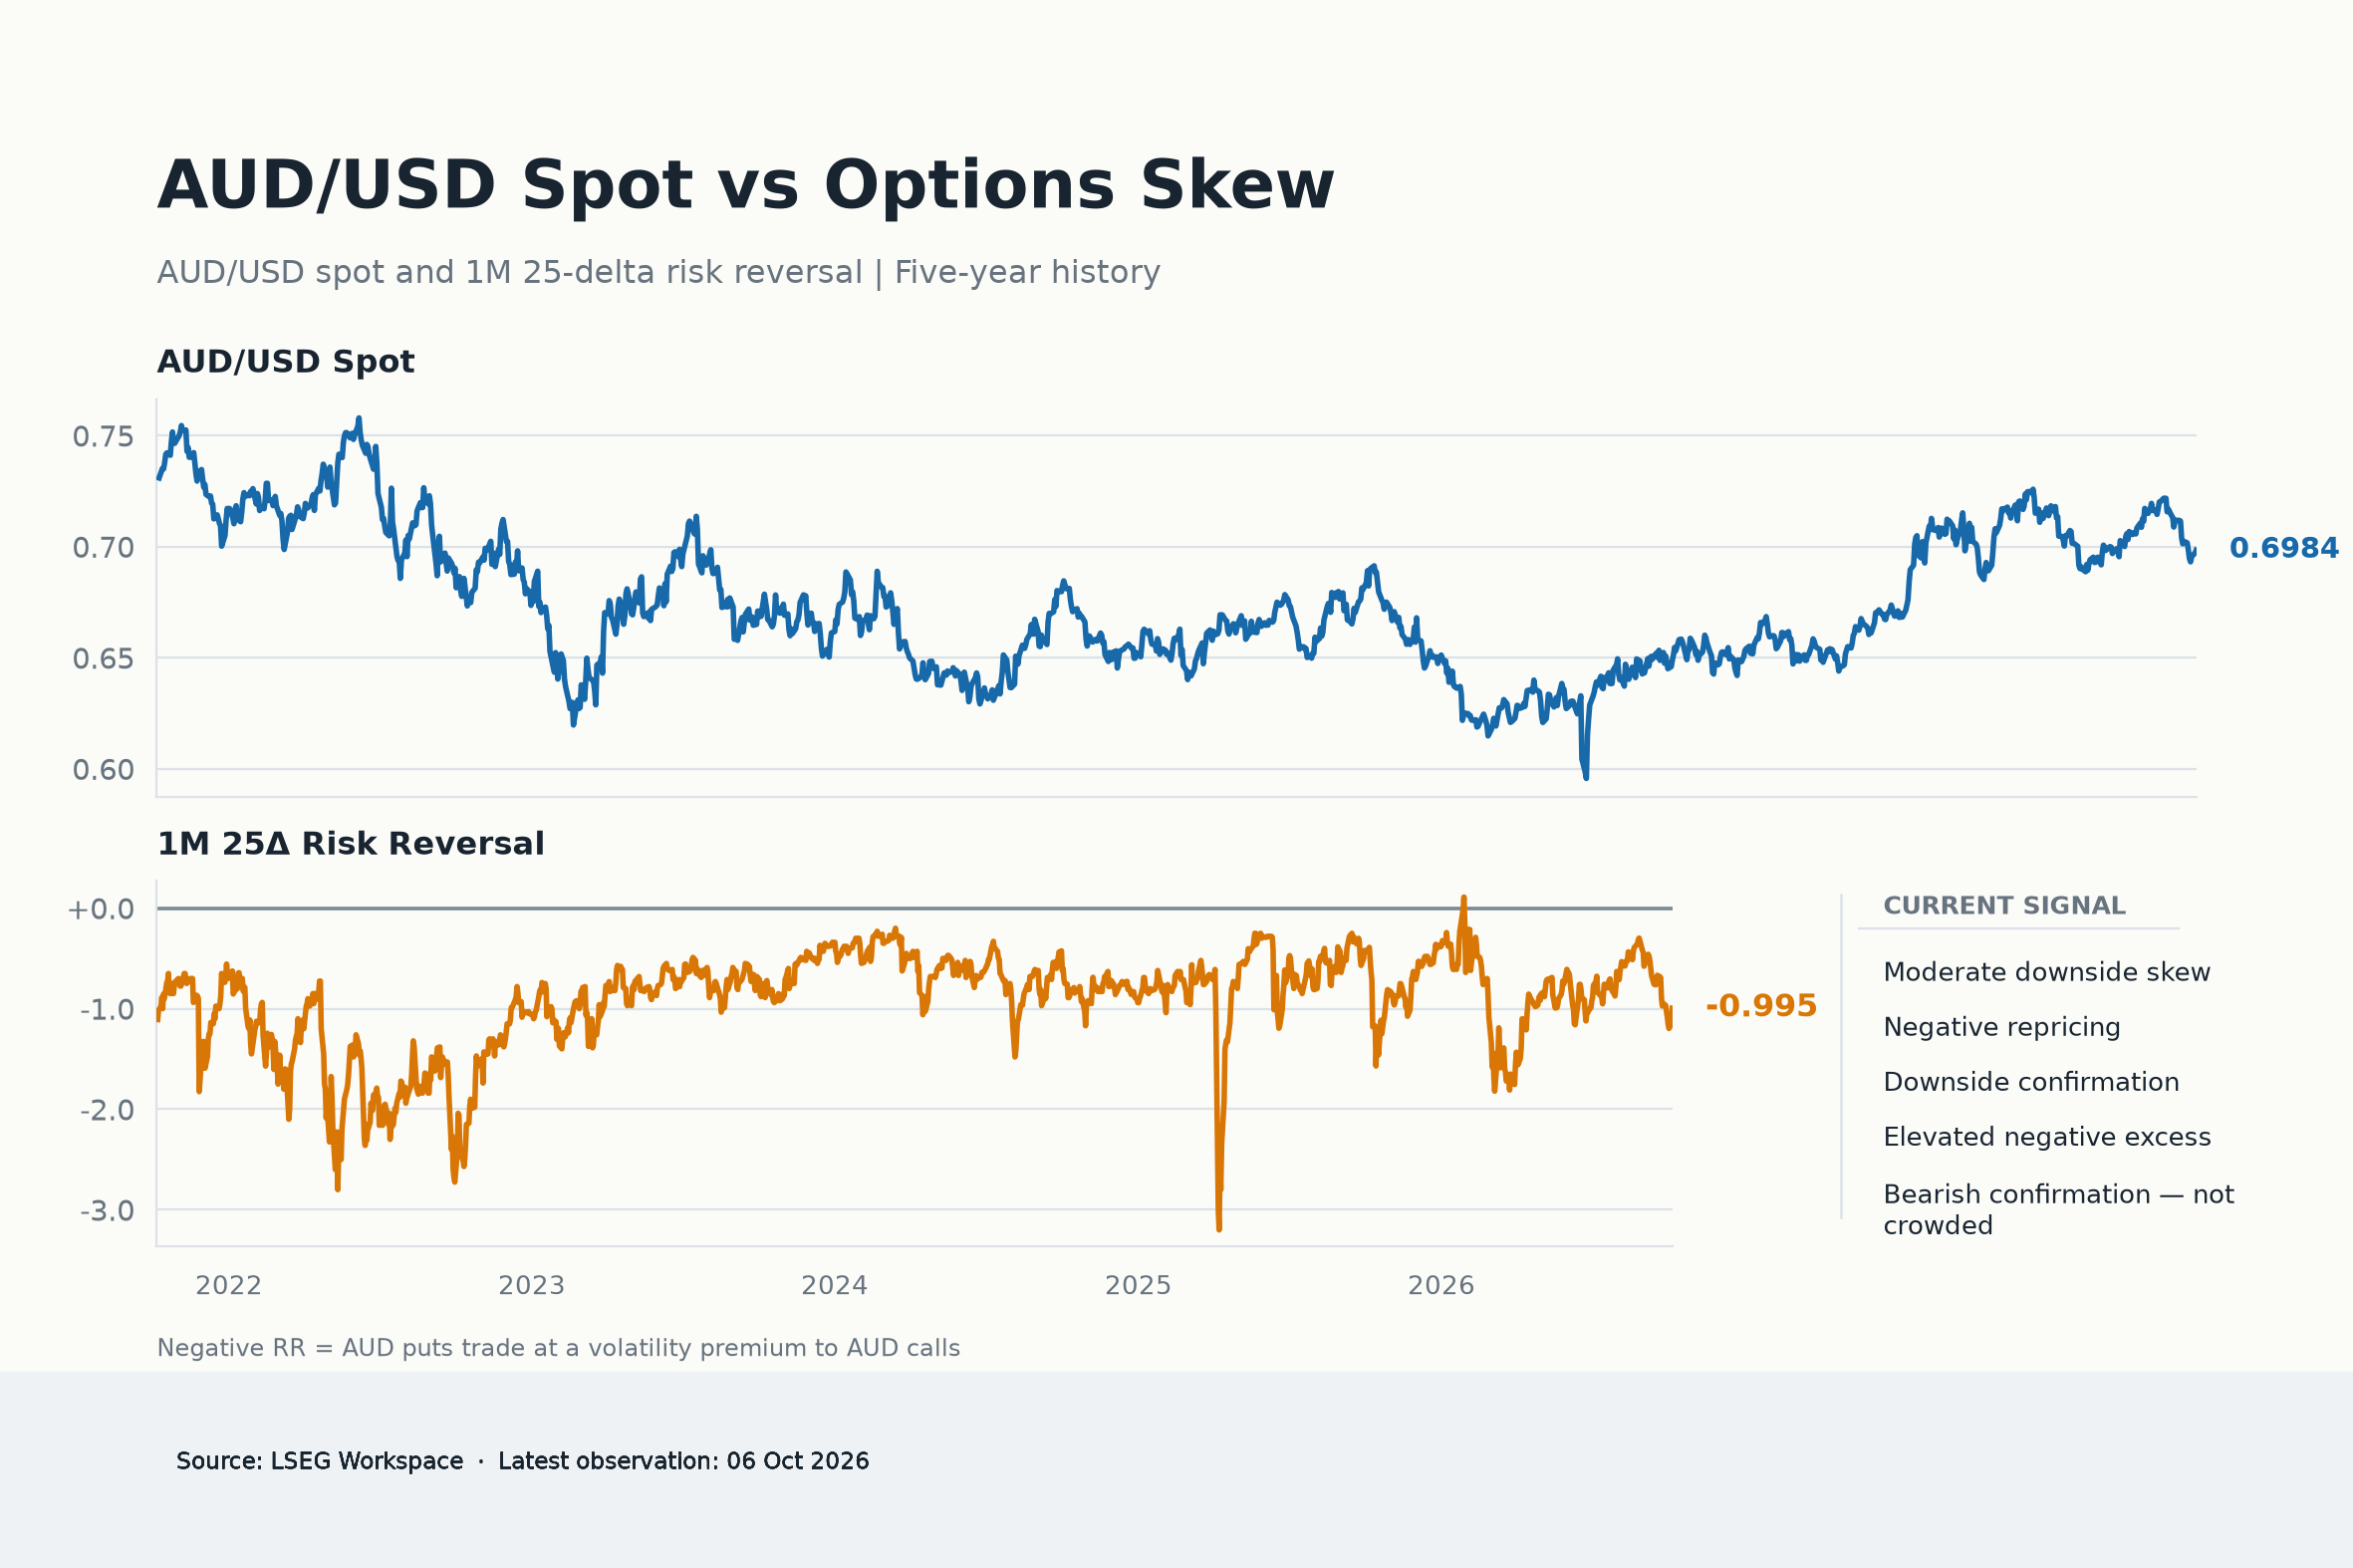
Overall, the cross-market signal remains bearish confirmation, not crowded. The recent stabilisation in risk reversals argues against describing downside hedging as accelerating right now, but options and futures positioning continue to suggest that investors remain wary of further AUD weakness, with room for bearish positioning to extend before crowding itself becomes a major constraint.
What’s next for AUD/USD?
US Dollar dynamics, global risk sentiment, and geopolitical developments remain the main near-term drivers of AUD/USD.
In the meantime, the next data release note on the domestic calendar will be the publication of the Consumer Inflation Expectations tracked by the Melbourne Institute.
Beyond the immediate releases, the main risks include a sharper slowdown in China, a persistently cautious Fed, a deterioration in investor risk appetite or a change in the RBA’s current policy stance. Any of these developments could quickly alter the outlook for the Australian Dollar.
Technical analysis
In the daily chart, AUD/USD trades at 0.6963, keeping a bearish near-term tone as spot holds beneath the 200-day simple moving average (SMA) at 0.7035 and other key trend filters, including the 100-day SMA at 0.7053 and the 55-day SMA at 0.7080. Price sits just above the 78.6% Fibonacci retracement at 0.6945, suggesting a fragile attempt to stabilize near this support, while the Relative Strength Index (14) at 35.1 hovers close to oversold territory and the Average Directional Index at 40.2 hints at a relatively strong ongoing downtrend.
On the downside, immediate support is aligned at the 78.6% retracement at 0.6945, ahead of the horizontal levels at 0.6901 and the 0.6865 area, which is reinforced by both a Fibonacci cycle anchor and a marked historical floor, with deeper cushions seen at 0.6833 and then 0.6660. On the topside, initial resistance emerges at the 61.8% Fibonacci retracement at 0.7008, followed by the 200-day SMA at 0.7035 and the 50% retracement at 0.7052 alongside the 100-day SMA at 0.7053, while a denser barrier is located around 0.7079–0.7096, preceding higher caps at 0.7150 and the 0.7238/0.7278/0.7283 cluster.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Domestic support, external pressure: AUD caught in the middle
Some dark clouds continue to hover around the AUD’s near-term outlook.
Australia’s domestic backdrop compares favourably with that of many advanced economies, and the RBA is in no hurry to abandon its hawkish stance. These factors should somewhat contain the bearish impulse.
The recovery nevertheless remains vulnerable to renewed strength in the Greenback, persistent geopolitical uncertainty and a Chinese economy that is stabilising rather than accelerating.
The 200-day SMA remains the key level for the medium-term outlook. Holding above it preserves the constructive structure, but a convincing break above 0.7200 is necessary to further extend the bull run.
However, such a move would require the resumption of the downward trend in the Greenback, stronger demand for risk-sensitive assets, additional cooling in US inflation, or a (less likely) dovish shift from the Fed.
Until then, external forces are likely to exert more influence over the Australian Dollar than domestic fundamentals.
Australian Dollar FAQs
One of the most significant factors for the Australian Dollar (AUD) is the level of interest rates set by the Reserve Bank of Australia (RBA). Because Australia is a resource-rich country another key driver is the price of its biggest export, Iron Ore. The health of the Chinese economy, its largest trading partner, is a factor, as well as inflation in Australia, its growth rate and Trade Balance. Market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – is also a factor, with risk-on positive for AUD.
The Reserve Bank of Australia (RBA) influences the Australian Dollar (AUD) by setting the level of interest rates that Australian banks can lend to each other. This influences the level of interest rates in the economy as a whole. The main goal of the RBA is to maintain a stable inflation rate of 2-3% by adjusting interest rates up or down. Relatively high interest rates compared to other major central banks support the AUD, and the opposite for relatively low. The RBA can also use quantitative easing and tightening to influence credit conditions, with the former AUD-negative and the latter AUD-positive.
China is Australia’s largest trading partner so the health of the Chinese economy is a major influence on the value of the Australian Dollar (AUD). When the Chinese economy is doing well it purchases more raw materials, goods and services from Australia, lifting demand for the AUD, and pushing up its value. The opposite is the case when the Chinese economy is not growing as fast as expected. Positive or negative surprises in Chinese growth data, therefore, often have a direct impact on the Australian Dollar and its pairs.
Iron Ore is Australia’s largest export, accounting for $118 billion a year according to data from 2021, with China as its primary destination. The price of Iron Ore, therefore, can be a driver of the Australian Dollar. Generally, if the price of Iron Ore rises, AUD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Iron Ore falls. Higher Iron Ore prices also tend to result in a greater likelihood of a positive Trade Balance for Australia, which is also positive of the AUD.
The Trade Balance, which is the difference between what a country earns from its exports versus what it pays for its imports, is another factor that can influence the value of the Australian Dollar. If Australia produces highly sought after exports, then its currency will gain in value purely from the surplus demand created from foreign buyers seeking to purchase its exports versus what it spends to purchase imports. Therefore, a positive net Trade Balance strengthens the AUD, with the opposite effect if the Trade Balance is negative.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.

















