NZD/USD Price Forecast: Resistance at 0.5805 is likely to hold bulls
- The New Zealand Dollar pulls back from highs near 0.5800 against the USD, but remains above 0.5750
- The US Dollar trims some losses as risk appetite eases ahead of the Fed meeting.
- NZD/USD faces significant resistance in the 0.5800 area.
The New Zealand Dollar’s recovery against the US Dollar stalled just below 0.5800 on Wednesday. The pair maintains a near-term positive trend intact so far, but the resistance area in the vicinity of 0.5800 is likely to pose a significant challenge for bulls.
The positive market mood seen in previous days is turning to caution as the US Federal Reserve’s monetary policy decision approaches. Furthermore, comments from the Chinese Foreign Minister urging the US to take actions to keep supply chains stable have failed to support investors' appetite for risk.
Technical Analysis: Bulls need to break 0.5805 and 0.5850 resistances
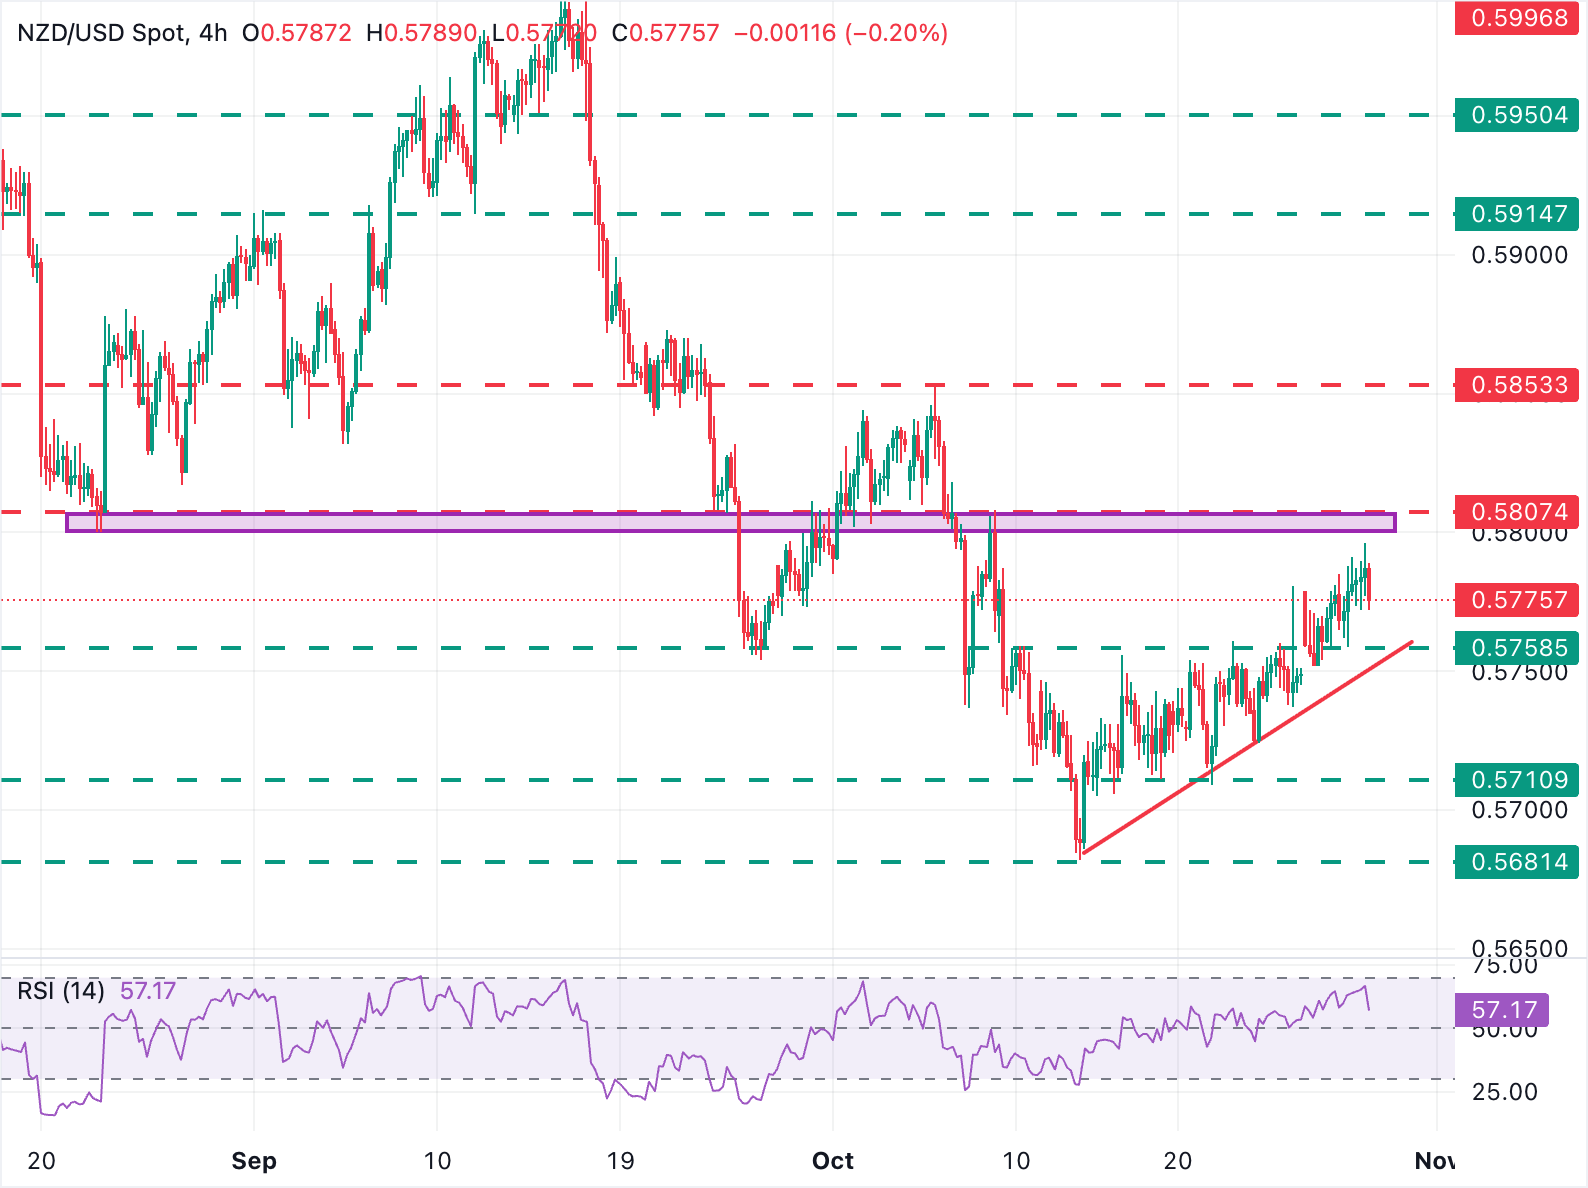
The technical picture shows the pair in a positive trend from mid-October lows at 0.5680, though the reversal from 0.5795 on the 4-hour chart suggests significant resistance in a former support area.
Looking from a wider perspective, the pair should break resistance at the mentioned 0.5800 area (October 9 high) and the October 6 high, at 0.5850 to break the bearish structure of lower highs and lower lows from mid-September highs, and aim for the area of 0.5915 (September 11 low).
To the downside, immediate support is at Tuesday’s low of 0.5760, and the trendline support from October 14 lows, now at 0-5750. A confirmation below here would increase pressure towards the October 17 and 21 lows, at the 0.5710 area.
Fed FAQs
Monetary policy in the US is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability and foster full employment. Its primary tool to achieve these goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, it raises interest rates, increasing borrowing costs throughout the economy. This results in a stronger US Dollar (USD) as it makes the US a more attractive place for international investors to park their money. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates to encourage borrowing, which weighs on the Greenback.
The Federal Reserve (Fed) holds eight policy meetings a year, where the Federal Open Market Committee (FOMC) assesses economic conditions and makes monetary policy decisions. The FOMC is attended by twelve Fed officials – the seven members of the Board of Governors, the president of the Federal Reserve Bank of New York, and four of the remaining eleven regional Reserve Bank presidents, who serve one-year terms on a rotating basis.
In extreme situations, the Federal Reserve may resort to a policy named Quantitative Easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used during crises or when inflation is extremely low. It was the Fed’s weapon of choice during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy high grade bonds from financial institutions. QE usually weakens the US Dollar.
Quantitative tightening (QT) is the reverse process of QE, whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing, to purchase new bonds. It is usually positive for the value of the US Dollar.
Author

Guillermo Alcala
FXStreet
Graduated in Communication Sciences at the Universidad del Pais Vasco and Universiteit van Amsterdam, Guillermo has been working as financial news editor and copywriter in diverse Forex-related firms, like FXStreet and Kantox.

















