Micron Earnings Preview: The 5 key requirements for a successful Q4
- Micron will release fiscal Q4 earnings after the bell on Wednesday.
- Wall Street expects $31.82 in adjusted EPS on revenue of $51.5 billion for Q4.
- Micron's share price requires DRAM/HBM pricing to remain high and supply to remain tight.
- Guidance for $58 billion in Q1 revenue is key to a successful quarter.
Micron Technologies (MU) will release earnings after the close on Wednesday and the market views this release as the next big puzzle in the ongoing AI stock rally. Micron has been one of the primary beneficiaries of AI data centers monstrous demand for memory chips, but investors need to see that explosive growth carrying still higher in the fiscal fourth quarter.
Prices for DRAM and HBM chips, two of Micron's mainstays, have multiplied between five and seven times over the past 18 months due to the supply crunch, but bears suggest that Chinese memory chip supply is ramping up and that the market is already witnessing a slowing in DRAM price acceleration.
While the vast majority of analyst revisions have been upward over the past three months, it is clear that the skeptical crowd has been slowly growing. Micron heads into Wednesday's gauntlet with 14 upward revisions against three downward revisions.
Here are the five most important details that investors are focused on ahead of Micron's fiscal Q4 earnings release.
Micron's five major requirements for a successful Q4 earnings release
Micron’s fiscal Q4 release, which covers the three months that ended in late August, will hinge on five critical swing factors:
- Beating the fiscal Q4 consensus for EPS and revenue
- HBM4 demand growth
- DRAM and NAND pricing sustainability
- Gross margin retaining a sky-high, mid-80s percentage figure
- Fiscal Q1 2027 guidance hike
These are the items Wall Street analysts say will determine whether Micron’s stock surges or sells off.
1. Beating the Wall Street consensus for EPS and revenue
The latest consensus data from analysts tracking Micron calls for the Idaho-based firm to report $31.82 in adjusted earnings per share (EPS) on $51.5 billion in revenue. That latter figure has risen from the previous guidance of $50 billion in sales, showing how much expectations have grown for Micron.
Citi analyst Atif Malik, whose semiconductor analysis is well-respected on the Street, suggests that $31.45 in adjusted EPS on $51 billion in revenue is a better bet. Malik remains bullish on Micron but offers a somewhat staid price target of $1,300 on shares of the company that now trade closer to $1,070.
2. HBM4 demand growth and customer commitments
Analysts agree the single biggest driver of Micron’s earnings reaction will be confirmation that HBM4 and HBM4E demand remains structurally tight. This "high-bandwidth memory" is integral for AI data centers to carry out the heavy compute required for AI model training.
During the Q3 call in August, management said that HBM4 was already in "high-volume shipments for our lead customer's platform, and qualification samples have been shipped to multiple end-customers." Now it's time to see how much has been delivered in Q4.
They also claimed that HBM4E, built on 1-gamma DRAM technology, was well underway but that high-volume production wasn't slated until 2027. Investors will want to know if that production begins in fiscal Q1 or in later quarters.
Micron management said during the fiscal Q3 call that demand continues to outpace supply for HBM4. Investors will want to know how long this historically high pricing can last. Principally, that means the market wants to hear that more supply for 2027 is bound by long-term supply contracts.
HBM is now the core of Micron’s profit engine. Any signal of slowing demand or pricing pressure would hit the stock immediately.
3. DRAM pricing strength and tight supply setup
DRAM, which includes HBM, is still about 75% of Micron’s revenue, and analysts are laser-focused on whether the tight supply environment persists for the entire category.
The Wall Street consensus now expects $39.8 billion in overall DRAM revenue for Q4, up 23% QoQ. Then investors need to know whether DRAM revenue is still on pace to reach $42.8 billion in Q1, up another 12%.
Are DRAM gross profit estimates still projected to rise significantly in fiscal 2027? If Micron signals DRAM pricing is plateauing, the stock will fall. If pricing is still accelerating, Micron could re-rate higher.
Prominent AI bear Michael Burry recently said he had made new bearish bets on Micron. Specifically, Burry said that he has seen evidence of DDR4 oversupply that should start to cut into pricing in the near future.
Burry's put buying follows comments from Acer CEO Jason Chen that cracks are beginning to form in the memory shortage narrative. Chen said that he sees PC prices, which have been pushed up for the last few years based on the spiking costs of memory chips, will reach a plateau in the first half of 2027.
This is principally because Chen thinks that the shortage will begin to disappear next year as China's CXMT ramps up deliveries of its own DRAM products. Chen says that CXMT is on pace to hit 350,000 wafers per month, just 25,000 below Micron's 375,000 monthly estimate.
4. Gross margin durability near 86%
Last quarter, Micron guided to an 86% overall gross margin in Q4, an unheard-of level for memory. That comes on the back of an 84.6% gross margin figure in Q3.
Analysts want to know if this is peak margin or the new normal. If Micron shows margins can stay above 85% into 2027, analysts will raise long-term EPS targets dramatically.
In Q3, Micron reported gross margins of 87% for its Core Data Center Business unit and its Mobile & Client Business Unit. The Cloud Memory unit reported an 83% gross margin, while the Automotive & Embedded segment reported a 79% gross margin.
5. Fiscal Q1 2027 guidance
It's quite possible, even probable, that Micron's guidance for Q1 (the final quarter in calendar 2026) will be the primary mover of Micron's share price.
As it now stands, Wall Street expects Micron to earn $35.92 in adjusted EPS in fiscal Q1 on revenue of $57.93 billion.
Citi's Malik has a slightly lower projection than those topline numbers, but he is guiding for 13% and 15% growth in non-contracted DRAM and NAND prices, respectively.
If Micron guides Q1 2027 revenue above $58 billion and margins stay resilient at 85%, the stock could rally sharply.
Micron stock chart
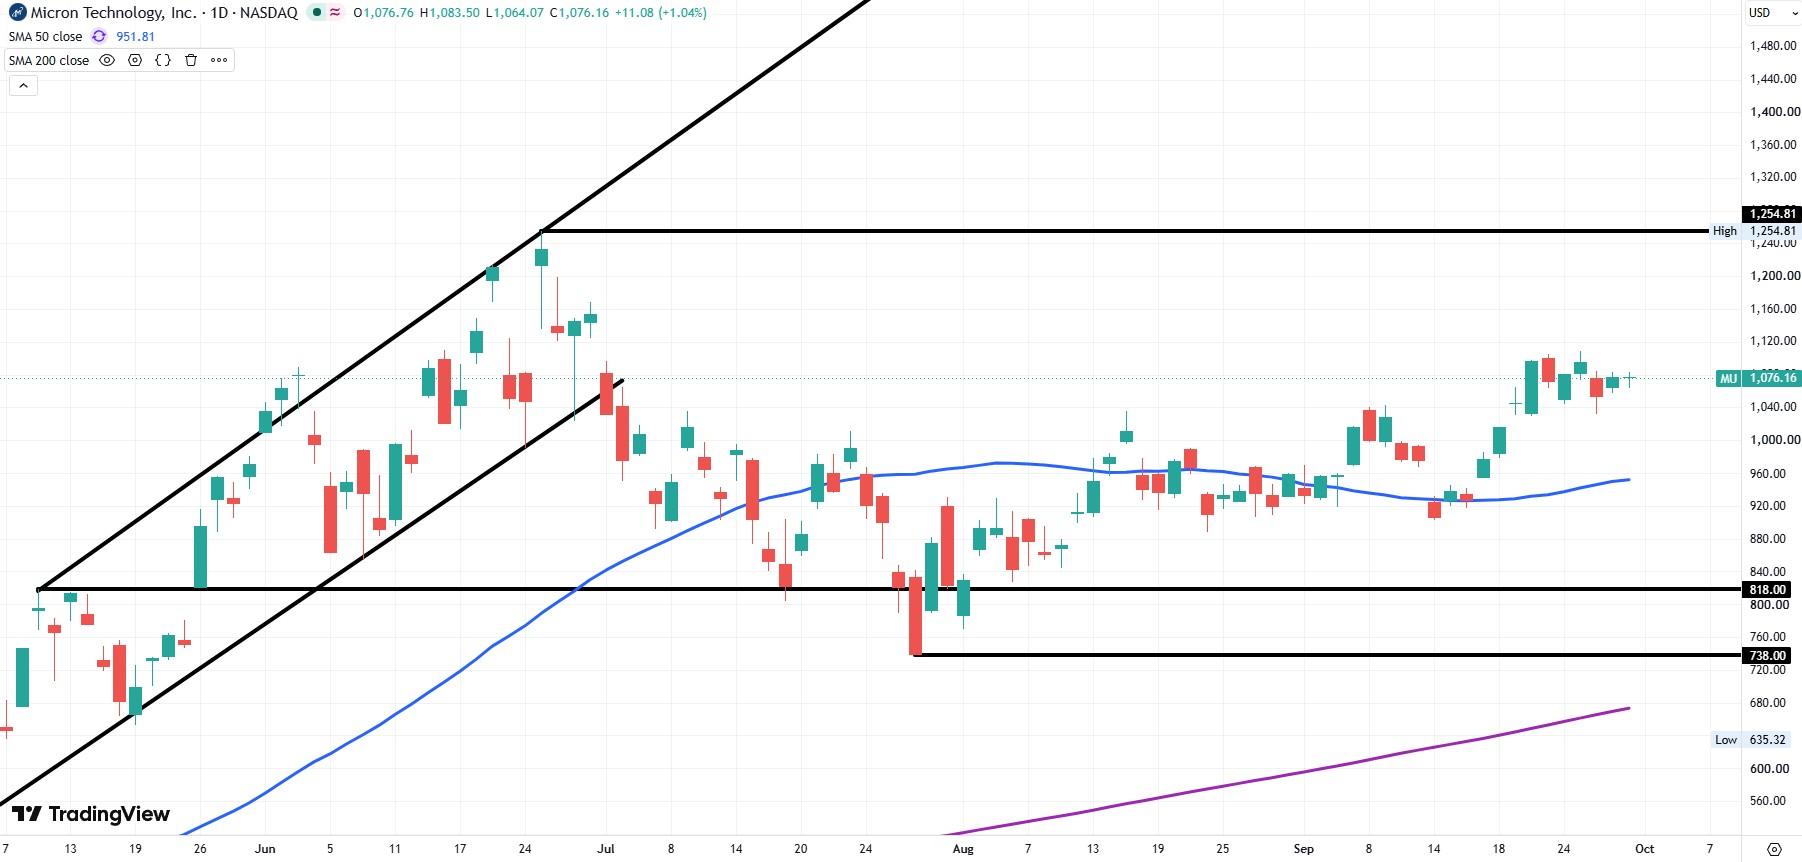
Micron's share price has been leaning higher since its July 29 low near $738. Trading well above its 50-day Simple Moving Average (SMA), Micron is poised to retest its all-time high near $1,255 if Wednesday's Q4 earnings release goes off as planned.
Much of the sell-off over the summer was a product of Leopold Aschenbrenner's Situational Awareness hedge fund going belly up. But now that period of forced selling is behind it, Micron is poised to break new ground.
However, poor guidance or sheepish remarks from executives could send MU stock down toward mid-year support circa $818.
Author

Clay Webster
FXStreet
Clay Webster grew up in the US outside Buffalo, New York and Lancaster, Pennsylvania. He began investing after college following the 2008 financial crisis.
















