Mexican Peso slips despite strong trade data, as US trade worries persist
- Mexican Peso weakens 0.48% even as Mexican labor market and trade data surprise to the upside.
- Ongoing US-China trade tensions cloud risk sentiment, limiting Peso's upside potential.
- Traders eye Mexico’s Q1 GDP, Business Confidence, and Manufacturing PMI data this week.
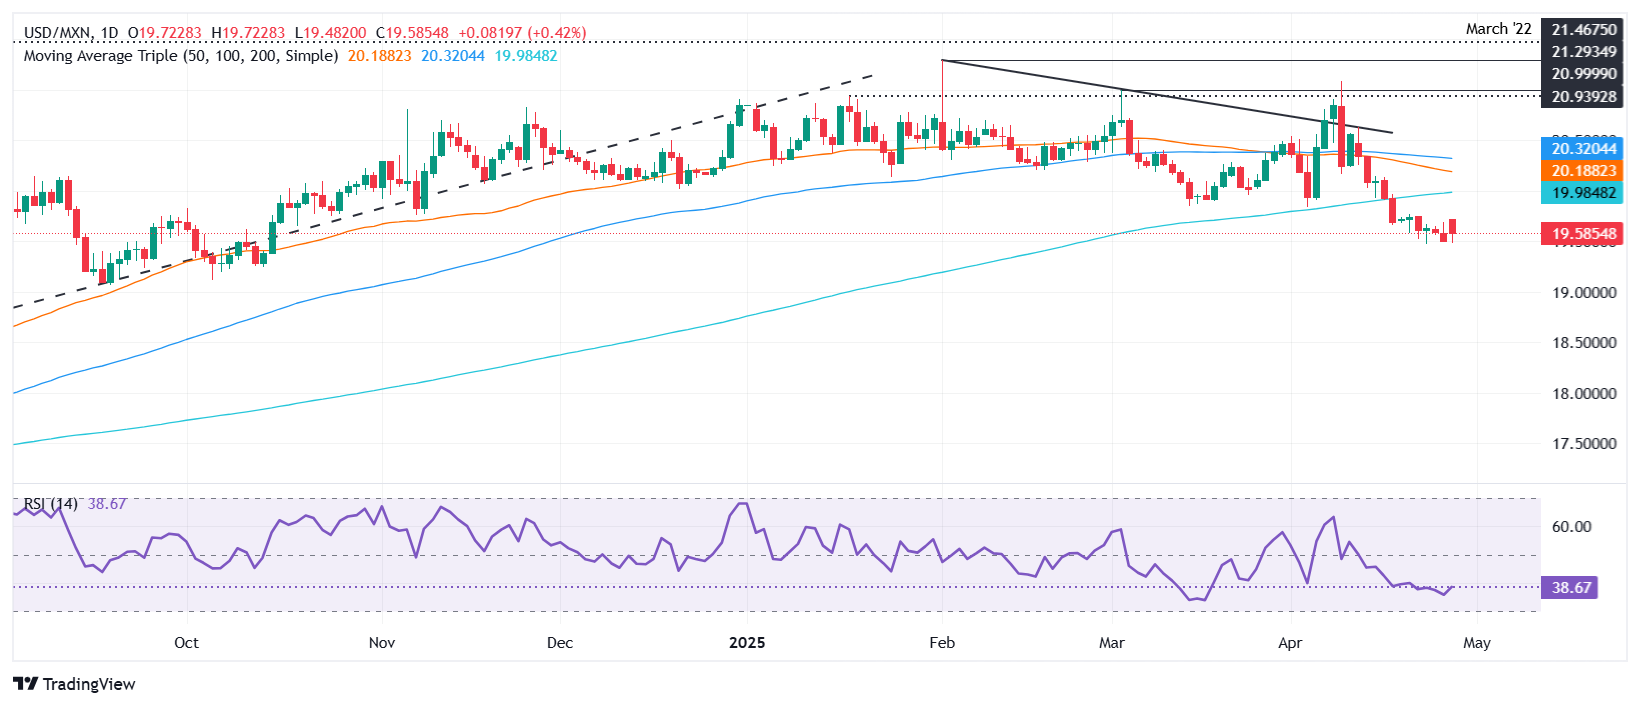
The Mexican Peso weakened by 0.48% against the US Dollar on Monday, despite Wall Street gains and a 0.64% drop in the US Dollar Index (DXY). At the time of writing, the USD/MXN trades at 19.58 after bouncing off daily lows of 19.47.
Market participants remain worried about US trade policies. Earlier, US Treasury Secretary Scott Bessent said they’re progressing on some trade proposals, but China’s negotiations have not even begun. CNBC revealed that China insists there are no tariff talks underway with Trump and Xi or with aides, despite US claims.
In the meantime, Mexico’s economic docket revealed labor market data, which showed the economy continuing to create jobs amid an ongoing economic deceleration. At the same time, the Trade Balance in March witnessed a surplus as exports outpaced imports, according to the Instituto Nacional de Estadistica y Geografia(INEGI).
Although the data further favored the downside of USD/MXN, traders remain reluctant to buy the Peso amid uncertainty about US trade news.
Mexico’s economic docket will feature Gross Domestic Product (GDP) figures for the first quarter, alongside the release of Business Confidence and S&P Global Manufacturing PMI data for April.
Daily digest market movers: Mexican Peso depreciates despite posting solid data
- Mexico’s Balance of Trade printed a surplus of $3.422 billion, exceeding forecasts of $2.60 billion, up 9.6% compared to February’s figures.
- The Unemployment Rate fell from 2.5% in the prior month to 2.2% in March, beneath forecasts of a 2.4% dip.
- Mexico’s Economic Activity in February expanded by 1% MoM, above forecasts for a 0.6% growth. On a yearly basis, activity dipped from 0% to -0.7%, better than expected.
- Economic data revealed during the week witnessed a reacceleration of inflation in the first half of April, revealed INEGI. Retail Sales in February were lower than expected, showcasing the ongoing economic slowdown.
- Last week, Banxico’s Deputy Governor Omar Mejia Castelazo revealed that the economy has been undergoing a slowdown since Q4 2023, he said in Washington.
- Citi Mexico's expectations survey shows that economists expect Banxico to cut its rate by 50 basis points at the May meeting. For the full year, they project the main reference rate to end near 7.75%.
- Regarding the USD/MXN exchange rate, private analysts see the exotic pair finishing at 20.93, up from 20.90. Inflation in 2025 is projected to finish at 3.78% with core figures at 3.80% mostly aligned with the previous poll.
- Mexico’s economy is expected to grow 0.2% in 2025, below the 0.3% projected in the prior survey.
USD/MXN technical outlook: Mexican Peso remains bullish as USD/MXN stays below 200-day SMA
USD/MXN is downward biased after clearing the 200-day Simple Moving Average of 19.94, which sponsored the pair’s last leg toward yearly lows of 19.46. Although sellers are in charge, they must print a daily close below the latter, so the pair could be poised to challenge the 19.00 psychological level.
Conversely, if USD/MXN climbs past the 200-day SMA, buyers could push the exchange rate towards 20.00. If surpassed, the next step would be the 20-day SMA at 20.15.
Mexican Peso FAQs
The Mexican Peso (MXN) is the most traded currency among its Latin American peers. Its value is broadly determined by the performance of the Mexican economy, the country’s central bank’s policy, the amount of foreign investment in the country and even the levels of remittances sent by Mexicans who live abroad, particularly in the United States. Geopolitical trends can also move MXN: for example, the process of nearshoring – or the decision by some firms to relocate manufacturing capacity and supply chains closer to their home countries – is also seen as a catalyst for the Mexican currency as the country is considered a key manufacturing hub in the American continent. Another catalyst for MXN is Oil prices as Mexico is a key exporter of the commodity.
The main objective of Mexico’s central bank, also known as Banxico, is to maintain inflation at low and stable levels (at or close to its target of 3%, the midpoint in a tolerance band of between 2% and 4%). To this end, the bank sets an appropriate level of interest rates. When inflation is too high, Banxico will attempt to tame it by raising interest rates, making it more expensive for households and businesses to borrow money, thus cooling demand and the overall economy. Higher interest rates are generally positive for the Mexican Peso (MXN) as they lead to higher yields, making the country a more attractive place for investors. On the contrary, lower interest rates tend to weaken MXN.
Macroeconomic data releases are key to assess the state of the economy and can have an impact on the Mexican Peso (MXN) valuation. A strong Mexican economy, based on high economic growth, low unemployment and high confidence is good for MXN. Not only does it attract more foreign investment but it may encourage the Bank of Mexico (Banxico) to increase interest rates, particularly if this strength comes together with elevated inflation. However, if economic data is weak, MXN is likely to depreciate.
As an emerging-market currency, the Mexican Peso (MXN) tends to strive during risk-on periods, or when investors perceive that broader market risks are low and thus are eager to engage with investments that carry a higher risk. Conversely, MXN tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















