Japanese Yen bullish potential seems intact amid hawkish BoJ expectations and a weaker USD
- The Japanese Yen pulls back from the monthly low touched against the USD earlier this Monday.
- Hopes for a US-Japan trade deal, BoJ rate hike bets, and geopolitical risks should support the JPY.
- US fiscal concerns and the divergent BoJ-Fed expectations warrant caution for USD/JPY bulls.
The Japanese Yen (JPY) remains depressed heading into the early European session as US President Donald Trump's decision to delay the implementation of tariffs on the European Union (EU) is seen undermining safe-haven assets. This, in turn, assists the USD/JPY pair to stage a modest intraday recovery from the 142.25-142.20 area or a fresh monthly low touched this Monday. However, hopes that Japan will strike a trade deal with the US, along with the growing acceptance that the Bank of Japan (BoJ) will continue raising interest rates, warrant some caution for aggressive JPY bears.
Meanwhile, hawkish BoJ expectations mark a big divergence in comparison to rising bets that the Federal Reserve (Fed) will lower borrowing costs further in 2025. This, along with concerns about the worsening US fiscal conditions, drags the US Dollar (USD) to over a one-month low at the start of a new week and should further contribute to limiting the downside for the lower-yielding JPY. Hence, it will be prudent to wait for strong follow-through buying before confirming that the USD/JPY pair has formed a near-term bottom and positioning for any meaningful appreciating move.
Japanese Yen is pressured by receding safe-haven demand on the back of US-EU trade optimism
- Following a third round of Japan-US talks, Japan's Prime Minister Shigeru Ishiba said on Sunday that Tokyo aims to advance tariff talks with the US, with the goal of achieving an outcome during the Group of Seven summit next month. Moreover, Japan's top tariff negotiator Ryosei Akazawa said that the schedule for the next Japan-US talks is being arranged and that he hopes to meet US Treasury Secretary Scott Bessent during his next visit.
- Friday's hotter-than-expected consumer inflation figures from Japan, along with expectations that higher wages will boost prices, keep the door open for further policy tightening by the Bank of Japan. In fact, BoJ officials recently showed a willingness to hike interest rates again if the economy and prices improve as projected. Investors, however, now seem convinced that policymakers will assess tariffs and trade flows before making the next move.
- US President Donald Trump delayed the implementation of a 50% tariff on the European Union from June 1 until July 9. Earlier on Sunday Ursula von der Leyen, president of the European Commission, said that the EU was ready to move quickly in trade talks with the U.S. but needed more time to strike a deal.
- On the geopolitical front, Russian forces launched a massive drone and missile attack across Ukrainian cities, marking the war's largest aerial attack to date. Speaking to reporters, US President Donald Trump called the attack unacceptable and said that he was considering new sanctions against Russia. Meanwhile, Israeli strikes over the past 24 hours killed at least 38 people in Gaza, including children. Israel had said earlier that it plans to seize full control of Gaza.
- Trump's sweeping tax cut and spending bill is expected to add around $4 trillion to the nation's deficit over the next 10 years and swell the federal government's debt. Moreover, traders have been pricing in the possibility that the Federal Reserve will lower borrowing costs further this year. This, in turn, drags the US Dollar to a nearly one-month low and also benefits the lower-yielding JPY, which, in turn, supports prospects for a further USD/JPY depreciation.
- The focus now shifts to this week's important US macro releases – Durable Goods Order on Wednesday, followed by the Prelim GDP print and the Personal Consumption Expenditure (PCE) Price Index on Thursday and Friday, respectively. Apart from this, the FOMC meeting minutes on Wednesday will play a key role in influencing the USD price dynamics, which, along with Tokyo CPI on Friday, should provide some meaningful impetus to the USD/JPY pair.
USD/JPY needs to strengthen beyond above 143.00 hurdle to support prospects for further gains
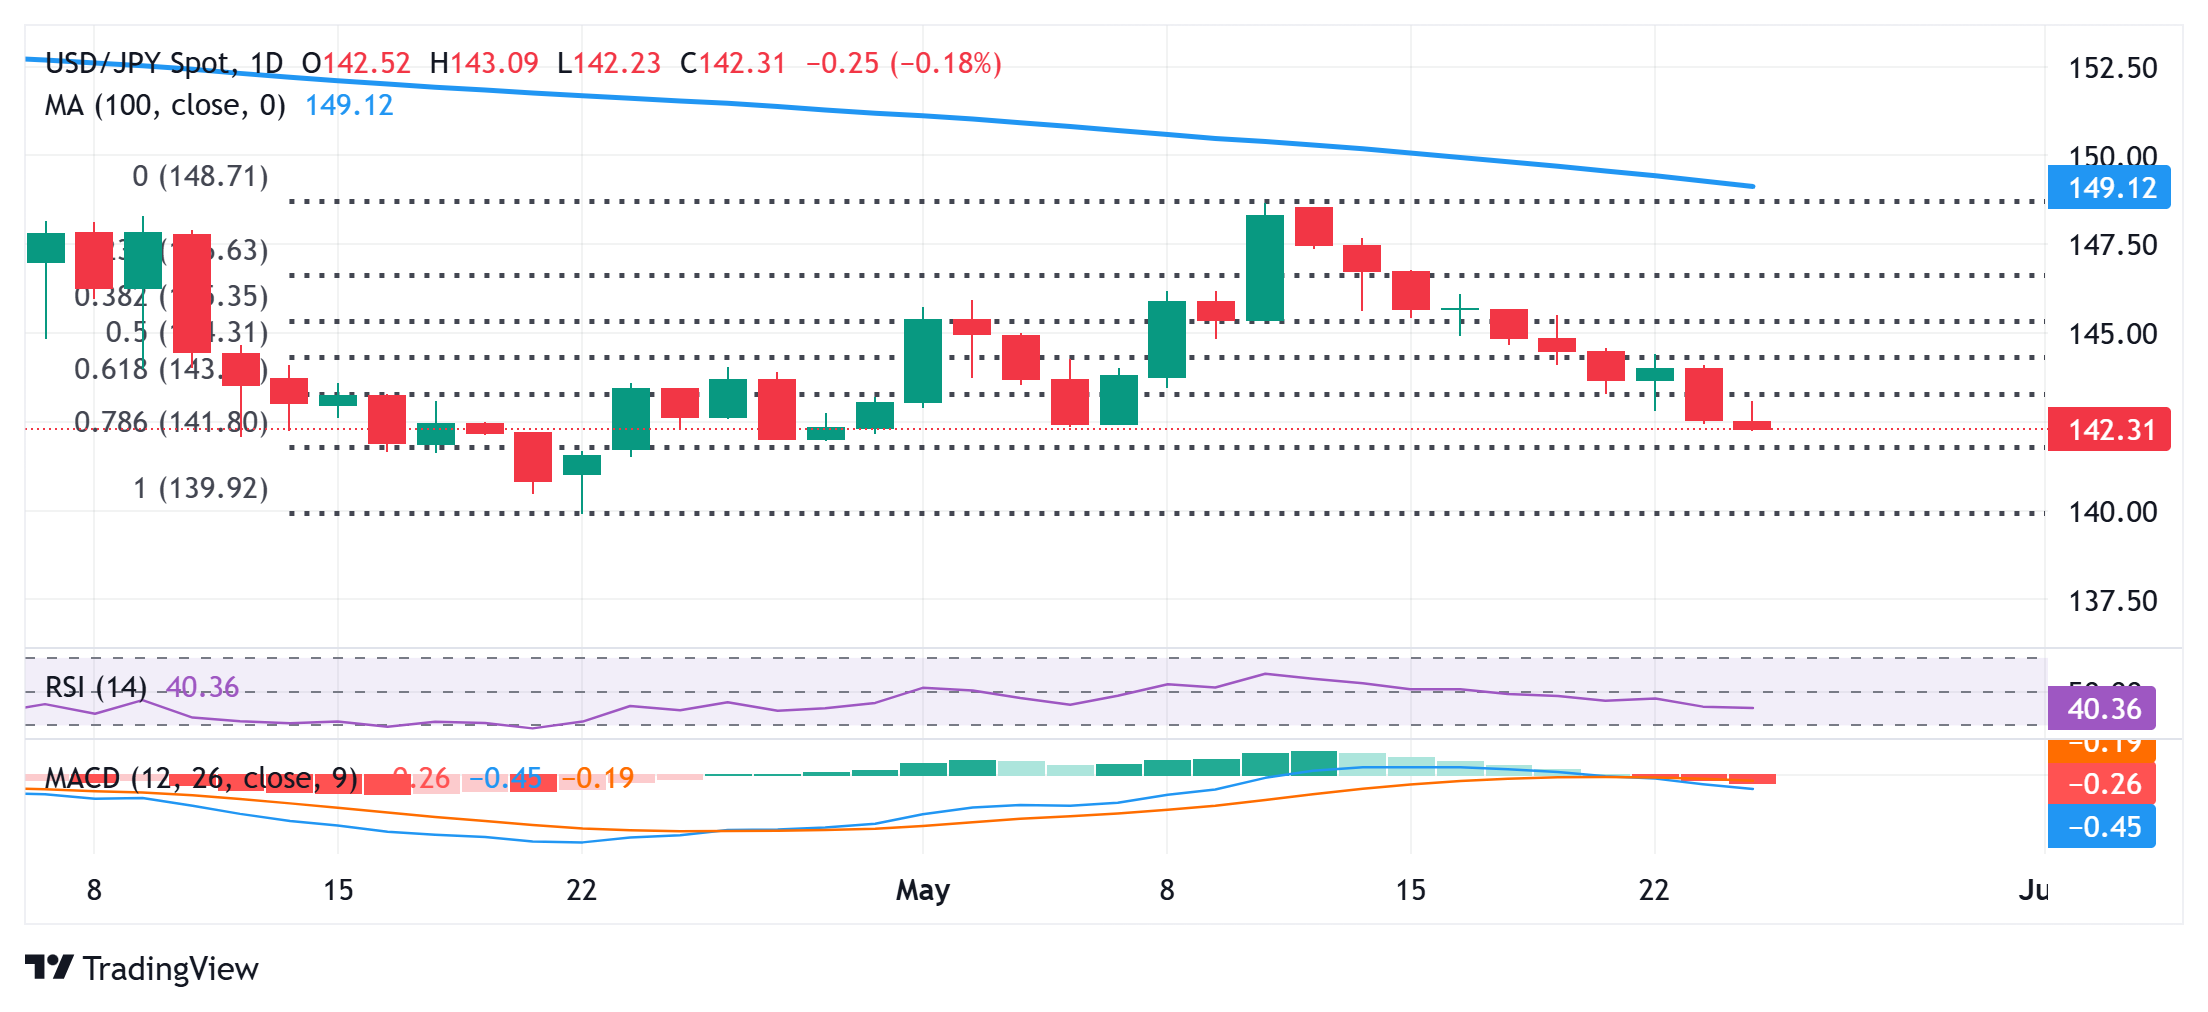
From a technical perspective, an intraday failure near the 143.00 round-figure mark validates last week's breakdown below the 61.8% Fibonacci retracement level of April-May move higher. Adding to this, oscillators on the daily chart have been gaining negative traction and suggest that the path of least resistance for the USD/JPY pair remains to the downside. Some follow-through selling below the 142.00 mark will reaffirm the bearish outlook and drag spot prices below the 141.55 intermediate support, towards the 141.00 round figure. The subsequent downfall would expose the year-to-date low, or levels below the 140.00 psychological mark touched on April 22.
On the flip side, the Asian session peak, around the 143.10 area, now seems to act as an immediate hurdle, above which a bout of a short-covering move could lift the USD/JPY pair to the 143.65 region en route to the 144.00 round figure. The latter should act as a strong barrier, which, if cleared, could pave the way for a further recovery. However, the move higher might still be seen as a selling opportunity near the 144.80 zone and remain capped near the 145.00 psychological mark.
Fed FAQs
Monetary policy in the US is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability and foster full employment. Its primary tool to achieve these goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, it raises interest rates, increasing borrowing costs throughout the economy. This results in a stronger US Dollar (USD) as it makes the US a more attractive place for international investors to park their money. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates to encourage borrowing, which weighs on the Greenback.
The Federal Reserve (Fed) holds eight policy meetings a year, where the Federal Open Market Committee (FOMC) assesses economic conditions and makes monetary policy decisions. The FOMC is attended by twelve Fed officials – the seven members of the Board of Governors, the president of the Federal Reserve Bank of New York, and four of the remaining eleven regional Reserve Bank presidents, who serve one-year terms on a rotating basis.
In extreme situations, the Federal Reserve may resort to a policy named Quantitative Easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used during crises or when inflation is extremely low. It was the Fed’s weapon of choice during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy high grade bonds from financial institutions. QE usually weakens the US Dollar.
Quantitative tightening (QT) is the reverse process of QE, whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing, to purchase new bonds. It is usually positive for the value of the US Dollar.
Author

Haresh Menghani
FXStreet
Haresh Menghani is a detail-oriented professional with 10+ years of extensive experience in analysing the global financial markets.

















