EUR/USD posts fresh two-month low as US Inflation rose faster than expected
- EUR/USD weakens after the US CPI data for September came in hotter than expected.
- Fed officials are highly concerned about reviving job growth.
- The Euro is under pressure as the ECB is expected to reduce interest rates further by 50 bps by year-end.

EUR/USD prints a fresh two-month low near 1.0900 in Thursday’s North American session. The major currency weakens after the release of the United States (US) Consumer Price Index (CPI) report for September, which showed that inflationary pressures grew at a faster-than-projected pace.
The annual core CPI – which excludes volatile food and energy prices – accelerated to 3.3% from the estimates and the August reading of 3.2%. In the same period, the headline CPI rose by 2.4%, faster than estimates of 2.3% but slower than the prior release of 2.5%. The month-on-month headline and core CPI grew steadily by 0.2% and 0.3%, respectively, faster than estimates.
Though the inflation data turned out stubborn, it is less likely to weigh on market expectations for the Federal Reserve (Fed) to reduce interest rates further by 50 basis points (bps) in the remainder of the year.
Recent commentaries from Fed officials have indicated that they are confident about price pressures remaining on track to return sustainably to the bank’s target of 2%. Fed policymakers are highly focused on reviving labor demand due to which they unanimously voted for a larger-than-usual rate cut size of 50 basis points (bps) in the September policy meeting.
Daily digest market movers: EUR/USD weakens amid Euro's underperformance
- EUR/USD slides further to near 1.0900 due to the Euro’s (EUR) underperformance against its major peers amid escalating European Central Bank (ECB) dovish bets. A majority of ECB officials have argued in favor of reducing interest rates further as risks of inflation remaining persistent in the Eurozone have significantly eased after the September flash annual Harmonized Index of Consumer Prices (HICP) report decelerated to 1.8%, the lowest since April 2021. Also, growing risks to economic growth have allowed traders to price in a 25-bps interest rate cut in each of the remaining two meetings this year.
- German economic ministry said on Wednesday that they are expecting the economy to end the year with a 0.2% decline in the overall output. Earlier, the economic ministry projected a 0.3% growth but was forced to revise forecasts due to structural problems and geopolitical issues. Being the largest nation in the Eurozone, the impact of a de-growth in the German economy would be high on the Euro.
- On the economic front, annual German Retail Sales, a key measure of consumer spending that prompts inflationary pressures, expanded at a robust pace of 2.1% in August after contracting by 1.6% in July. On month-on-month, the consumer spending measure rose at a faster pace of 1.6% from 1.5% in July.
- Meanwhile, ECB Monetary Policy Meeting Accounts for September, released in late Europe, showed that policymakers expect inflation in the Eurozone to rise again in the latter part of the year. ECB accounts also indicated that officials see inflation remaining on track to the bank’s target of 2% but refrained from announcing a victory over it.
Technical Analysis: EUR/USD sees more downside below 200-day EMA
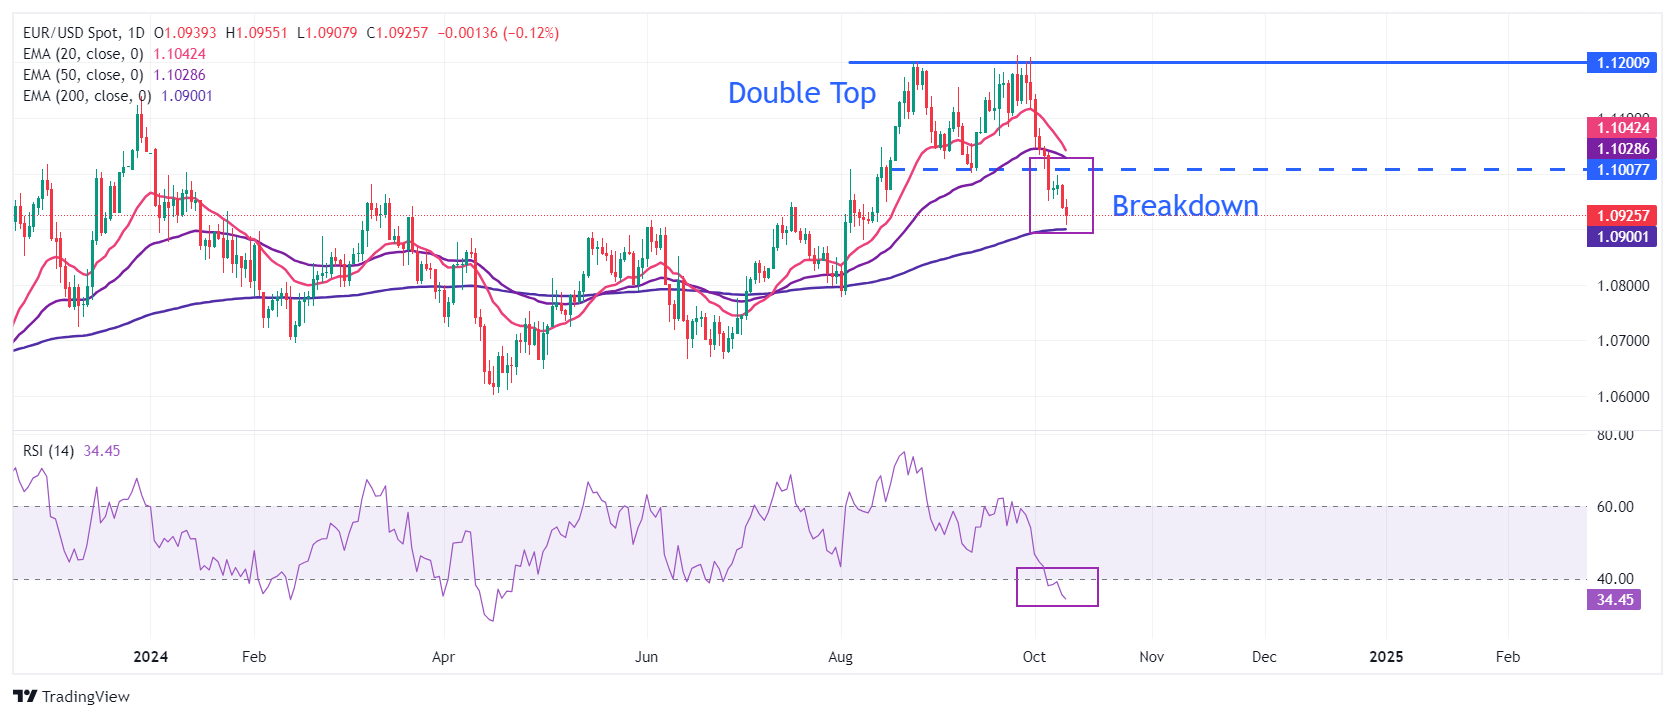
EUR/USD extends its downside to near 1.0900 after failing to hold the key support of 1.0950. The major currency pair weakened after it delivered a breakdown of the Double Top chart pattern formation on a daily timeframe. The above-mentioned chart pattern was triggered after the shared currency pair broke below the September 11 low of 1.1000.
The 14-day Relative Strength Index (RSI) settles inside the bearish range of 20.00-40.00, suggesting more weakness ahead.
Looking down, the pair is expected to find support near the round-level support of 1.0800 after breaking below the 200-day EMA around 1.0900. On the upside, the September 11 low of 1.1000 and the 20-day EMA at 1.1090 will be major resistance zones.
Economic Indicator
Consumer Price Index ex Food & Energy (YoY)
Inflationary or deflationary tendencies are measured by periodically summing the prices of a basket of representative goods and services and presenting the data as the Consumer Price Index (CPI). CPI data is compiled on a monthly basis and released by the US Department of Labor Statistics. The YoY reading compares the prices of goods in the reference month to the same month a year earlier. The CPI Ex Food & Energy excludes the so-called more volatile food and energy components to give a more accurate measurement of price pressures. Generally speaking, a high reading is bullish for the US Dollar (USD), while a low reading is seen as bearish.
Read more.Last release: Thu Oct 10, 2024 12:30
Frequency: Monthly
Actual: 3.3%
Consensus: 3.2%
Previous: 3.2%
Source: US Bureau of Labor Statistics
The US Federal Reserve has a dual mandate of maintaining price stability and maximum employment. According to such mandate, inflation should be at around 2% YoY and has become the weakest pillar of the central bank’s directive ever since the world suffered a pandemic, which extends to these days. Price pressures keep rising amid supply-chain issues and bottlenecks, with the Consumer Price Index (CPI) hanging at multi-decade highs. The Fed has already taken measures to tame inflation and is expected to maintain an aggressive stance in the foreseeable future.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.

















