EUR/USD climbs on risk-on sentiment swing, approaches 1.11
- EUR/USD gains half of a percent as markets force the Greenback lower.
- Impending major central banking summit has investors looking out for Fedspeak.
- EU and US PMIs due later in the week.

EUR/USD rallied into a half-percent gain on Monday as investors kick off the new trading week with a fresh dog-pile into broad-market buy buttons. The Fiber was bolstered cleanly above 1.1050 and is headed firmly for a retest of the 1.1100 handle. Recently, a rough patch of bad US data reignited investor fears of an impending US recession, but a late upswing in more recent US data prints has soothed investor nerves, who have to returned to waiting for signs of rate cuts from the Federal Reserve (Fed).
Forex Today: Attention shifts to Fedspeak ahead of Jackson Hole
The midweek stretch is a quiet affair as markets await key PMI data from both the EU and the US, as well as the kickoff of this year’s Jackson Hole Economic Symposium. All three are expected to land on markets beginning on Thursday.
Pan-EU HCOB Purchasing Managers Index (PMI) figures are expected to test higher in August. EU MoM Manufacturing PMI numbers are expected to clip into 46.0 from 45.8, while the Services PMI component is forecast to hold steady at 51.9 over the same period.
Across the Atlantic, US PMI figures are expected to soften on Thursday. US Manufacturing PMI in August is expected to tick down slightly to 49.5 from 49.6, while US Services PMI numbers are forecast to fall an entire point to 54.0 from 55.0.
The Jackson Hole Economic Symposium, slated to kick off a multi-day central banker extravaganza on Thursday, will have investors across the globe tuning in for any signals from Fed policymakers about the likelihood of a Fed rate cut in September.
Recent bets of a double cut in September have eased significantly after reaching a peak of 70% two weeks ago. According to the CME’s FedWatch Tool, rate markets are pricing in a scant one-in-five chance of a 50 bps cut on September 18. Overall, markets still have a 25 bps cut in September fully priced in, with three or four quarter-point cuts expected by the end of the year.
EUR/USD price forecast
EUR/USD set a new bidding high for 2024 on Monday, tapping 1.1086 as markets lean firmly into a risk-on stance. The Euro continues to rise against the Greenback unabated, kicking firmly above the 1.1000 handle as bidders drive the Fiber towards 1.1100. Bullish momentum fell short of reclaiming the key technical price handle, but buying power remains firm as the pair continues to climb.
EUR/USD has chalked in a nearly 3% gain bottom-to-top since the beginning of August, after the pair launched north following a swing low into the 200-day Exponential Moving Average (EMA) near 1.0800.
EUR/USD daily chart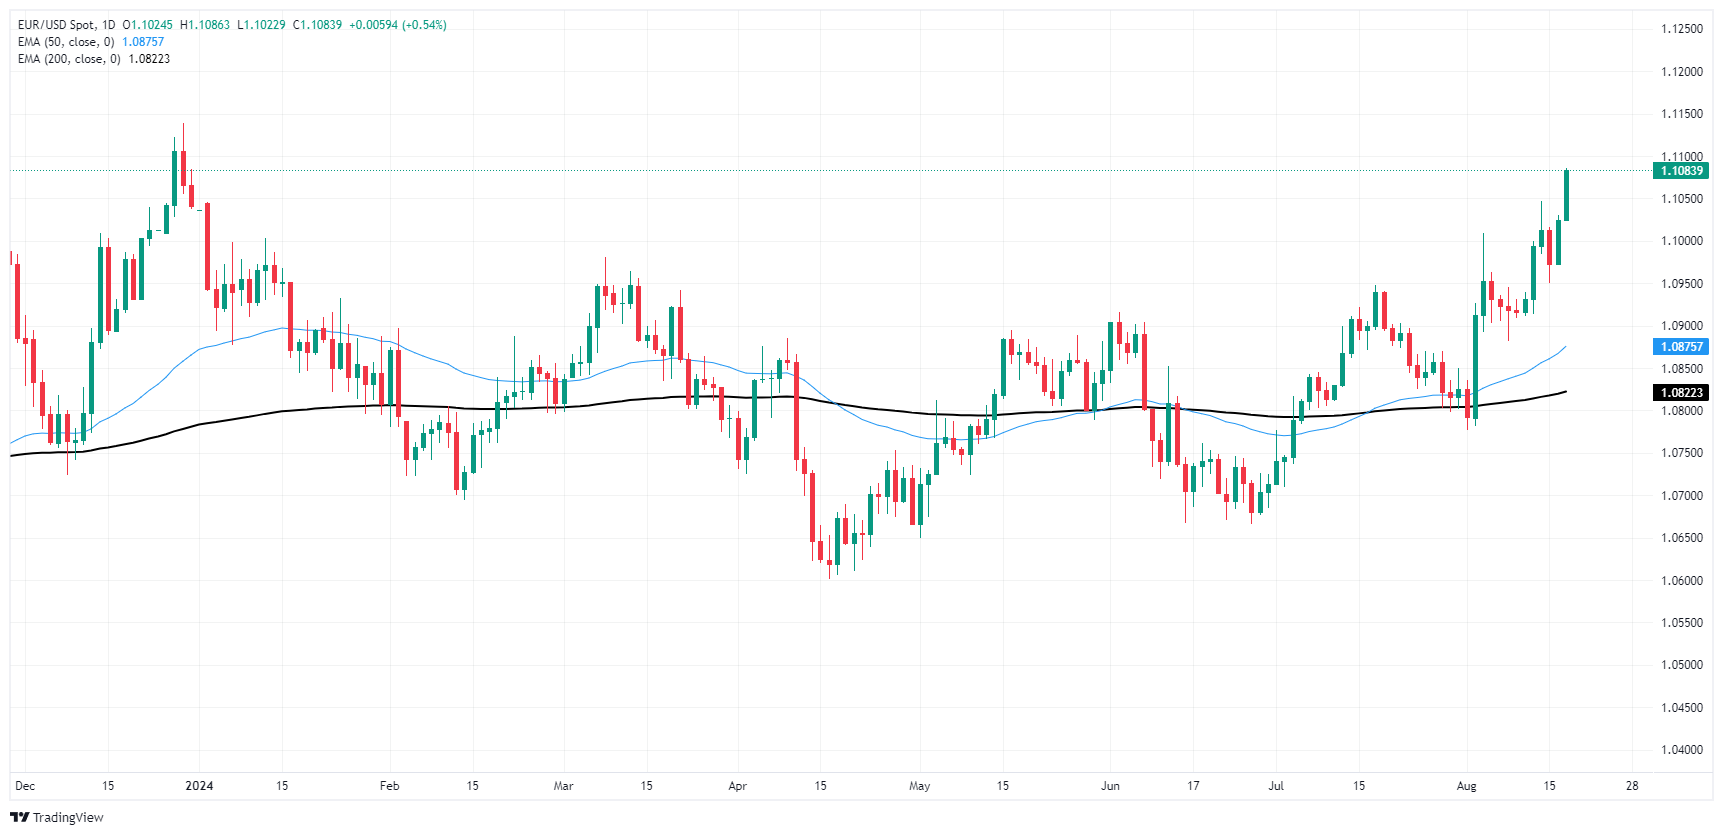
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















