Canadian Dollar whipsaws after Canadian CPI inflation report
- The Canadian Dollar pared early losses on Tuesday, but remains in key congestion area.
- Canadian CPI inflation rose slightly faster than expected in September, putting pressure on BoC watchers.
- US CPI inflation data is due this week and will give the Fed one last datapoint before its next rate call.
The Canadian Dollar (CAD) found some room to move on the high side of the US Dollar (USD) on Tuesday, paring away early session losses and keeping the Loonie entrenched in a recent consolidation zone. Bullish momentum behind the CAD remains next to non-existent, but scrambling Loonie traders will take any support they can get as they battle against six-month lows.
Canadian Consumer Price Index (CPI) inflation came in higher than expected across the board on Tuesday, putting renewed pressure on Bank of Canada (BoC) rate watchers. With inflation continuing to ride on the high side of BoC target ranges, the Canadian central bank will have less room to drop interest rates to help shore up a flagging Canadian economy that is suffering at the hands of US trade tariffs.
Daily digest market movers: Canadian Dollar keeps losses under control post-CPI
- Despite finding mid-session gains, the Canadian Dollar remains stuck near six-month lows against the US Dollar.
- USD/CAD remains capped below a hard technical barrier above 1.4050.
- Canadian CPI inflation rose more than expected in September, with headline CPI inflation rising to 2.4% YoY.
- With Canadian inflation metrics back on the rise, the BoC will have a harder time pursuing further interest rate cuts to bolster the economy, however their next interest rate call is still likely to be another cut.
- US CPI inflation data due on Thursday will be the real test for datawatchers this week.
Canadian Dollar price forecast
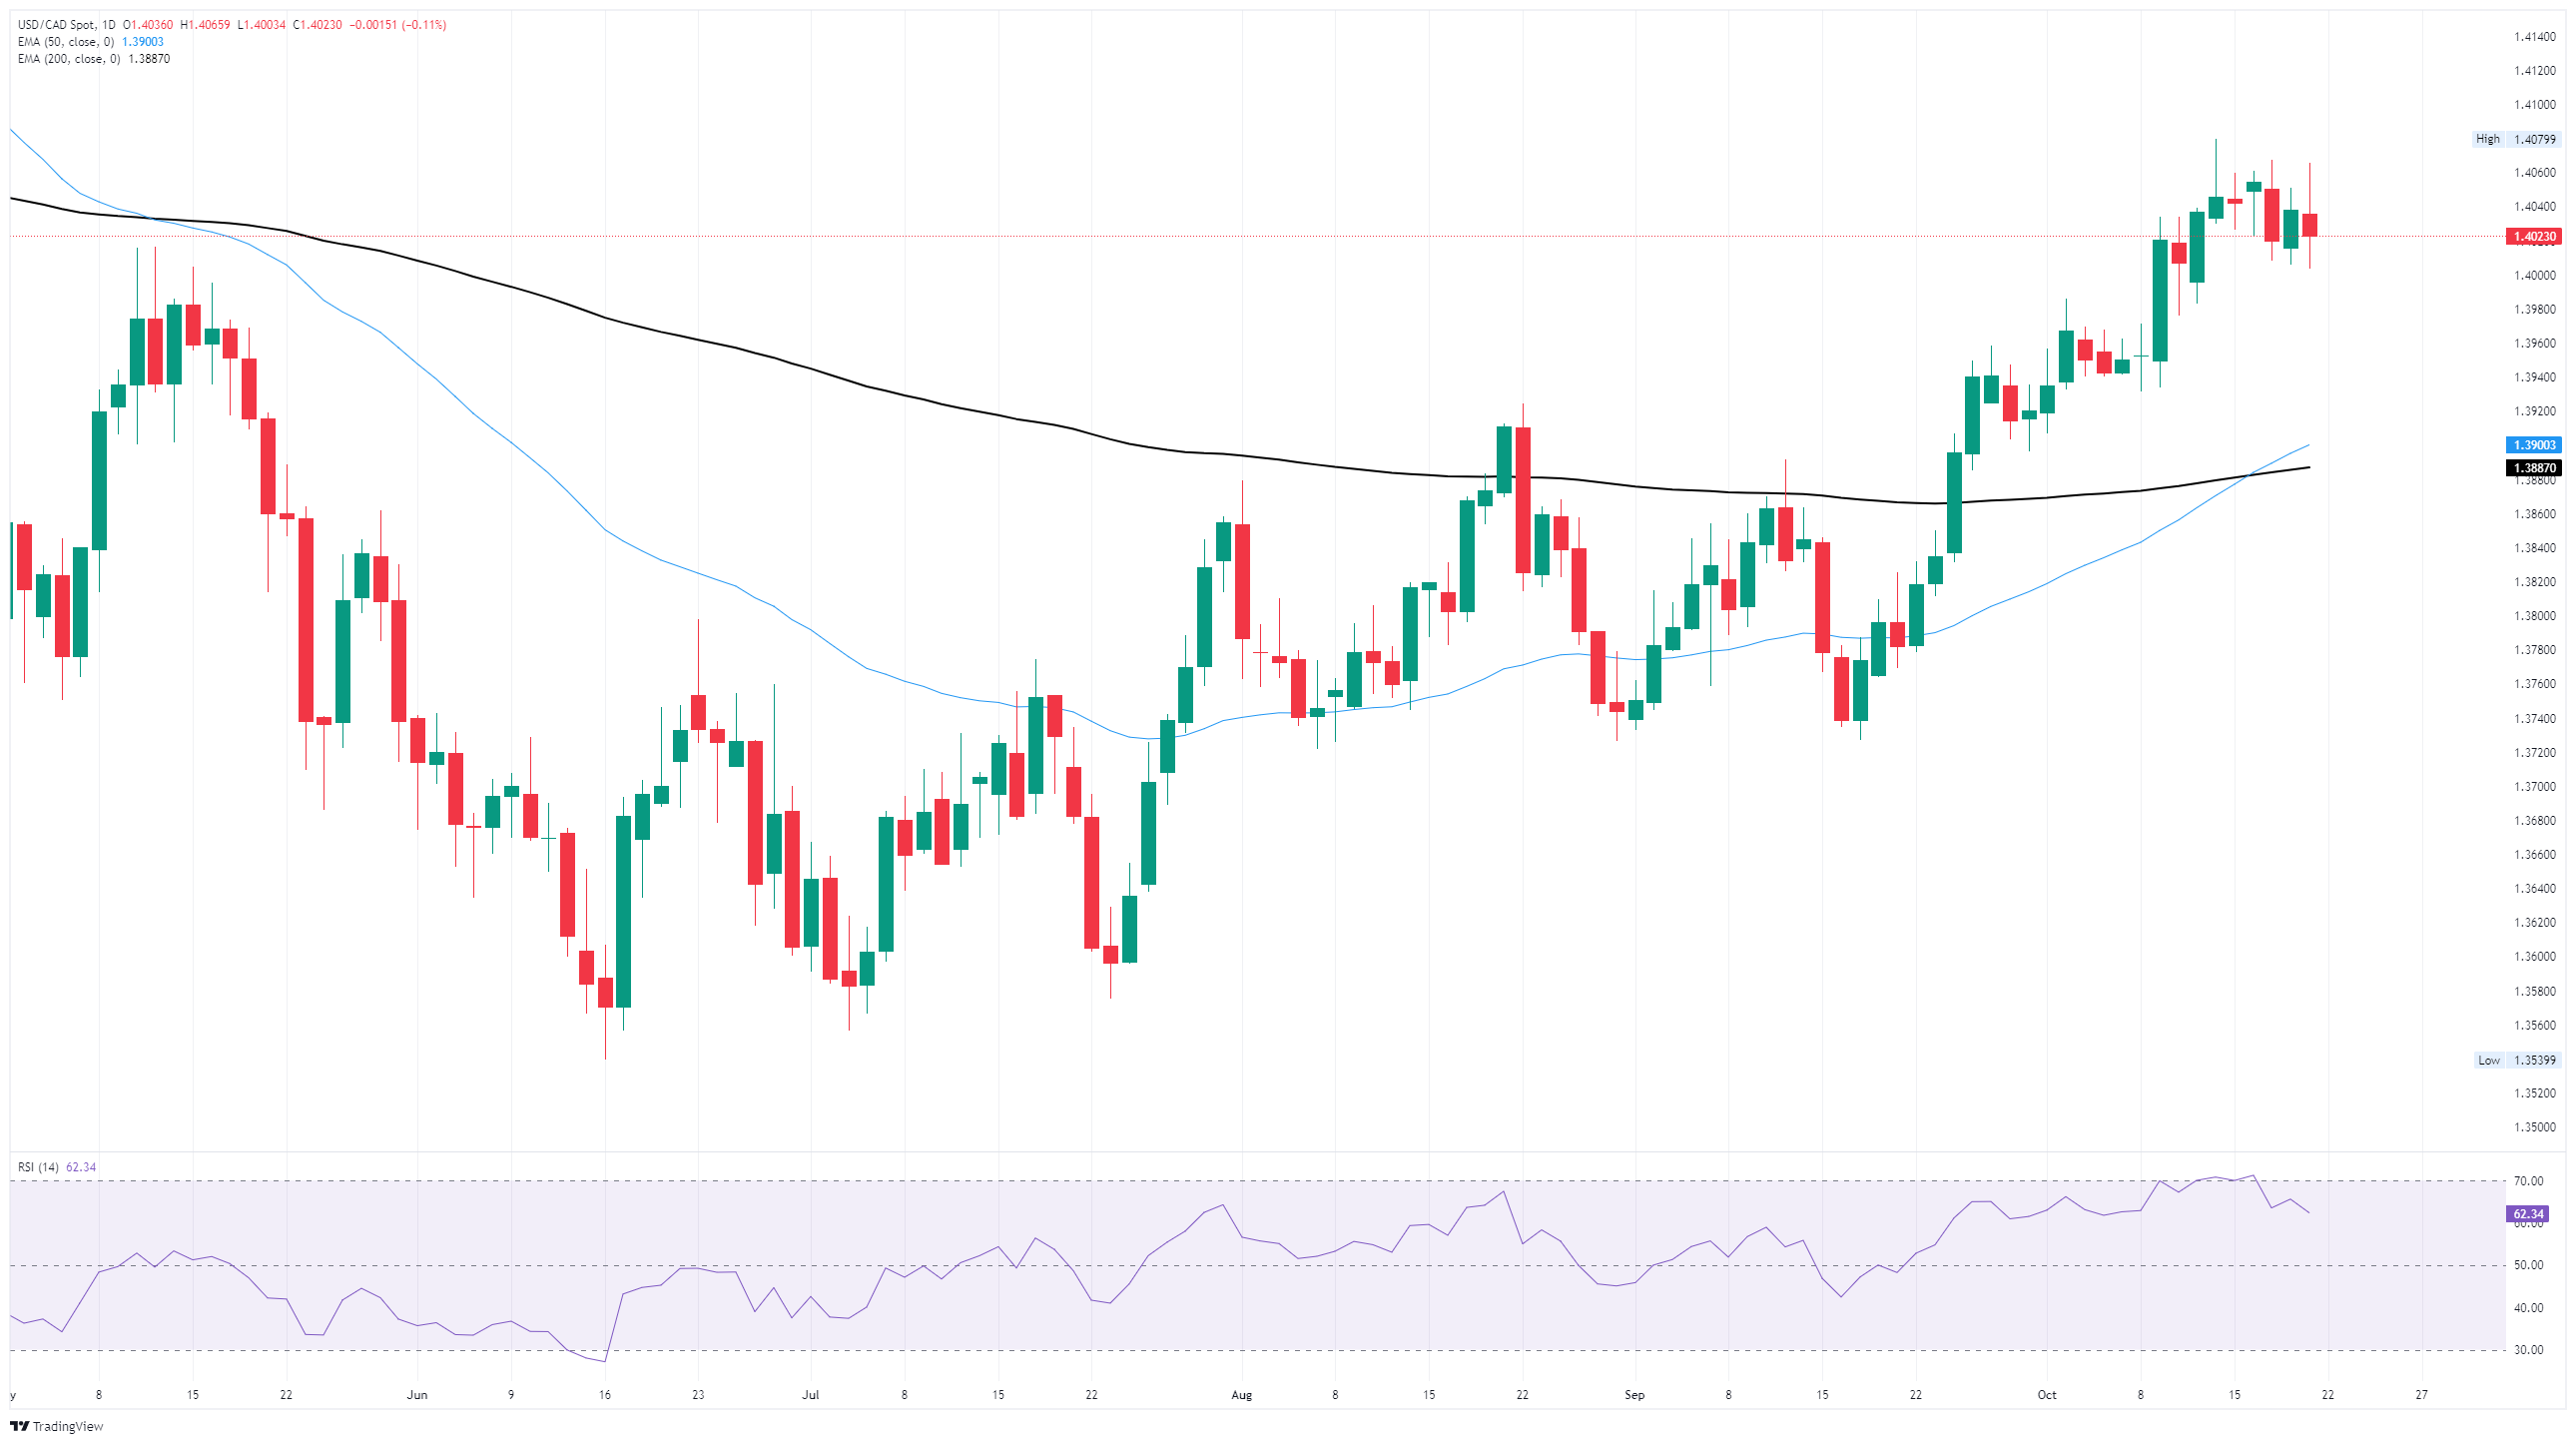
The USD/CAD daily chart shows the US Dollar trading near 1.4025 against the Canadian Dollar, easing slightly after testing resistance around 1.4080. The pair has been trending higher since early September, building a clear pattern of higher highs and higher lows. The 50-day Exponential Moving Average (EMA), now near 1.3900, has moved above the 200-day EMA at 1.3885, forming what traders often call a “golden cross.” This crossover usually signals improving medium-term momentum and growing buying interest.
Price action suggests that the market is pausing after a strong rally. Sellers are beginning to emerge around the 1.4070–1.4100 zone, which has acted as resistance in recent sessions. On the downside, the 1.3950–1.3900 area looks like the first layer of support. If buyers can defend that region, the broader uptrend remains intact. A drop below it could open the door to a deeper retracement toward 1.3800.
The Relative Strength Index (RSI) is sitting around 62, pointing to steady bullish momentum without signaling overbought conditions. That leaves room for further gains if fresh catalysts support the move.
Overall, the pair maintains a constructive tone, but with the rally showing signs of fatigue near 1.41, traders appear to be waiting for new drivers such as upcoming U.S. data or commentary from the Bank of Canada before committing to the next leg higher.
USD/CAD daily chart
Canadian Dollar FAQs
The key factors driving the Canadian Dollar (CAD) are the level of interest rates set by the Bank of Canada (BoC), the price of Oil, Canada’s largest export, the health of its economy, inflation and the Trade Balance, which is the difference between the value of Canada’s exports versus its imports. Other factors include market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – with risk-on being CAD-positive. As its largest trading partner, the health of the US economy is also a key factor influencing the Canadian Dollar.
The Bank of Canada (BoC) has a significant influence on the Canadian Dollar by setting the level of interest rates that banks can lend to one another. This influences the level of interest rates for everyone. The main goal of the BoC is to maintain inflation at 1-3% by adjusting interest rates up or down. Relatively higher interest rates tend to be positive for the CAD. The Bank of Canada can also use quantitative easing and tightening to influence credit conditions, with the former CAD-negative and the latter CAD-positive.
The price of Oil is a key factor impacting the value of the Canadian Dollar. Petroleum is Canada’s biggest export, so Oil price tends to have an immediate impact on the CAD value. Generally, if Oil price rises CAD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Oil falls. Higher Oil prices also tend to result in a greater likelihood of a positive Trade Balance, which is also supportive of the CAD.
While inflation had always traditionally been thought of as a negative factor for a currency since it lowers the value of money, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Higher inflation tends to lead central banks to put up interest rates which attracts more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in Canada’s case is the Canadian Dollar.
Macroeconomic data releases gauge the health of the economy and can have an impact on the Canadian Dollar. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the CAD. A strong economy is good for the Canadian Dollar. Not only does it attract more foreign investment but it may encourage the Bank of Canada to put up interest rates, leading to a stronger currency. If economic data is weak, however, the CAD is likely to fall.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















