What to expect in the week ahead
Investors are still digesting last week’s price action as we start a new week. US stocks sold off sharply, with the Swiss and UK indices attracting inflows as tech sold off. Sovereign bonds, particularly Treasuries, rallied and acted as a safe haven as the AI trade suffered another bout of volatility. The oil price also surged and Brent crude closed the week just below $110 per barrel, after more attacks on Russian energy infrastructure and further escalation in the Middle East.
UK budget latest
Even though the UK Budget is next week, there were few fresh leaks over the weekend, and the newsflow from the UK Treasury was light. This comes after the bombshell that UK banks will be hit by a profit surcharge tax that could be up to 8%. Although this is only a rumour, the chancellor has already written his budget, so if he is not denying an extra banking tax, it means it’s part of the plan.
Critics argue that this is short-sighted, and will hurt economic growth since it will limit access to borrowing or make borrowing even more expensive. Added to this, it increases an already record high tax burden for the UK.
The FTSE 100 may have been one of the most resilient indices last week, but the banks sold off on Friday. In fairness the 1% decline for NatWest and Lloyds was modest, which suggests that those in the know in markets assume that any plan to tax banks could be watered down, or countered with a cut to the reserve requirements. Added to this, the surcharge tax is less onerous than a windfall tax, which also limited the bank sector sell off.
As we start a new week, reports suggest that the Chancellor, John Healey, will introduce measures to stop further leaks. However, soon after this there were fresh reports that the Chancellor will implement income tax on families who pass businesses down the generations, rather than capital gains tax rates. This will cause a massive outcry, and add to the view that Labour is anti-growth and a high tax/ high spend party. Interestingly, there have been very few spending cuts leaked in advance of this budget, which is probably a sign that there won’t be any.
So far, nothing that Healey has or hasn’t said has spooked the UK bond market. Gilt yields have fallen in recent days, and the 10-year yield is lower by 5bps so far in October. We still have elevated Gilt yields, so Healey will need to tread carefully in the coming days.
Are French riots a risk to the bond market?
The sell off in AI and the French riots have taken the limelight off the UK, which, for now, feels more stable than elsewhere. From a market perspective, the violence and protests in France over the weekend could impact the French - German sovereign bond spread at the start of this week. This spread is already elevated, at over 135bps. This could widen out towards 150bp, since political and social pressure are building at the same time as the country is trying to put together a fiscal tightening in its budget for next year. The newsflow from France could also impact the euro. The euro was down slightly vs. the USD last week, although att eh start of the week it is below $1.12. If these riots boost support for the anti-EU Marine Le Pen, then we may see further declines for the single currency.
Earnings season digest: Concerns about AI collide with earnings reports this week
The focus will also shift to the US, as earnings season continues. Netflix, Meta and Tesla are the highlights this week, with the first of the Magnificent 7 reports giving us a steer on whether strong tech earnings can stop the slide in AI stocks.
The Philadelphia semiconductor index slumped 12% last week, the chip heavy Korean Kospi index also fell 16%. Concerns about slowing revenue growth for Anthropic, and cracks starting to appear in the AI boom, will come up against expected strong earnings in the coming days.
Hyperscalers more resilient to AI sell off
Meta’s results will be worth watching closely, after it recently launched a well received AI agent for businesses. However, Meta’s share price fell after its earnings report for Q2, as investors worried about the level of AI spending. So far, hyperscalers like Meta have been more resilient than chip stocks during this bout of market volatility. Meta’s share price fell 2% last week, compared to a 25% slump for CoreWeave, and a 20% fall for SanDisk.
Although volatility spiked last week, the recent bumps in the road for the AI trade have been short lived. Could signs of robust capex spending at Meta and Tesla rejuvenate the chip trade? Valuations fell sharply last week, and we think any sign that revenue growth for the chip makers like SanDisk, Micron, AMD, Nvidia etc. will continue to expand in the coming months could be used as a buying opportunity.
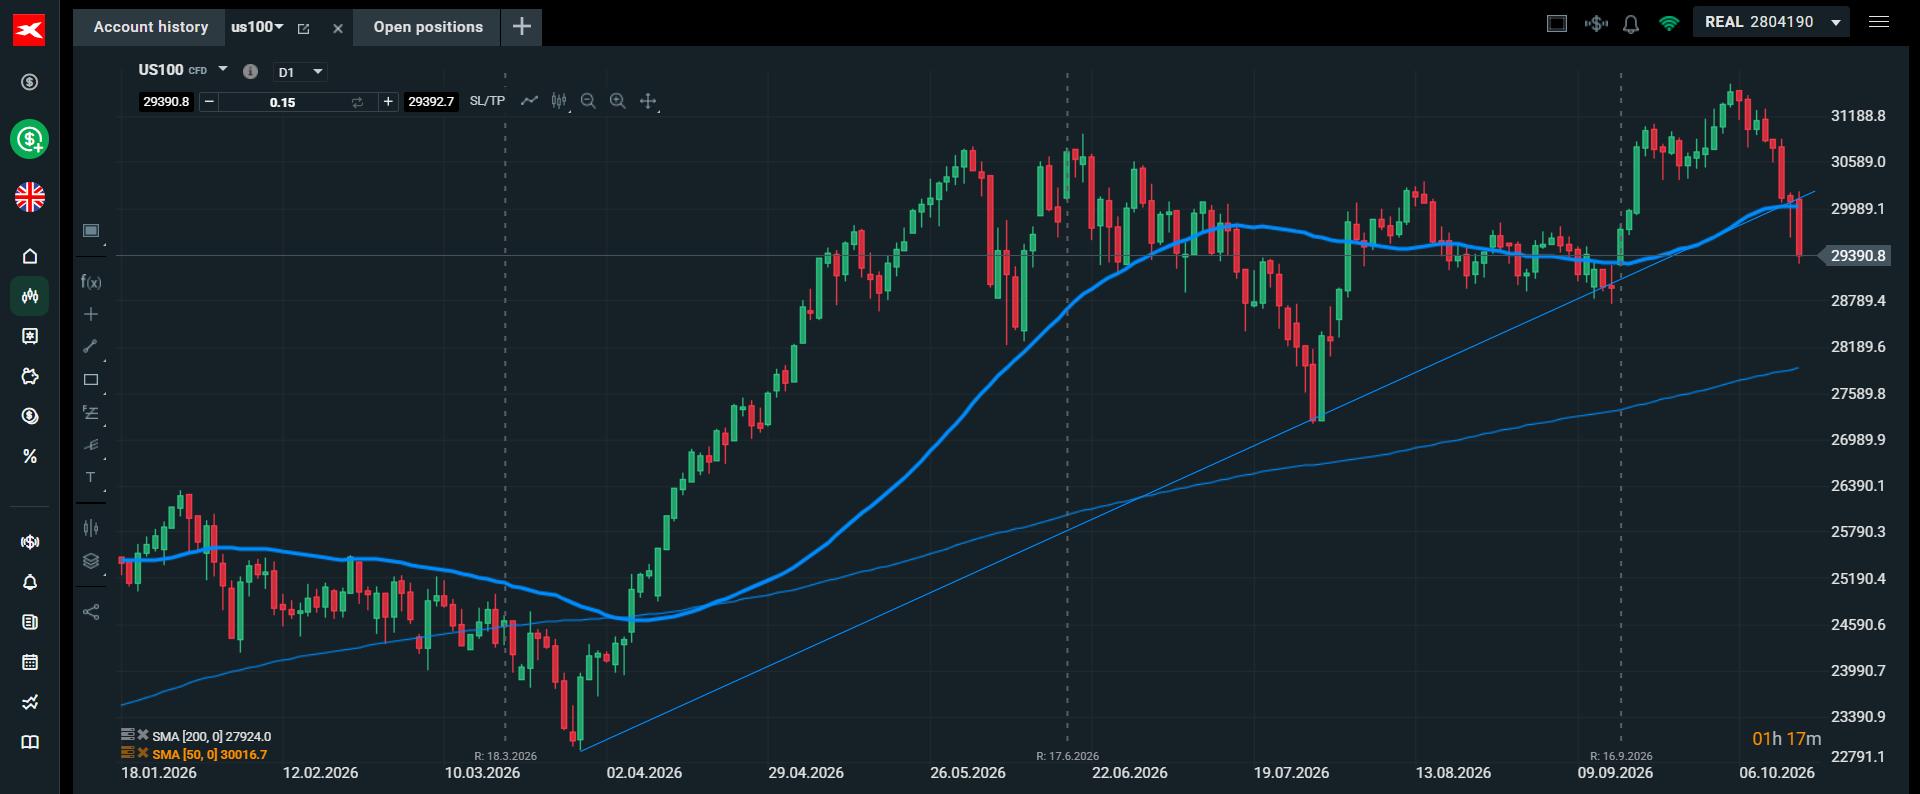
Chart 1: Nasdaq 100 fell through 50-day sma and broke below multi-month trend line during last week’s sell off.
Author

Kathleen Brooks
XTB UK
Kathleen has nearly 15 years’ experience working with some of the leading retail trading and investment companies in the City of London.