Week Ahead on Wall Street (SPY) (QQQ): Volatility remains as hawks feed on bull carcasses
- Facebook Meta Platforms (FB) suffers the biggest market cap loss in history.
- Alphabet (GOOGL) smashes earnings estimates and Amazon (AMZN) reaps Rivian (RIVN) gains.
- Bank of England and ECB set off another round of hawkish price adjustments.
Yet another incredible week of volatility with counterpoint arguments coming from all sides as the week progressed. We got set up nicely from Google earnings early in the week and markets penciled in more good news from Facebook. Facebook Meta Platforms (FB) closed up 5% in anticipation of more solid earnings. When these did not materialize the reaction was severe. The most severe in fact in history as far as we are aware for a US-listed share. About $230 billion was wiped off the value of FB stock on Thursday as it closed 26% lower. The company is betting the house on the metaverse it seems and issued lower forecasts which investors disliked. Amazon (AMZN) then steadied the ship somewhat on Friday as it reported after the bell on Thursday. Amazon beat big excluding the huge profit from its stake in EV start-up Rivian (RIVN). Amazon Web Services drove a lot of growth and Amazon announced a Prime price increase. At the time of writing Amazon's (AMZN) stock is up 15% with two hours left in the week. This has helped the Nasdaq back into positive territory after a volatile week.
On to the macro picture now and hawks rule the skies increasingly after the Bank of England and ECB decisions hit this week. The Bank of England surprised nobody in raising rates 25bps but what did surprise many economists was the narrow 5-4 vote in favour of the 25bps hike. The other 4 members looked for a 50bps hike. This led to an immediate spike in money markets and they have now pencilled in an extra hike this year. The ECB then also surprised no one when it left interest rates on hold but ECB President Christine Lagard was notably more hawkish in her press conference afterward. All this saw the dollar dump hard as it hit a low of 1.1487 versus the euro. This time last week it had a 1.11 handle, nearly 4 big figures in a week is a huge move for this pair.
Oil prices went on a rampage also as the week progressed. While the narrative over Russia and Ukraine appeared to die down or at least stabilise Oil popped to a seven-year high on Friday as strong US employment added to recent speculator demand due to falling US delivery supplies. We should note though that next week is the calendar roll period where speculators likely have to sell the front month and buy the far to maintain long positions. This could put pressure on oil prices in the short term.
American Association of Individual Investors (AAII) Sentiment
The AAII survey shows investors remain highly pessimistic about the stock market going forward for the next 6 to 12 months. Bullish sentiment is at 26.5% which is a small 3% increase on the week. Bearish sentiment has fallen by 9% though but still dominates at 43.7%.
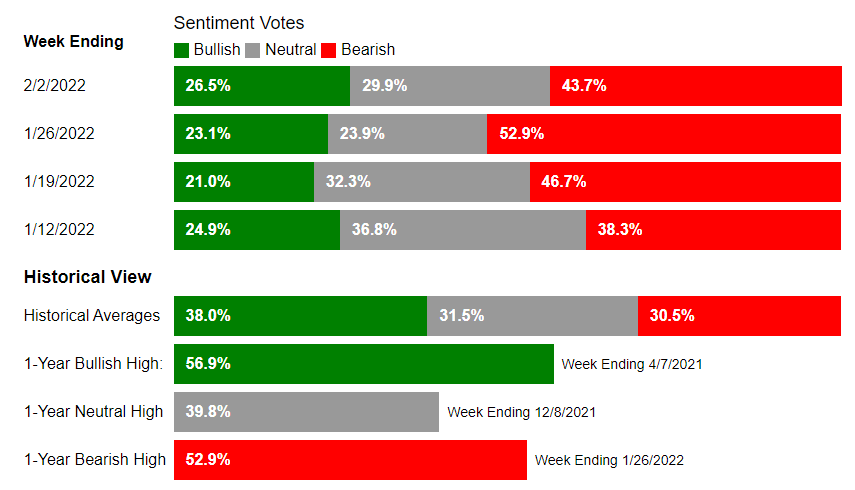
Source: AAII.com
Earnings data
Over halfway through earnings season and it certainly has provided plenty of talking points. We had big banks largely underwhelming us before Apple and Google got the tech sector off to a strong start. Just when markets started gearing up, Facebook smashed them back down only for Amazon to boom. 278 companies from the S&P 500 have now reported according to Refinitiv Lipper Alpha. 78.4% have beaten estimates which is down from last quarter's average of 83.9%. This is still well above historical beat averages. However, the market has clearly not been impressed with the strong earnings numbers. We do not have data for outlook forecasts but the trend of strong earnings not following through in stockmarket performance is worrying. It does feel to us as if forecasts have been slightly disappointing but that is only our viewpoint we have no conclusive data yet to back that up. We do note some guidance figures from Refinitv showing earnings guidance for Q1 2022 has certainly fallen this year compared to last.
Earnings week ahead
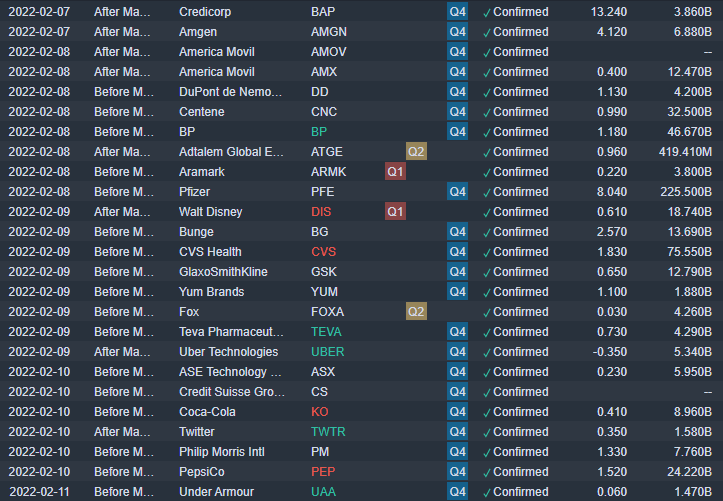
Source: Benzinga Pro
S&P 500 (SPY) technical analysis
$428 remains the huge support. Note next week blackout period ends for some large corporate buybacks. RSI still trending lower and looks to have topped out so could the SPY follow suit? MACD has crossed over but yields are surging again after the employment report. This Friday green may be just position closing. $450 is resistance and looks unlikely to be broken. Opening next week below $450 sets up a fresh test of $428 in our view.
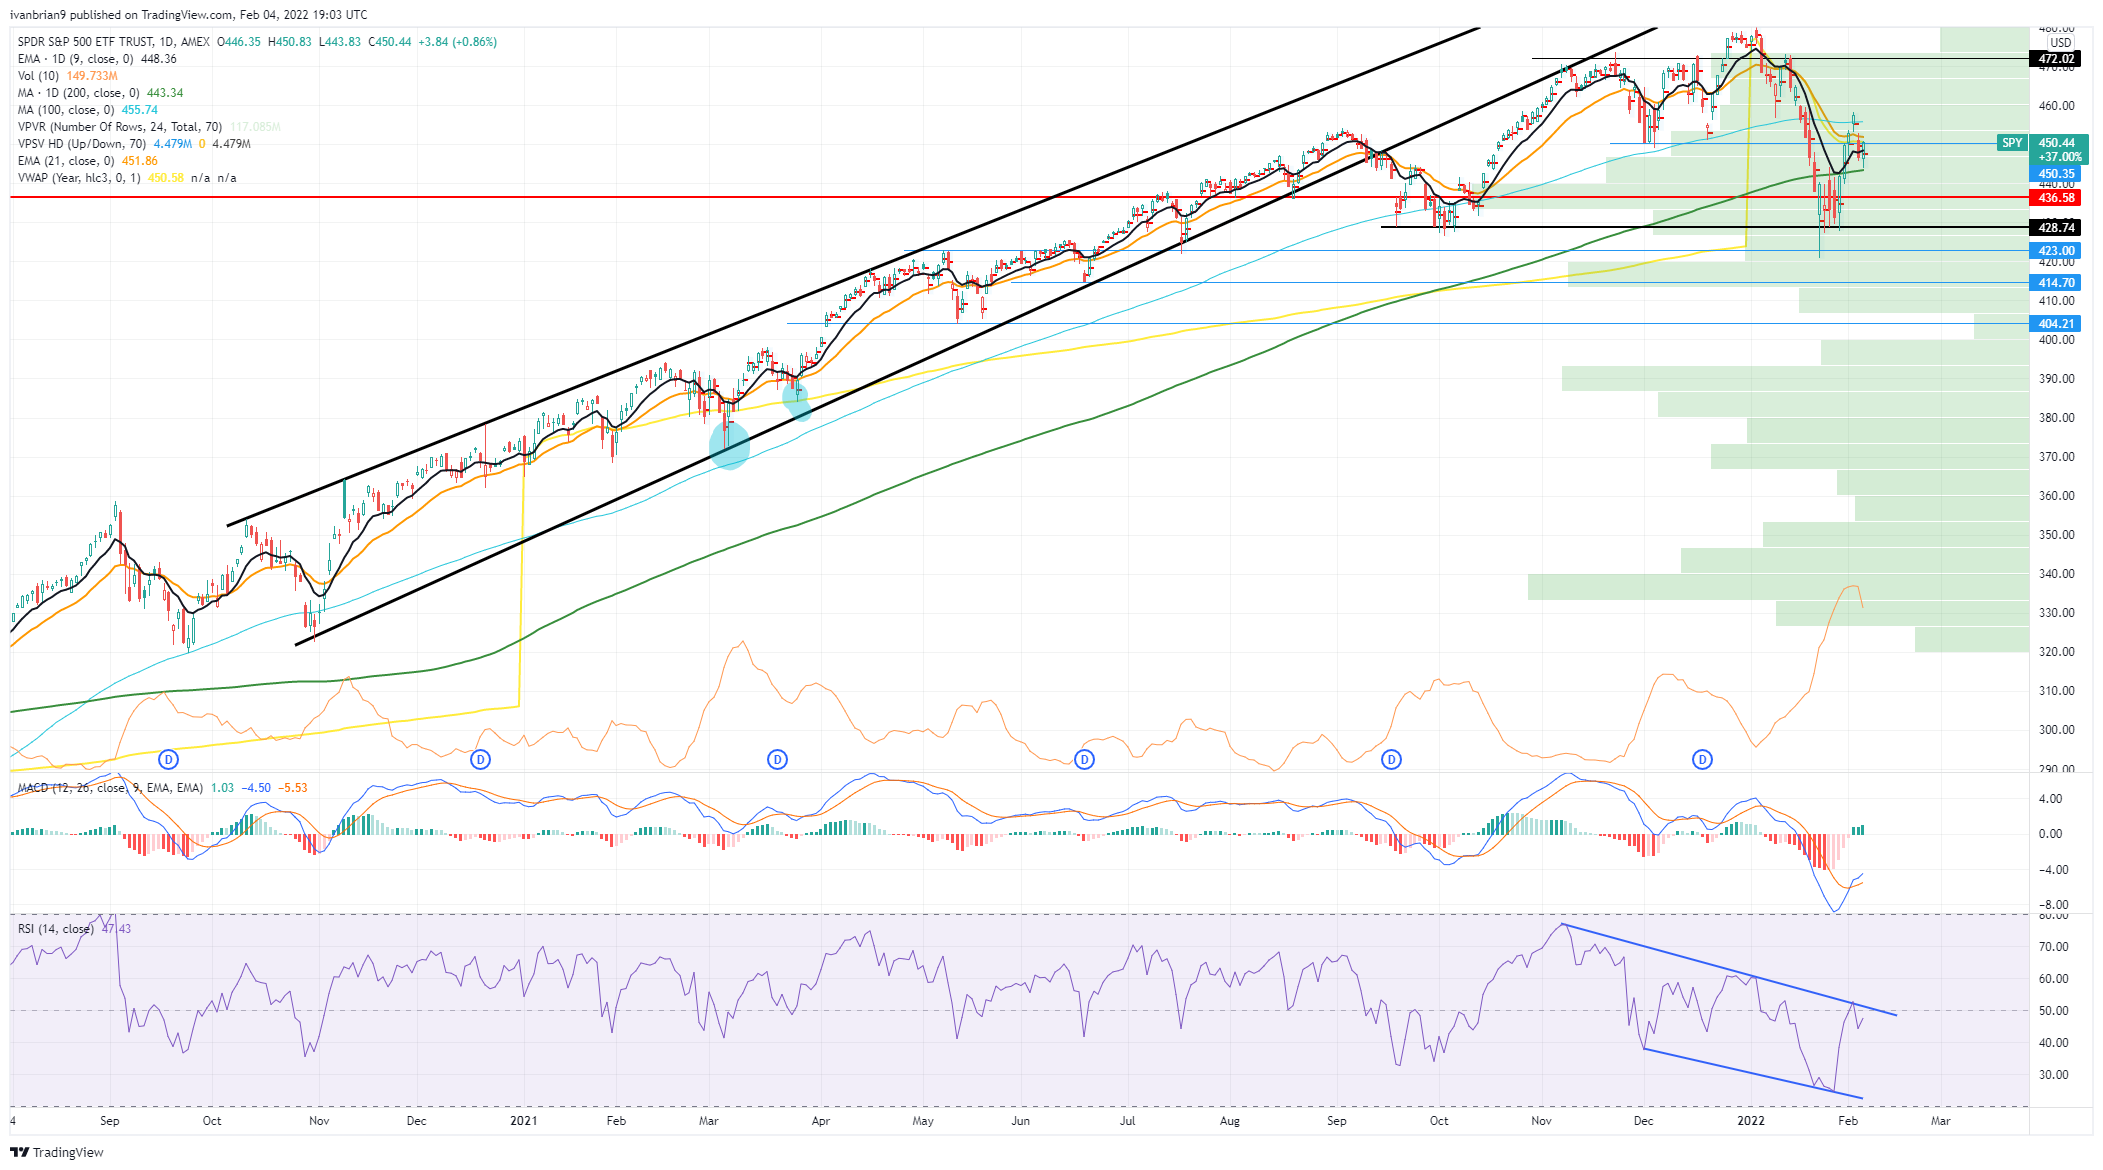
SPY chart, daily
Nasdaq (QQQ) technical analysis
RSI still trending lower but today's prie action has seen some stabilization. The rise in yields after the strong employment report could put more pressure on the sector next week. $350 is the short term pivot and below $342 would be more than likely to break on another test. That will then lead us lower to $316 and $300 as likely supports and targets. The February 2 spike looks like the latest high in the emerging downtrend.
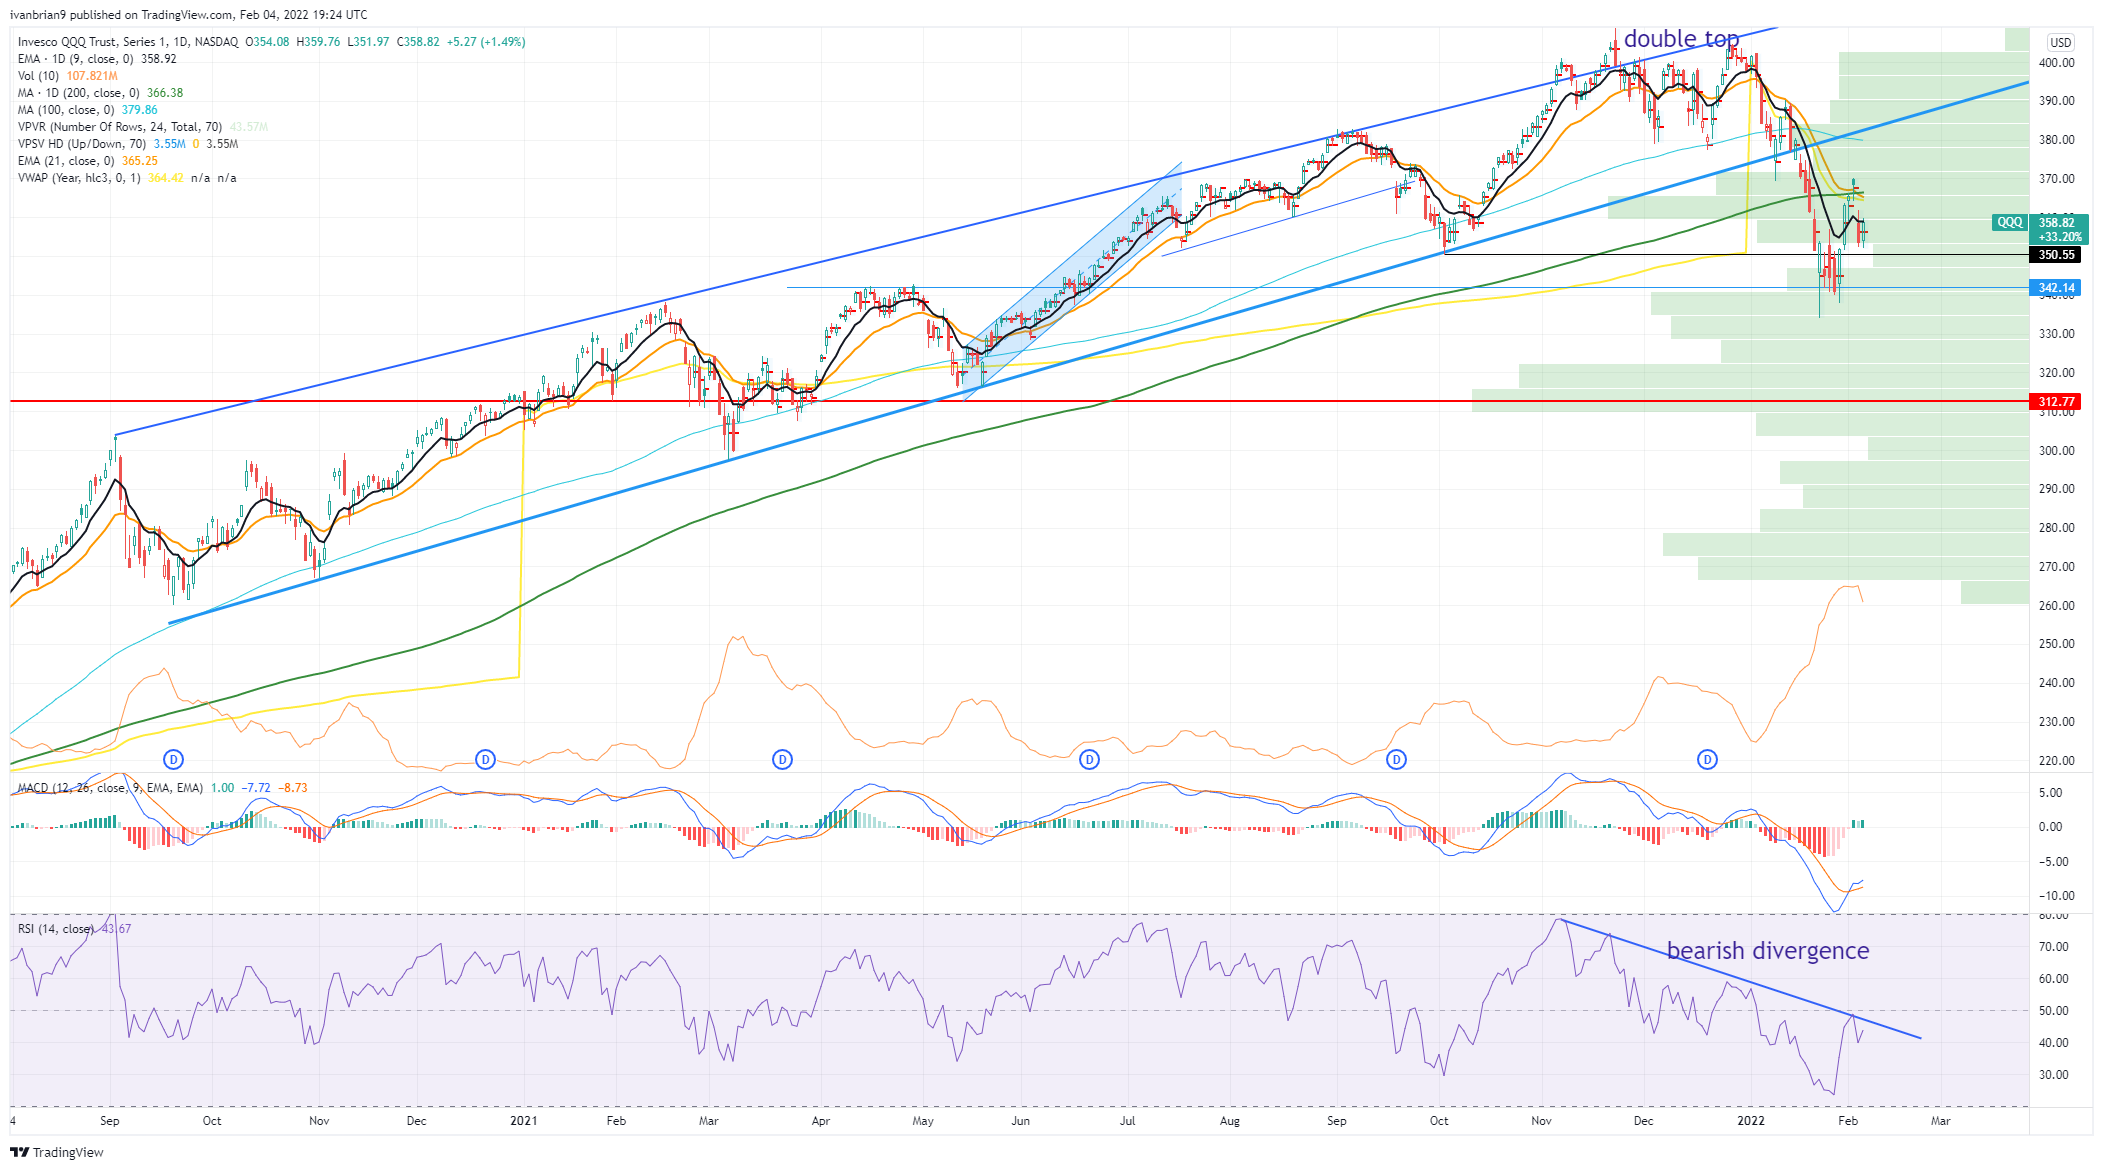
Nasdaq (QQQ) chart, daily
Economic releases
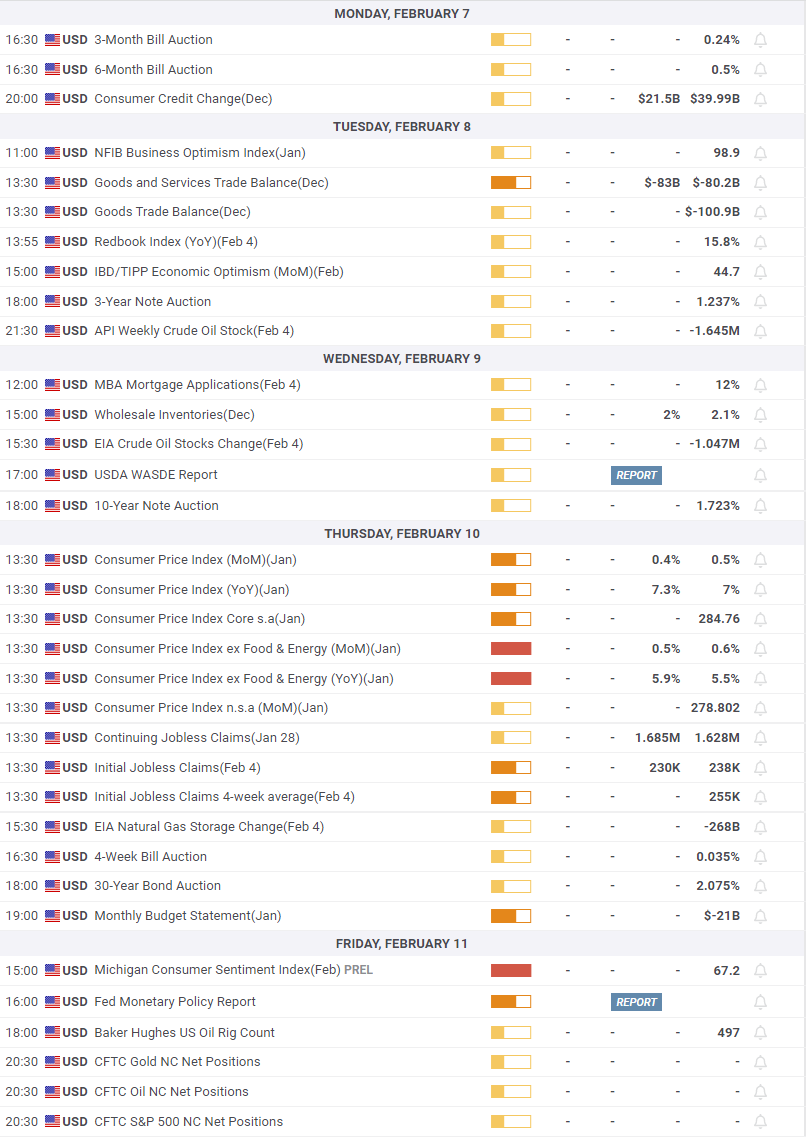
Next week is not too heavy data wise. The obvious highlight is the CPI on Thursday. The risk-reward is skewed to the downside in this release in our view. The market is now increasingly hawkish and money markets have adjusted accordingly. A number higher than expected will not have too much of an effect whereas a surprisingly low number will see a large repricing across money, FX and equity markets.
Author

Ivan Brian
FXStreet
Ivan Brian started his career with AIB Bank in corporate finance and then worked for seven years at Baxter. He started as a macro analyst before becoming Head of Research and then CFO.
















