US Dollar Weekly Forecast: FOMC Minutes and US data return to the fore
- The US Dollar closed its second week in a row of losses.
- Bets for another rate cut by the Fed in December continued to dwindle.
- Republicans and Democrats clinched a deal to end the US shutdown.
The week that was
The US Dollar (USD) could not reverse the ongoing bearish tone this week, prompting the US Dollar Index (DXY) to retreat for the second week in a row. That said, the index further extended its rejection from recent multi-week highs north of the psychological 100.00 barrier set on November 5.
The Greenback’s march south, however, came despite a persistent hawkish narrative from many Fed rate setters, which in turn prompted bets for another quarter-point rate cut in December to shrink further.
The positive news from the US political scenario, which saw both Republicans and Democrats find common ground to end the historic US federal government shutdown, did not help the buck either.
In the US debt market, US Treasury yields traded mostly in a positive mood across the curve, in contrast to the Greenback’s performance.
Powell warns on December cut as FOMC debate deepens
The Fed’s late-October meeting delivered exactly what markets had been bracing for: a quarter-point rate cut, approved by a solid, though not unanimous, 10–2 vote. That move pulled the benchmark rate down to 3.75%–4.00%, broadly in line with expectations but still enough to spark debate inside the central bank.
What caught many by surprise wasn’t the cut itself but the Fed’s decision to quietly restart small-scale Treasury purchases. Officials framed it as a technical step to ease emerging strains in money markets, but the message was clear: liquidity has been tightening more than they’re comfortable with.
At his press conference, Chair Jerome Powell leaned into the uncertainty. He made a point of saying the committee was divided and urged investors not to take a December cut for granted. The tone was noticeably cautious, a reminder that policymakers are still wrestling with conflicting signals: stubborn inflation on one side, a cooling but not collapsing labour market on the other.
Markets, for their part, took Powell at his word but not entirely at face value. Futures pricing now implies nearly 11 basis points of additional easing by year-end and roughly 80 basis points by the end of 2026, lower than traders were expecting just a week earlier.
A rate cut in December loses appeal
Federal Reserve officials spent the week signalling a wide range of views on the policy outlook, underscoring just how divided the central bank remains ahead of its December meeting.
San Francisco Fed President Mary Daly repeatedly said that she believed US monetary policy was in a “good place” for now. She argued that risks to the Fed’s dual mandate were broadly balanced after two rate cuts this year and noted that officials needed to keep an open mind heading into December. Daly suggested policymakers would be watching both inflation, still too sticky for comfort, and signs of further cooling in the labour market before deciding their next step.
St. Louis Fed President Alberto Musalem struck a more cautious tone, saying the Fed should tread carefully with any additional easing. He pointed to inflation still hovering closer to 3% than the 2% target, combined with resilient economic activity and generally accommodative financial conditions. In his view, policy is near neutral, leaving little room for error.
Atlanta Fed President Raphael Bostic, speaking shortly after announcing his plan to retire at the end of February, said he favoured holding rates steady until there was clearly convincing evidence that inflation was on track to return to 2%. He emphasised that the greater risk still lay with price stability rather than the job market.
Fed Governor Stephen Miran took a different angle, reiterating his belief that recent inflation readings are backward-looking and overstated. He argued that easing housing inflation was already doing much of the work to cool price pressures and that policy was now too restrictive as a result.
Boston Fed President Susan Collins, who supported last month’s cut, cautioned that the bar for further near-term easing remained high. She pointed to still-elevated inflation and acknowledged the divisions within the FOMC, divisions Chief Powell himself alluded to when he warned that another cut in December was “far from” guaranteed.
Minneapolis Fed President Neel Kashkari described the economic backdrop as mixed. Inflation around 3% was, in his view, still too high, but he also saw signs that parts of the labour market were weakening. In an interview, he said he did not support the October rate cut given the economy’s resilience and admitted he was undecided about December.
Cleveland Fed President Beth Hammack indicated she was inclined to keep policy in a position that would help bring inflation lower, hinting that she was not keen on another cut, just yet. She and others are weighing whether a follow-up reduction would risk undercutting progress on inflation at a delicate moment.
Rounding out the week, Kansas City Fed President Jeffrey Schmid said his inflation concerns extended well beyond the immediate impact of tariffs. His comments suggested he might dissent again in December if the committee opts to lower borrowing costs, as he did in October.
Taken together, the remarks paint a picture of the Fed wrestling with crosscurrents: inflation that is easing but still sticky, a labour market that is cooling unevenly, and an economy that refuses to lose momentum.
With officials openly split, December’s decision is shaping up to be one of the more contentious meetings in recent memory.
Reopening isn’t the end: Markets grapple with missing data
On Wednesday, President Donald Trump finally signed a new government funding bill, ending the bitter standoff between Republicans and Democrats and ending the longest shutdown in US history.
The shutdown lasted 43 days and stemmed from one key disagreement: Democrats in the Senate refused to approve the funding bill unless it included an extension of healthcare subsidies for low-income Americans. Republicans resisted, and neither party wavered. The result was nearly six weeks of unpaid federal workers, closed or severely limited agencies, and a government running on fumes.
The disruption even spilt into the economic data calendar. The Bureau of Labor Statistics (BLS) was unable to release its October jobs report, and a batch of key inflation figures scheduled for mid-October also had to be delayed.
Karoline Leavitt, the White House Press Secretary, said on Wednesday that those numbers might not show up at all, even though the shutdown is over, because survey teams couldn't get the time-sensitive data they needed.
Leavitt says that the lack of information will "permanently impair" some economic indicators for October 2025, which will leave the Fed "blind" during a crucial time for monetary policy. Without those benchmarks, policymakers lose an important part of the toolkit they rely on to steer interest rates. Businesses, investors, and analysts also lose visibility, creating a rare blind spot in the long run of US economic records.
For now, the new funding bill keeps the government running through the end of January. But the underlying issue, healthcare tax credits under the Affordable Care Act, hasn’t been resolved. If lawmakers can’t reach a compromise, the country could be staring at yet another shutdown early next year.
What’s in store for the US Dollar
While market participants are still guessing which data releases will be available and when, the main focus of attention will be on the publication of the FOMC Minutes on November 19, ahead of key preliminary gauges of business activity from S&P Global PMIs.
Technical landscape
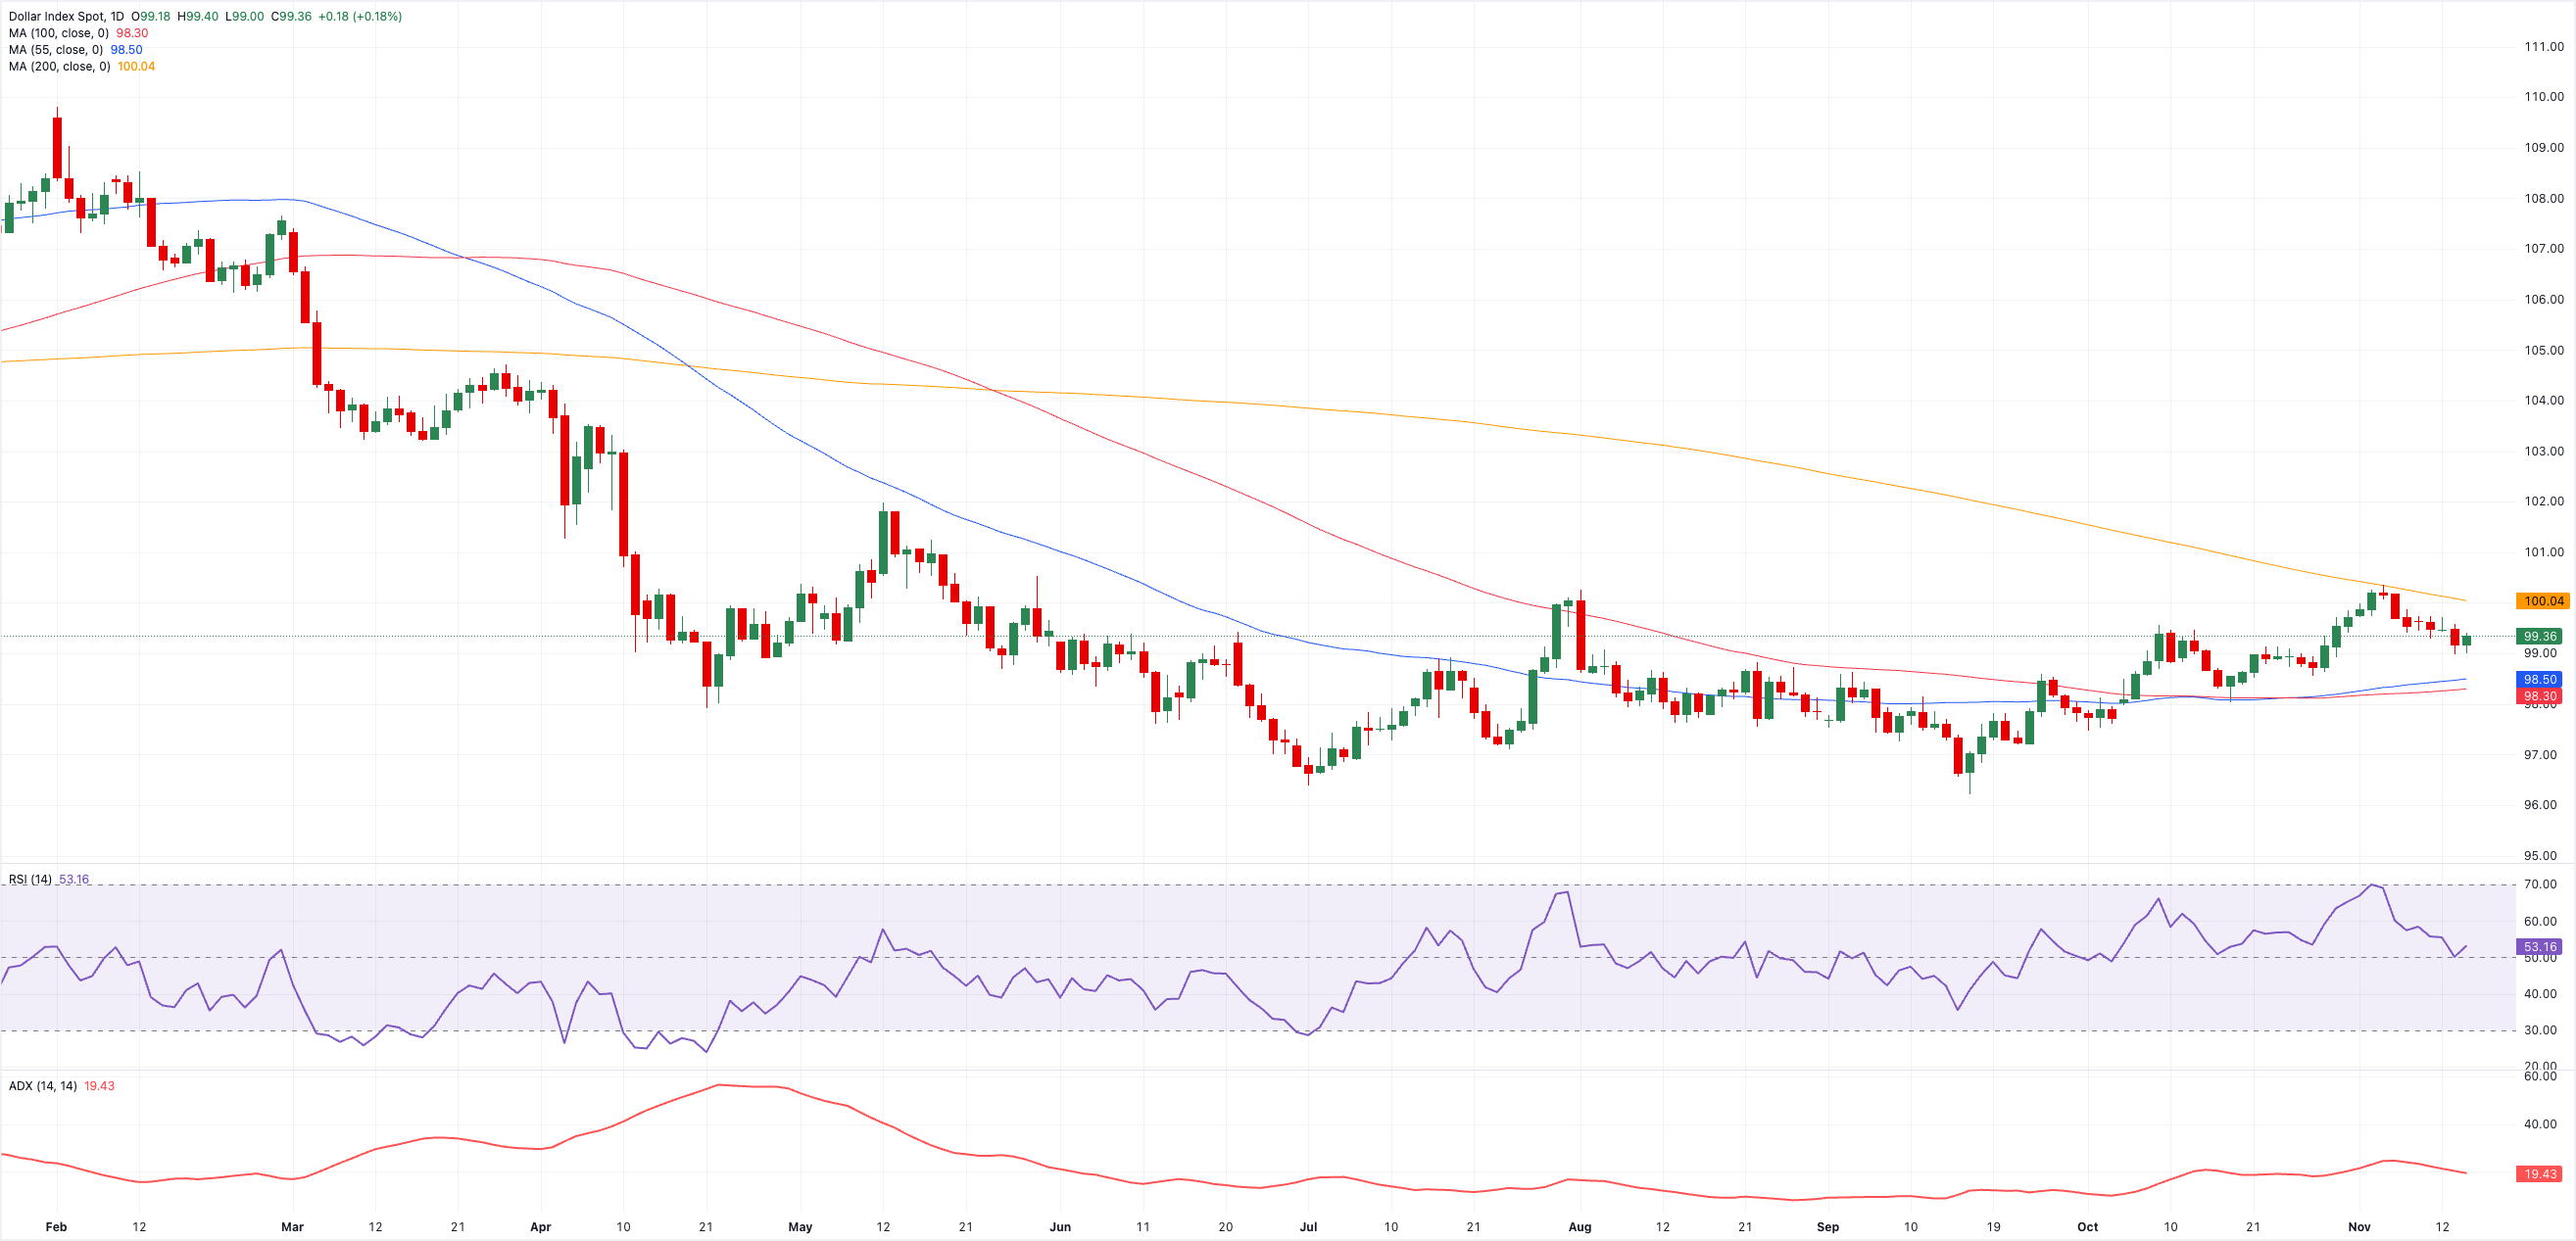
The US Dollar Index (DXY) has remained in a "correction" mode since it surpassed the 100.00 hurdle earlier this month.
The critical 200-day SMA now emerges immediately to the upside at 100.08. Surpassing this region is vital to shift the buck’s outlook to a more constructive one and allow for more convincing advances. That said, the November high at 100.36 (November 5) comes first, seconded by the weekly peak at 100.54 (May 29) and the May top at 101.97 (May 12).
Conversely, the 55-day and 100-day SMAs at 98.48 and 98.28, respectively, should offer transitory contention ahead of the weekly low of 98.03 (October 17). Further south sits the 2025 bottom at 96.21 (September 17) prior to the February 2022 base at 95.13 (February 4) and the 2022 valley at 94.62 (January 14).
In addition, momentum indicators have lost some shine, although they still lean bullish: The Relative Strength Index (RSI) bounces past the 52 level, indicating that further upside is still in the pipeline, while the Average Directional Index (ADX) near 19 suggests a modestly strong trend.
Bottom line
The short-term outlook for the US Dollar has softened over the past couple of weeks, and momentum hasn’t exactly been in its favour. Even so, the currency isn’t without support. A handful of Fed officials continue to strike a hawkish tone, and that stance should help limit how far the buck can fall in the near term.
The bigger issue now is the fallout from the record-breaking government shutdown. On paper, US fundamentals still look broadly aligned, but the missing data releases have left investors squinting through a foggy macro picture. With key reports delayed, or potentially lost altogether, the backlog could end up carrying far more weight than usual once it finally hits, potentially nudging expectations for what the Fed does over the next few months.
For the moment, policymakers say they’re mostly focused on the labour market. But inflation hasn’t gone away; it’s still running hotter than the Fed would like. If price pressures refuse to cool, officials could be forced to pivot back toward inflation control faster than expected. And that would almost certainly translate into a more cautious Fed, regardless of how President Trump might feel about it.
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.

















