US CPI December Preview: Markets take the Fed's cue and look away
- Annual consumer inflation expected to rise in December, core rate stable.
- Weak Retail Sales in November, December to undermine pricing power.
- CPI a secondary statistic after Fed adoption of inflation averaging.
- Interest rate policy is divorced from consumer prices.

Inflation in the US has been stable for five months since prices recovered from the lockdown collapse in April and May. Prices are expected to rise slightly in December but is there no discernible pressure to return to their pre-pandemic levels.
The Consumer Price Index (CPI) is forecast to rise 0.4% on the month and 1.3% annually up from 0.2% and 1.2% in November. The Core Consumer Price Index is projected to climb 0.1% and 1.6% in December after 0.2% and 1.6% in November.
Pandemic price collapse
Annual price changes fell from 2.5% in January to 0.3% in April and 0.1% in May as retailers desperately cut prices in effort to move goods in a shuttered economy. Core prices dropped from 2.4% in February to 1.2% in May and June.
From July through November CPI has averaged 1.22%, just under half the January rate. Core CPI averaged 1.58% in the same period, two-thirds of the February rate.
CPI
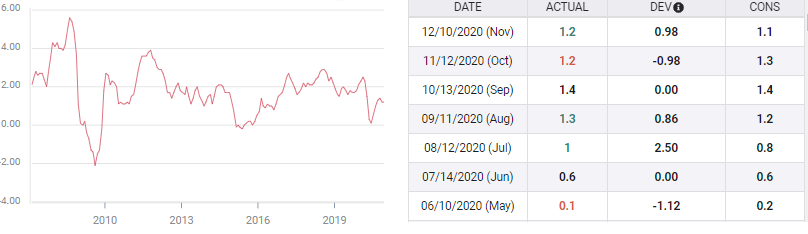
Both indexes have declined slightly since reaching their respective top, 1.7% in August and September for core CPI and 1.4% in September for CPI.
Retail Sales
Retail Sales recovered smartly from the 22.9% plunge in the lockdown months of March and April adding 29.7% from May through September. Since then however they have slipped 0.1% in October and 1.1% in November as payrolls dropped by more than half to to 245,000. Sales are expected to be flat when December's figures are reported this Friday.
Retail Sales
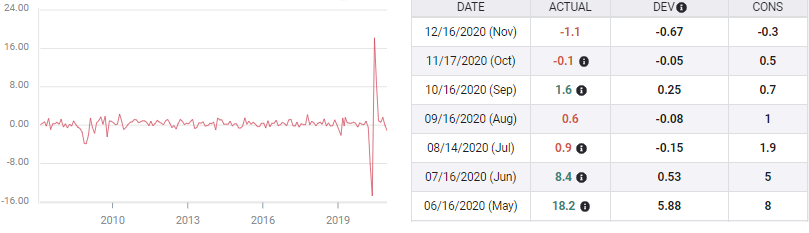
This level of consumption will be unable to restore any measure of pricing power to retailers and manufacturers. One lesson of the financial crisis recession and quantitative easing is that no amount of liquidity will produce price gains when demand is weak.
Federal Reserve
The Fed's move to an inflation averaging model for interest rate policy recognizes what has been unofficially true since the financial crisis, the labor market and economic growth take precedence over price changes.
Under the new policy inflation can range above the ostensible 2% target for an indeterminate time before the governors will entertain price concerns.
Conclusion and markets
The combination of weak price increases and the Fed's new inflation averaging outlook has removed CPI, Core CPI and its Personal Consumption Price Index (PCE) counterparts from market consideration.
If the Fed can officially countenance inflation over its 2% target for a considerable period then no foreseeable monthly result will be of interest to markets.
Author

Joseph Trevisani
FXStreet
Joseph Trevisani began his thirty-year career in the financial markets at Credit Suisse in New York and Singapore where he worked for 12 years as an interbank currency trader and trading desk manager.

















