UK GDP Preview: Early confirmation of BOE’s recession forecast
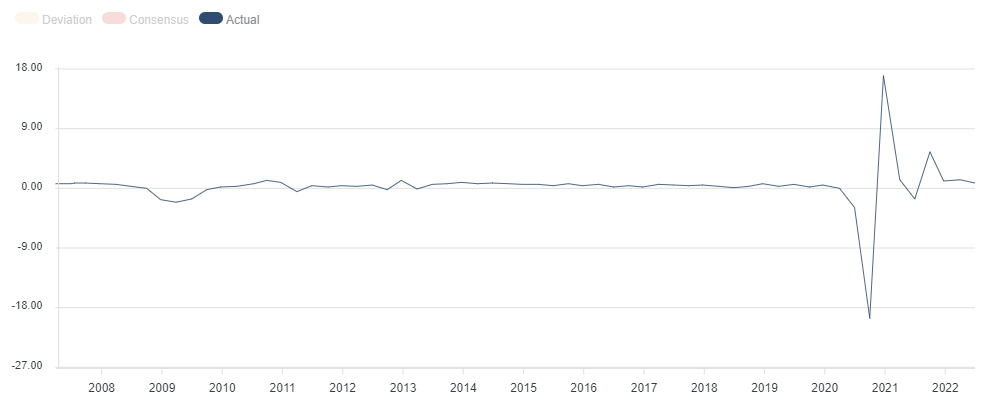
- The British economy is seen contracting -0.2% in Q2 2022 vs. +0.8% previous.
- The BOE anticipates a five-quarter recession beginning in Q4 2022.
- The pound remains vulnerable amid looming recessionary fears.

The Bank of England (BOE) warned last week that the UK economy will enter its longest recession since the global financial crisis (GFC) in the fourth quarter of 2022. However, the second quarter GDP is likely to show the worst economic downturn since the nation was in a coronavirus lockdown at the start of 2021.
The second quarter GDP print, due to be published on Friday at 06:00 GMT, could see a 0.2% contraction in the UK economy. On an annualized basis, the UK GDP is likely to have expanded 2.8% in Q2, down sharply from the 8.7% reported in the previous quarter. The June MoM GDP is seen shrinking by -1.3%.
In the first three months of 2022, the UK economy expanded by 0.8%. The bulk of the quarterly growth seen in the first quarter was recorded in January, as the Russia-Ukraine war ensued in the following months and weighed negatively on national output.
Source: FXstreet
BOE and the R-word
The second quarter GDP contraction could be mainly attributed to a very weak level of activity in June, in the wake of the holiday break to celebrate the Queen’s jubilee. Additionally, rampant inflation and deepening cost-of-living crisis in the UK is also having a significant impact on the economy.
In the last months, the Organisation for Economic Co-operation and Development (OECD) and the International Monetary Fund (IMF) projected that the UK economy would slow markedly in the second half of this year and throughout 2023.
And now with BOE Governor Andrew Bailey brutally honest about the dire economic outlook alongside the deepening energy crisis in Europe and the UK, the negative quarterly GDP print will come as no surprise.
Meanwhile, the central bank remains committed to fighting inflation, which they now see peaking above 13% by October. Therefore, the BOE will continue with the interest rate hikes further despite the impending recession, as it prioritizes the inflation fight over economic growth.
The size of potential BOE rate hikes, however, will depend on the economic situation evolving over the coming months, as surging energy costs hurt households. According to the latest reports, the UK government is preparing for the possibility of energy blackouts in the forthcoming winter. The household's annual energy bills are projected to rise to over £4000 in the new year.
More so, the UK political uncertainty remains in play ahead of the election on September 5, with Liz Truss, the favorite to succeed Boris Johnson, claiming that a recession isn’t inevitable. Truss pushed through her aggressive tax-cutting agenda.
Industry experts believe that Truss’ proposed £39 billion ($47 billion) of tax giveaways may reduce the depth of the slump expected by the BOE but still leave the economy in contraction.
Trading GBP/USD on the UK GDP
GBP/USD is reversing the soft US inflation data-led upswing, as investors turn cautious ahead of Friday’s UK GDP showdown. Risk sentiment also remains tepid amid brewing US-Sino trade tensions and rising China’s covid cases.
The pound appears vulnerable as the UK’s economic outlook remains gloomy. A quarterly contraction of 0.2% or higher could rekindle GBP/USD’s downtrend towards 1.2050-1.2000.
Should the GDP rate show an unexpected expansion, the currency pair could resume its post-US CPI upbeat momentum. However, bulls need to find acceptance above the 1.2300 barrier to kickstart a fresh uptrend.
Author

Dhwani Mehta
FXStreet
Residing in Mumbai (India), Dhwani is a Senior Analyst and Manager of the Asian session at FXStreet. She has over 10 years of experience in analyzing and covering the global financial markets, with specialization in Forex and commodities markets.

















