Political and fiscal uncertainty weighs on the EUR
USD remains strong EUR weakens
The USD remained strong despite September’s US employment report coming in weaker than expected. The Fed’s September meeting minutes on Wednesday could be the next test for USD and a possibly hawkish tone could support USD. Also, the EUR is weakening in the FX market, given the worries for France’s fiscal outlook and political unrest, while Spain is calling for a snap election and Italian bonds are being sold off.
US equities remain mixed
US equities edged higher on Friday, yet the tendencies seem to remain mixed as the index seem to follow different directions. Overall, the weak September US employment data tended to ease market expectations for the Fed to tighten its monetary policy, lifting US equities slightly. We consider the tech sector as still being the stock market barometer for now and a possible lifting of the market sentiment could lift US equities.
Oil prices continue to oscillate
Oil prices edged lower on Friday and during today’s Asian session, yet seem to remain within a range. Fundamentally the increase of oil flows out of the Middle East and market expectations for G7 to release 100 million barrels, tended to weigh on oil prices. Yet the worries for a possible flare up of tensions in the region tend to keep the losses contained and a substantial escalation could lift oil prices.
Other highlights for today
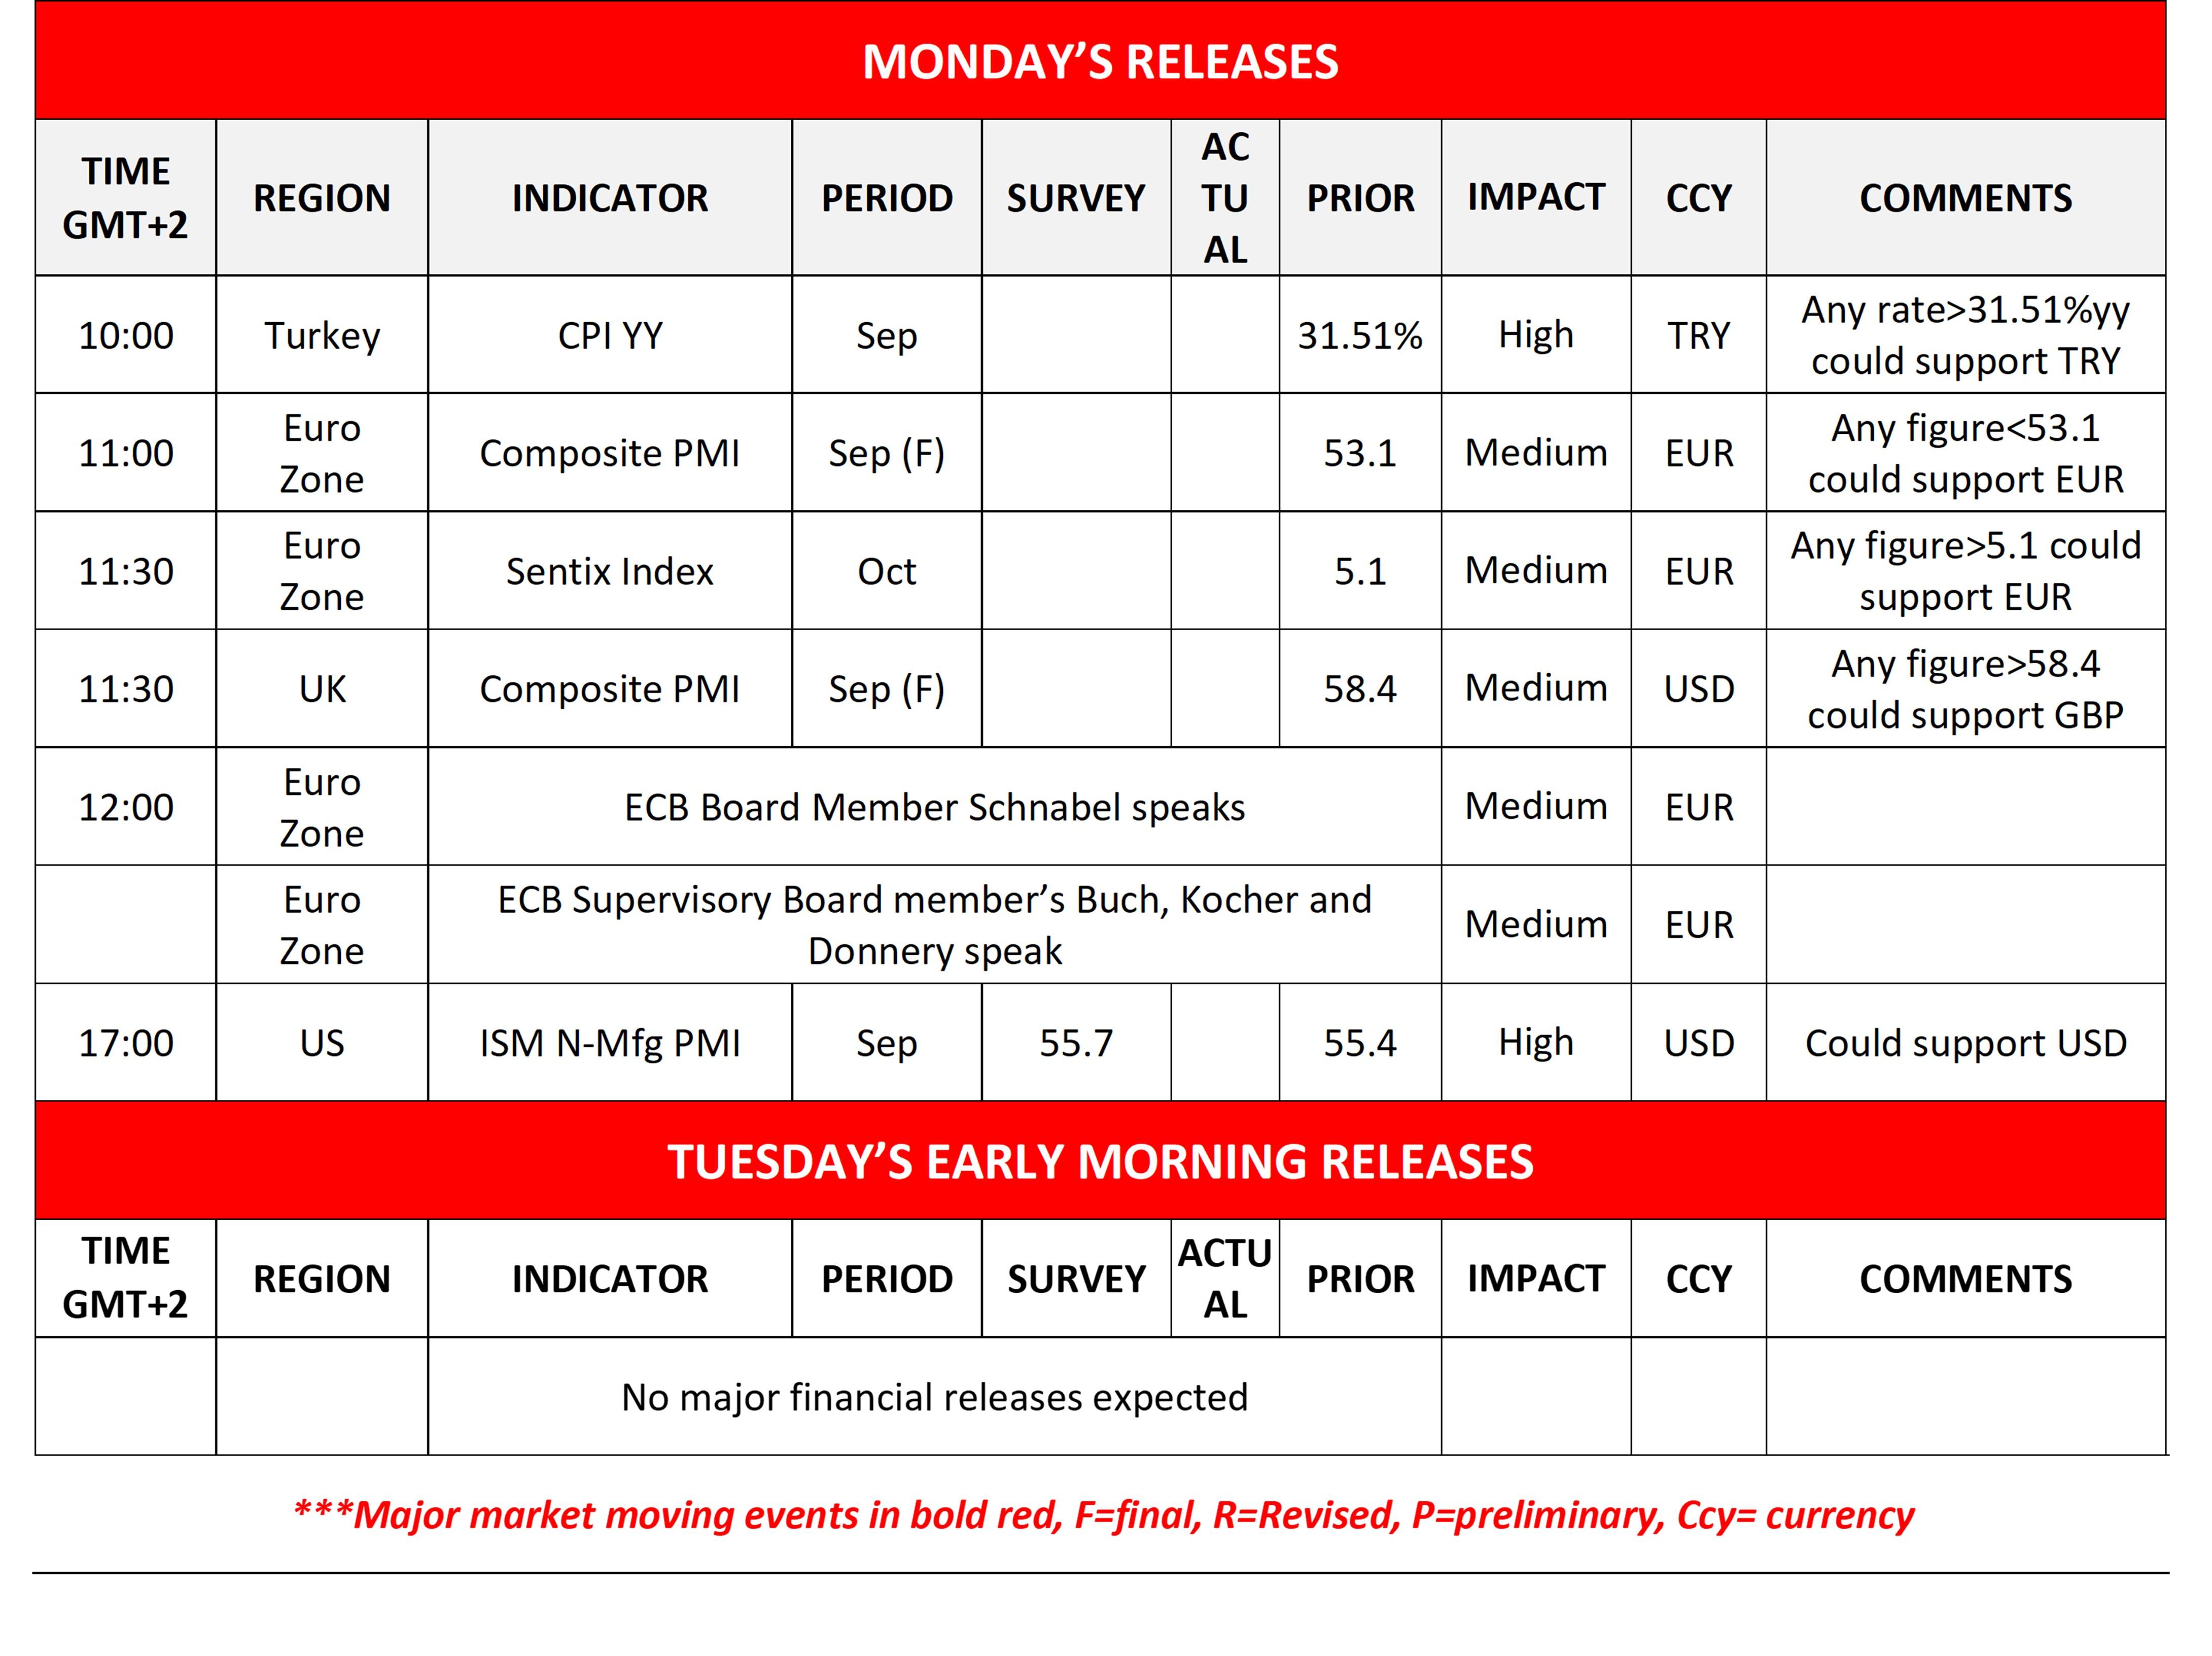
Today we get Turkey’s CPI rates for September, Euro Zone’s and the UK’s final composite and services PMI figures for September. Euro Zone’s Sentix index for October and the US ISM non-manufacturing PMI figure for September. On a monetary level we note that ECB’s Schnabel, Buch, Kocher and Donnery speak.
As for the rest of the week
On Tuesday we get Germany’s industrial orders for August, the Czech Republic’s CPI rates for September and Canada’s trade data for August. On Wednesday we get Germany’s industrial output for August, Sweden’s CPI Rates for September and the Fed releases the minutes of the September meeting. On Thursday we get Japan’s current account balance for August and the weekly US initial jobless claims figure. On Friday, we get Sweden’s GDP rate for August, Norway’s CPI rates for September, Canada’s employment data for the same month and from the US the preliminary UoM consumer sentiment for October.
Charts to keep an eye out
EUR/USD continued to move lower and in today’s Asian session broke the 1.1210 (R1) resistance line, now turned to support. We maintain a bearish outlook for the pair and intend to keep it as long as the downward trendline continues to guide it. Yet the pair seems to be in oversold territory given that the RSI indicator has breached below the reading of 30, thus we issue warning for a possible correction higher. Should the bears continue to lead EUR/USD we may see it aiming if not breaching the 1.1065 (S1) support line. Should the bulls take over, EUR/USD could break the 1.1210 (R1) resistance line, continue to break also the downward trendline guiding it, signalling an interruption of the pair’s downward motion and continue higher aiming if not reaching the 1.1350 (R2) resistance level.
WTI’s price edged lower on Friday and during today’s Asian session, yet its price action is still within the boundaries set by the R1 and the S1. We maintain a bias for the sideways motion of WTI’s price to continue for now, given also that the RSI indicator remains near the reading of 50, implying a rather indecisive market. Should the bears take control over WTI, we may see it breaking the 87.55 (S1) and start aiming for the 82.00 (S2) support level. Should the bulls take over, WTI’s price, may break the 94.30 (R1) resistance line and start aiming for the 101.00 (R2) resistance level.
EUR/USD daily chart
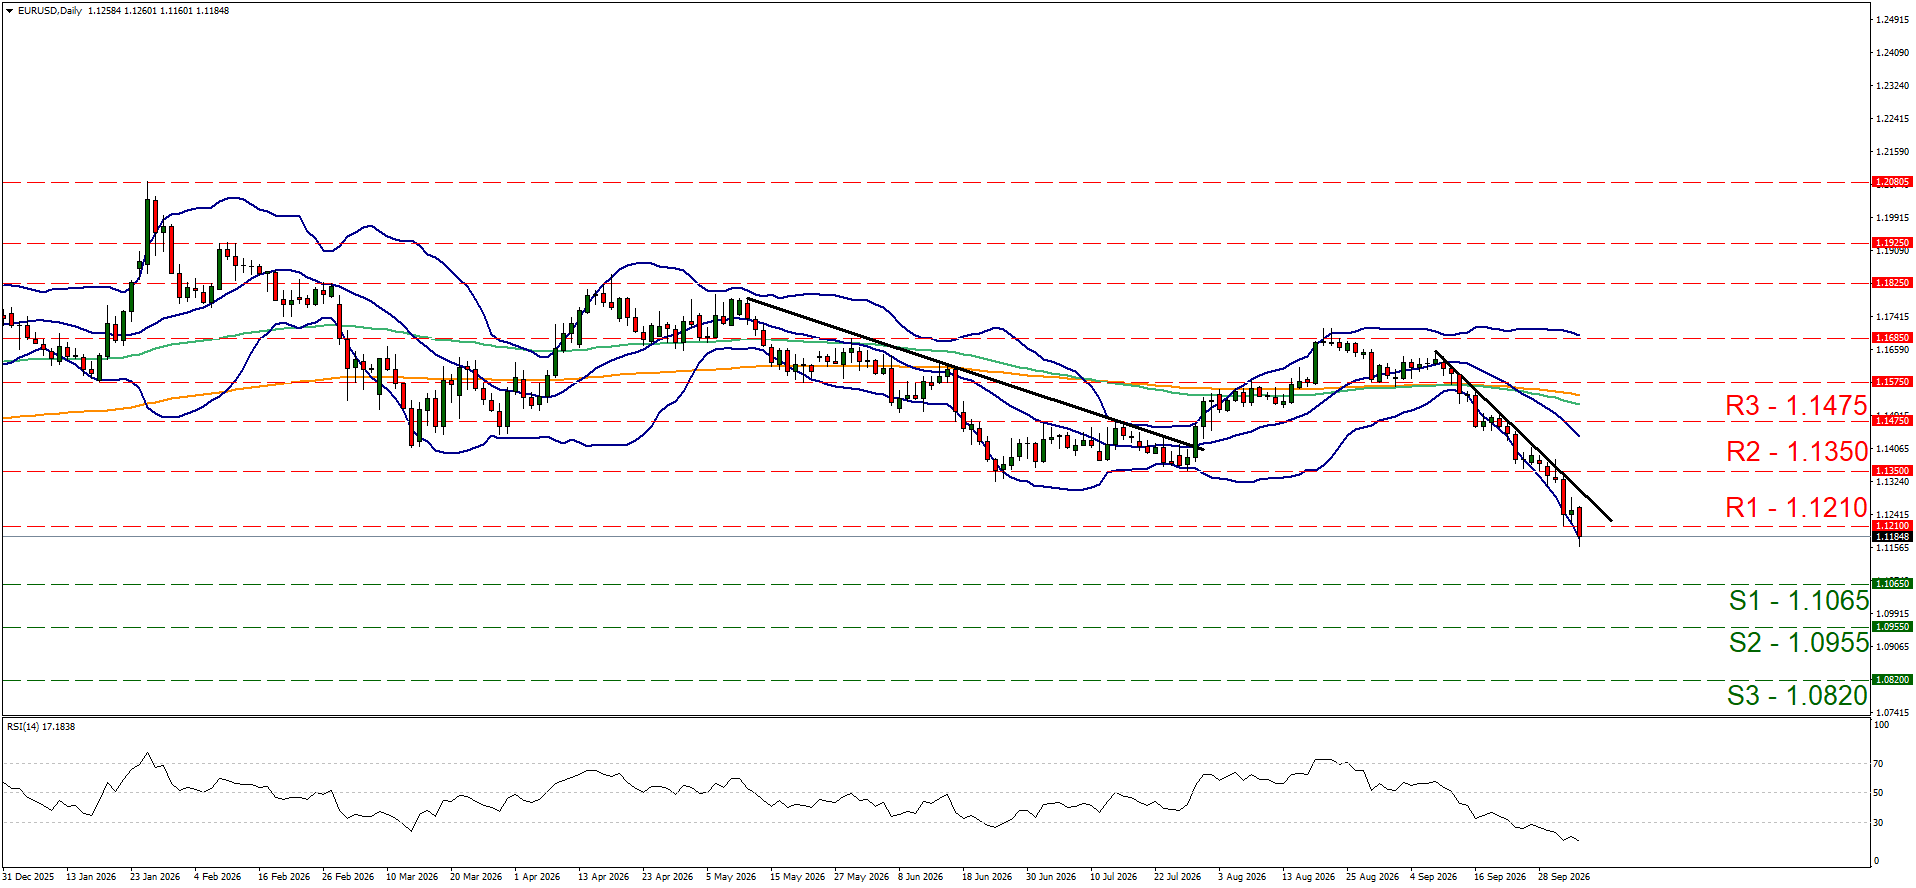
- Support: 1.1065 (S1), 1.0955 (S2), 1.0820 (S3).
- Resistance: 1.1210 (R1), 1.1350 (R2), 1.1475 (R3).
WTI daily chart
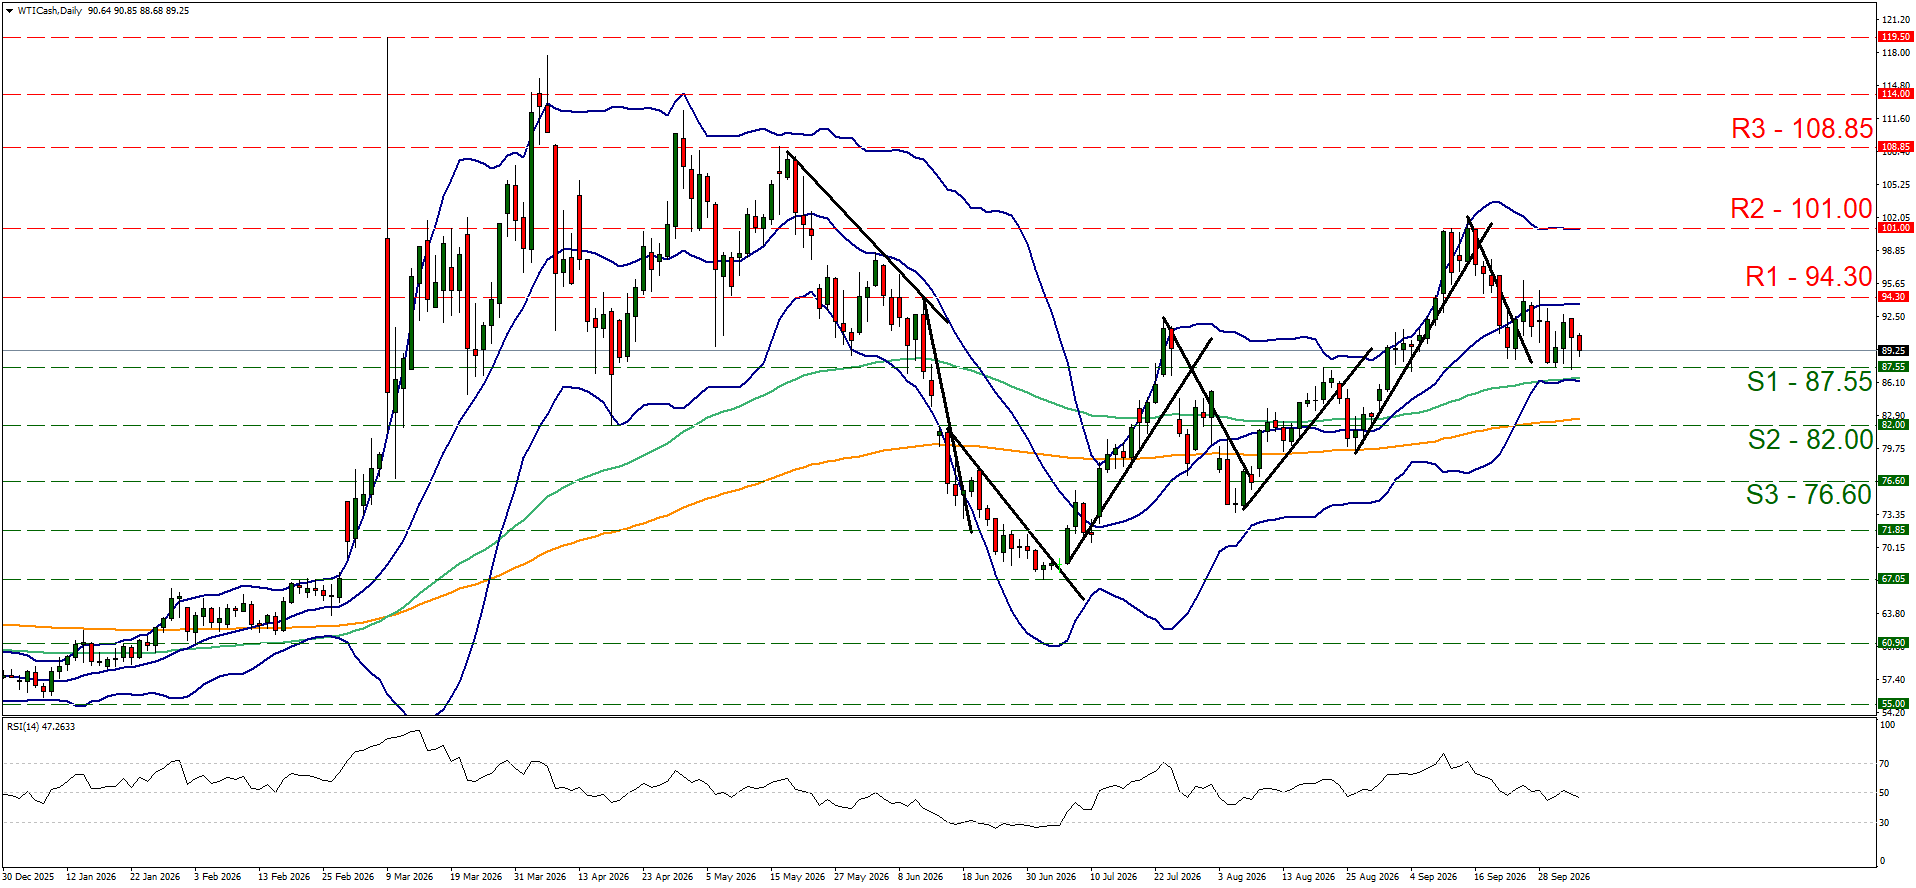
- Support: 87.55 (S1), 82.00 (S2), 76.60 (S3).
- Resistance: 94.30 (R1), 101.00 (R2), 108.85 (R3).
Author

Peter Iosif, ACA, MBA
IronFX
Mr. Iosif joined IronFX in 2017 as part of the sales force. His high level of competence and expertise enabled him to climb up the company ladder quickly and move to the IronFX Strategy team as a Research Analyst. Mr.

















