NFP preview: Complex data release will determine if Fed was right to cut rates
The long wait is over, and the Bureau of Labor Statistics in the US will release nonfarm payrolls reports for both November and October at 1330 GMT on Tuesday. The overall NFP figure for October is expected to be -10k, however, it is expected to be influenced by a massive 130k drop in federal department workers. This is unlikely to have been caused by the federal government shutdown and instead was driven by federal government workers who took the deferred resignation option offered by DOGE earlier in the year.
Broad range in expectations could trigger volatility
The market expects payrolls to ‘bounce’ back in November, and the median estimate of economists is for a 50k increase in payrolls. However, some analysts are expecting a much higher number and the range of economist estimates is broad, with 127k on the upside and -20k on the downside. This highlights how the government shutdown, combined with DOGE cuts impacting federal workers could distort this release.
Temporary increase in unemployment rate expected
The quality of this data may be an issue, as there will be no unemployment report for October, and the data that will be used for the November unemployment rate was collected in the last week of the government shutdown, so furloughed workers may be included as unemployed. The unemployment rate could rise to 4.6% or 4.7% in November, however, it may then retreat back towards 4.4%, the September rate, or 4.5%, in December and January.
US labour market at a crossroads
So, while this report will help shed some light on the health of the US labour market, it is not going to provide the full picture. Looking at other labour market indicators, including jobless claims and the ADP private sector report, the US labour market continues to look weak. Initial jobless claims have trended higher, and although job openings have risen in recent months, the hiring rate has stagnated, with companies in multiple sectors not hiring or firing staff in the current environment. Ahead of this reading, the US jobs market is at a crossroads. Will jobs growth continue to moderate, or will expectations of a resurgent economy in 2026 see a rebound?
Due to technical issues with this data, the market may discount the October payrolls report and the November unemployment rate, and instead the November payrolls report could drive the market reaction.
Dollar on the backfoot
Ahead of this reading, the dollar is mixed, but it has weakened in recent days. The Dollar index is below the 200-day sma and is close to the 98.00 level. Due to the complexity of this data release, we think that this report has the potential to trigger excess market volatility. Equities have also had a mixed performance in recent days, as the AI trade continues to come under pressure. However, on Monday, US and European stocks jumped in a broad advance, as upgrades to the 2026 US economic outlook boosted the market mood.
A strong economy is likely to foster a strong labour market, thus, if the economy is reaccelerating, we would expect to see a stronger than expected payrolls reading for November, with further gains expected in December. This report will also have a big impact on expectations for Fed rate cuts next year. Currently, the market is expecting another two cuts by September next year, however, the Fed only expects one cut. If we get a stronger-than-expected payrolls reading for last month, then market expectations could fall in line with the Fed. If this happens, the dollar index could move back towards the 200-day sma at 99.30, and cyclical stocks could come under pressure. It may also boost the gold price back towards October’s record high, as it could suggest that the Fed has cut interest rates too far too fast, with 75bps of cuts since September.
The Gold price could rise back to record highs if we get a stronger than expected payrolls reading for November
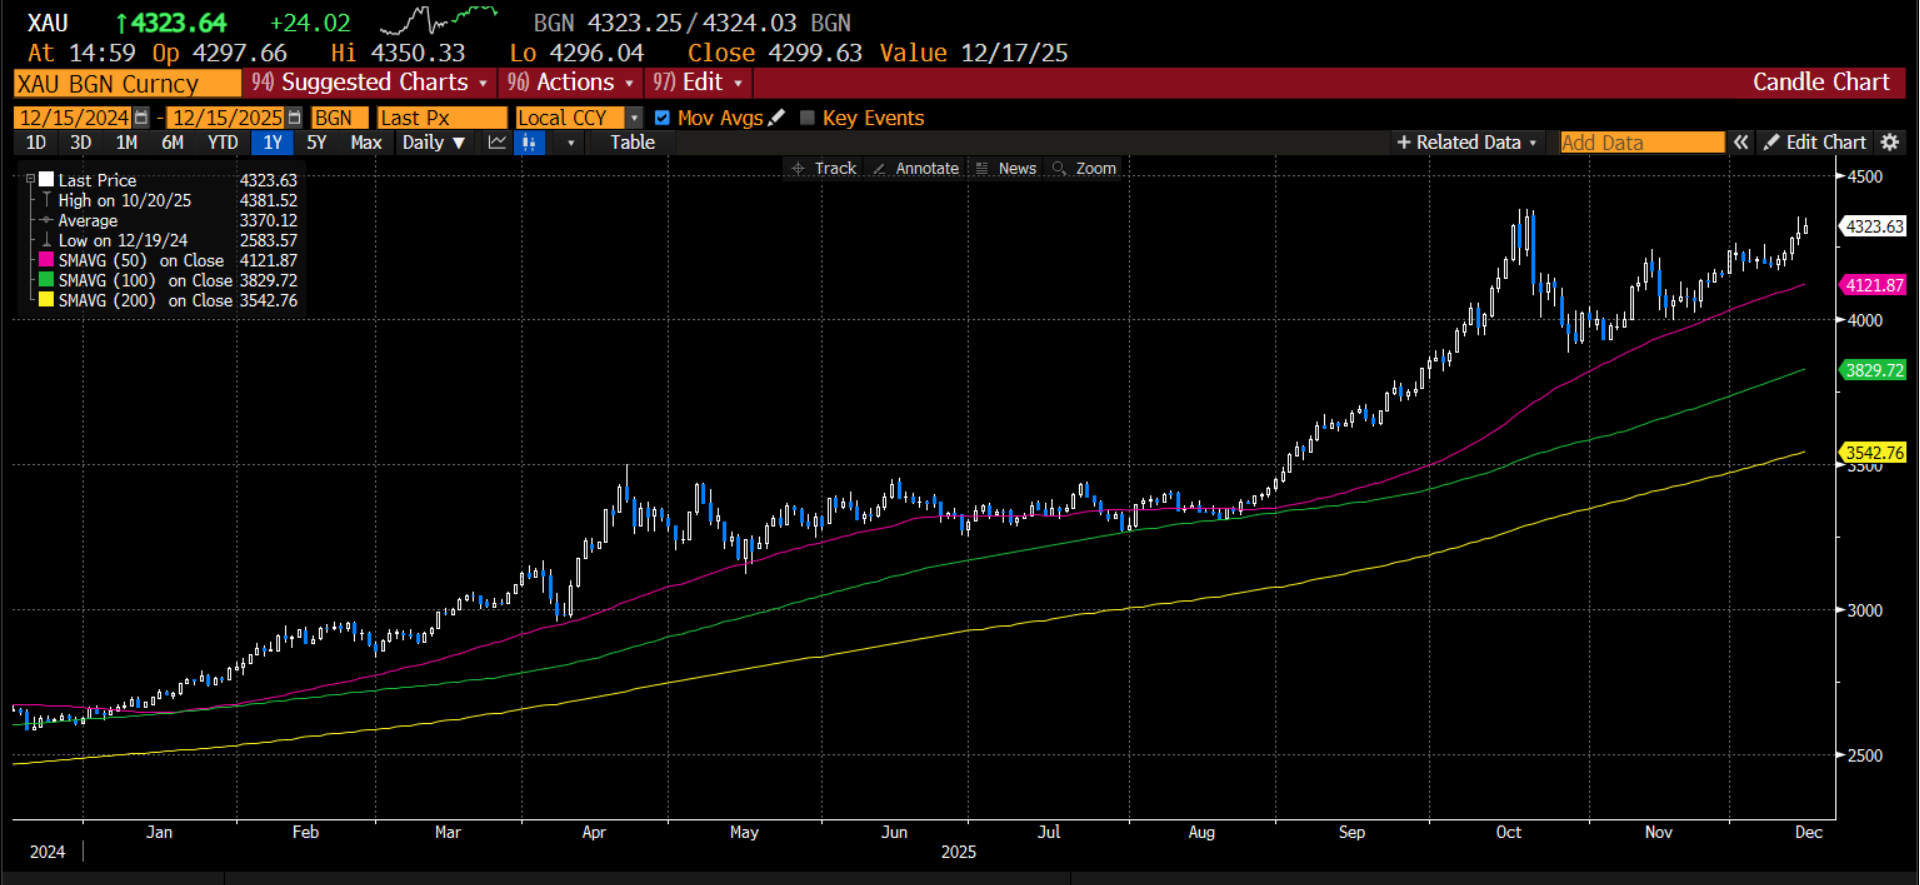
Source: XTB and Bloomberg
Author

Kathleen Brooks
XTB UK
Kathleen has nearly 15 years’ experience working with some of the leading retail trading and investment companies in the City of London.