Kevin Warsh takes the Fed helm: What it means for the US Dollar
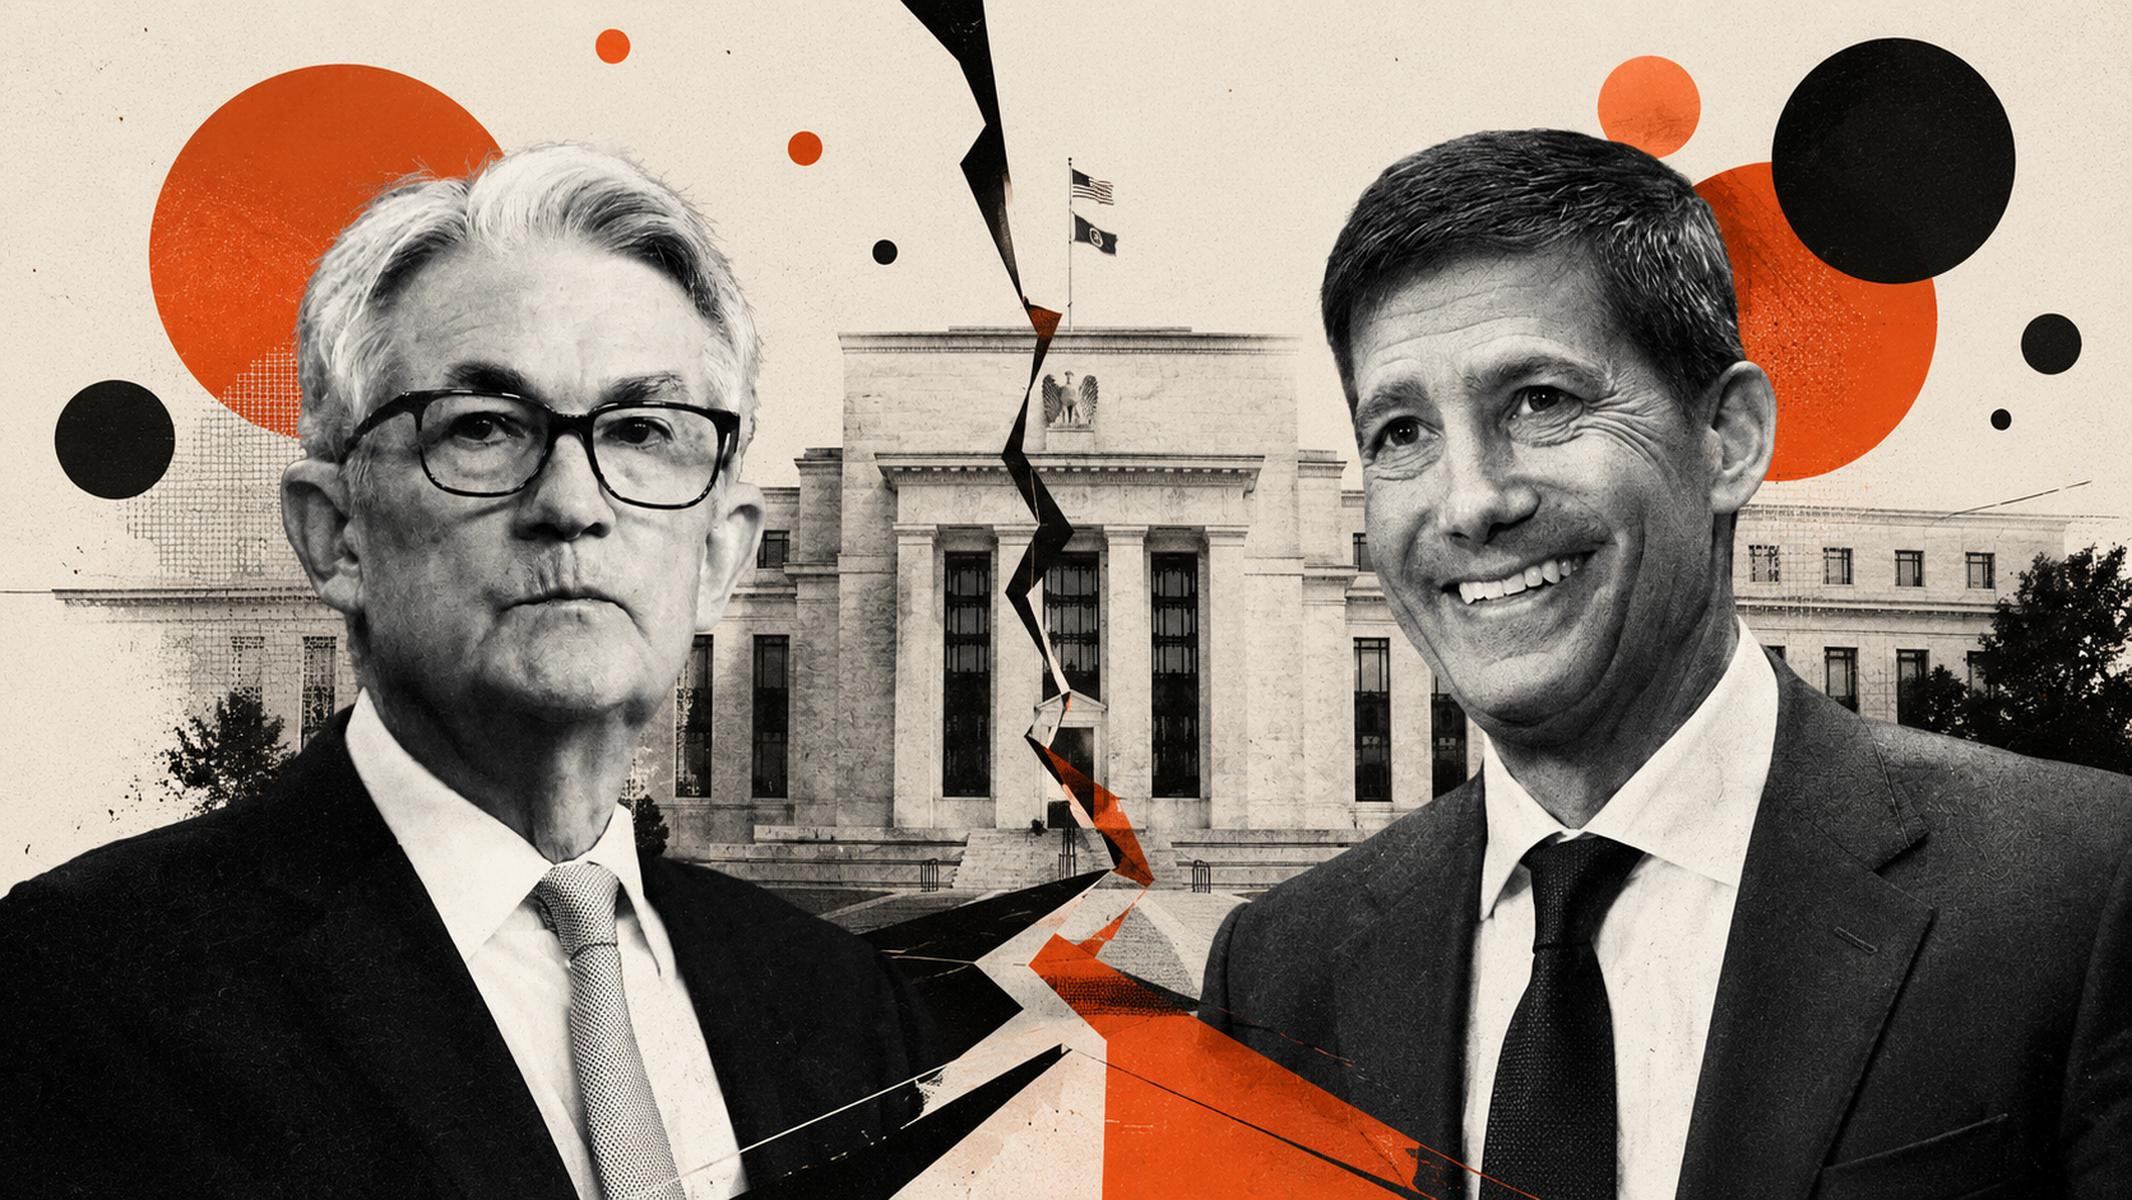
The Federal Reserve moves away from the highly predictable "forward guidance" model of the Jerome Powell era to a new “Kevin Warsh environment”, characterized by less communication, more policy surprises, and an increased focus on the Fed's complex balance sheet. For those trading the US Dollar, this leadership change brings questions about central bank independence, sticky inflation, and mounting political pressures.
Last week, Kevin Warsh replaced Jerome Powell as Fed chair. This is a major change that can entirely redefine how the markets read and react to Federal Reserve decisions, raising three key questions for currency traders: What does the Powell-to-Warsh transition actually mean for the Fed playbook? Why is the way Warsh reacts to his first major policy dilemma crucial for markets? And how could all of it reshape the trend of the US Dollar?
From Powell to Warsh
Under Jerome Powell, transparency became a market stabilizer through the Fed's communications strategy, also known as forward guidance. The Fed essentially kept traders informed about the tentative direction of interest rates, the evolution of inflation, and how policymakers were thinking months in advance. This made the Federal Reserve's interest rate decisions more predictable, with policy changes telegraphed through dot plots and by plenty of public speeches and interviews given by FOMC members. The markets had time to price in future interest rates before they were set, reducing Fed-led volatility and making tools such as the CME FedWatch chart a must for any macro trader.
Now, here comes Kevin Warsh. Having served as an FOMC board member under Ben Bernanke before the Global Financial Crisis, 20 years ago, Warsh represents a much more old-school Fed philosophy. For a Warsh-led Fed, markets expect less communication, surprises more often, and a gradual shift away from interest rates alone. This will mean more focus on the balance sheet itself, a monetary policy tool that is more complex to read than the fed funds rate.
As markets today are heavily wired to react to every single word about rates, a Fed under Warsh could create far more uncertainty and volatility across financial markets, especially around the US Dollar. The Fed sets policy through FOMC voting, in which 12 members vote on interest rates and guidance based on inflation, employment, and growth data. Although the Fed chair only has one official vote, Warsh, in this case, can influence and shift debates, consensus, communication, and the overall policy direction across the committee.
The central bank independence question
This leadership transition brings us to the Fed’s biggest conundrum: how to balance inflation and growth risks while resisting political pressure. We already know that President Trump wants lower rates; his public feud with Jerome Powell attests to that. But inflation figures have stayed way above the Fed’s long-term target of 2% for a long time, and the Middle East war has only exacerbated that problem. So, Warsh inherits a deeply conflicted macro environment.
On one side, inflation risks remain elevated due to energy shocks. On the other hand, the Trump administration has consistently favored lower rates, easier financial conditions, and a weaker USD to support growth and trade competitiveness. That creates a major policy dilemma.
Sticky inflation calls for the Fed to maintain policy tighter for longer. However, tighter policy risks hurting growth, increasing debt-servicing costs, and thus creating political friction with the White House. This brings us to one key question: how independent will the Fed be?
Implications for the US Dollar
That perception alone matters enormously for the US Dollar. The Greenback is seen as the world’s reserve currency. If investors begin to believe the Fed is becoming politically influenced, confidence in long-term USD stability could gradually weaken. A transition from Powell to Warsh creates uncertainty around future rate policy, communication strategy, inflation tolerance, and the Fed’s autonomy.
A less predictable Fed does not automatically mean an immediate USD weakness. In fact, the USD could initially strengthen as a safe haven amid the market’s nervousness over financial instability and higher long-term inflation. But a more politically pressured Fed, combined with debt persistence, could become bearish for the USD over time. That’s why this transition matters beyond just interest rates. This is about confidence in the US monetary policy framework as a whole.
Conclusion: a new monetary regime
To summarize, a Powell-to-Warsh transition could fundamentally reshape how the Fed communicates, how policy is implemented, and how global markets price the USD. It could mark the start of a completely new monetary regime, in which traders will need to pay more attention to balance-sheet policy than to forward guidance. Higher volatility and uncertainty may well be on the horizon.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor.)
Author

Dhwani Mehta
FXStreet
Residing in Mumbai (India), Dhwani is a Senior Analyst and Manager of the Asian session at FXStreet. She has over 10 years of experience in analyzing and covering the global financial markets, with specialization in Forex and commodities markets.

















