Japan's factory activity grows at fastest pace in nearly four years – PMI

Global developments
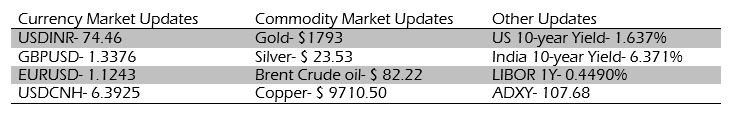
The sell-off in US treasuries which was triggered by Biden's announcement to reappoint Powell as Fed Chair continued. US yields have risen across the curve. US real rates too are higher. The Dollar has strengthened overall. Risk sentiment continues to be fragile in anticipation of faster tapering by the Fed. Comments from the BoE governor were hawkish. He said the BoE would have to trim the balance sheet at some point. These comments arrested the fall in Sterling. Hawkish comments from an ECB member however did not seem to have much of an impact on the Euro which continued to trend lower against the Dollar. Amid political pressure on account of surging inflation, the US (50mn barrels) along with India (5mn barrels), UK, China, Japan, and South Korea have released crude from strategic petroleum reserves. It remains to be seen how the OPEC+ reacts to this move. The next OPEC meeting is on 2nd December. FOMC minutes would be released late evening today. Tomorrow is a US holiday on account of Thanksgiving.
Domestic developments
Equities
Domestic equity indices had opened lower, following up on the day before yesterday's fall of 2%. However, equities bounced back strongly during the session, with the Nifty eventually ending 0.5% higher at 17503. Broader indices led the gains. US indices ended in the green yesterday with Dow up 0.55%. Asian equities are trading with a negative bias.
Bonds and Rates
Domestic bonds and Rates were steady yesterday. Money market rates rallied as IPO funding pressure eased. Higher VRRR cutoffs have not translated into higher money market rates as only banks have access to the Reverse Repo facility. A large section of the market does not and that has resulted in this dislocation. The RBI may look to address this in the upcoming monetary policy.
USD/INR
The Rupee had weakened to 74.57 intraday but recovered subsequently as domestic equities erased losses. The Rupee is exhibiting considerable resilience amid broad Dollar strength. High Beta currencies such as TRY, ZAR, MXN continue to underperform. The Turkish Lira continues to plumb new lows amid frantic volatility. Asian currencies are trading a tad weak against the Dollar. 1y forward yield ended at 4.85% while 3m ATMF vols are hovering around 4.75%. Last day March over First Day April points continue to remain elevated at 21p for 4 days.
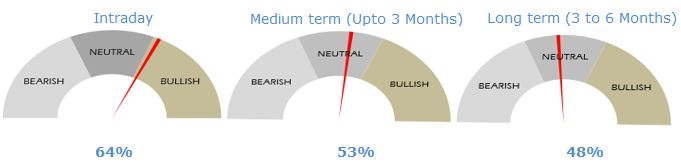
Strategy: Exporters are advised to cover on upticks towards 74.70 levels. Importers are advised to cover on dips towards 73.80 level. The 3M range for USDINR is 73.80 – 76.00 and the 6M range is 73.50 – 76.50.
Author

Abhishek Goenka
IFA Global
Mr. Abhishek Goenka is the Founder and CEO of IFA Global. He pilots the IFA Global strategic direction with a focus on relentlessly improving the existing offerings while constantly searching for the next generation of business excellence.

















