Italy’s corona crisis: Implications for the Italian economy, BTPs and Europe
-
Italian growth to see a big hit in H1 that risks pushing its debt to GDP ratio above 140% by the end of the year.
-
Brussels to apply leniency with budget and state aid rules. An Italian ESM programme remains an option of last resort.
-
Italian shutdown will hit neighbours' supply chains the hardest.
-
Italian banks to struggle with loan loss provisioning and lower profitability, while sovereign-bank linkages remain significant.
-
As long as Italy can avoid significant rating downgrades, we do not expect Italy to run into major funding problems.
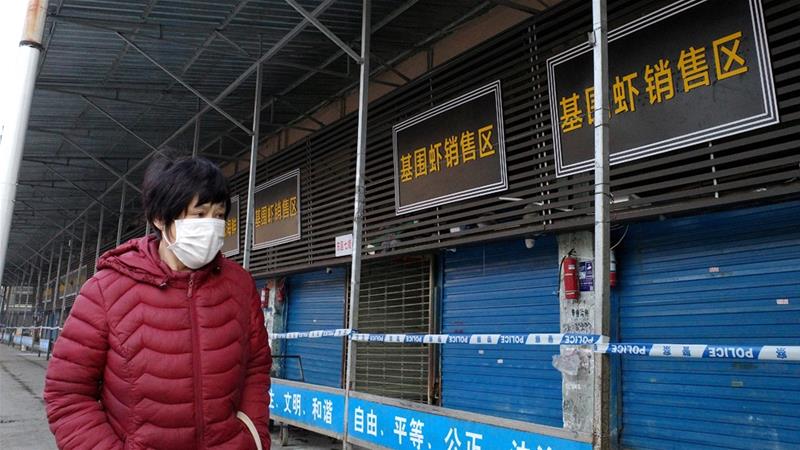
Yet again Italy has found itself at the epicentre of a crisis, battling with the most severe coronavirus outbreak globally after China. With the number of COVID-19 cases standing at 9,172 (at the time of writing), Italy has now even overtaken South Korea and the number of new infections continues to climb. Since the first COVID-19 infections where registered on 22 February, measures to contain the virus have been successively stepped up, culminating in nationwide school closures and travel bans on 10 March.
With the movement of some 60 million people severely restricted for an unknown period of time and companies, both public and private, encouraged to put their staff on leave, Italy's coronavirus crisis is rapidly turning from a humanitarian one to an economic one as well. Already at the end of 2019, the Italian economy was balancing on the brink of recession due to continued European industry headwinds and slowing consumer spending. Since 2018, services - accounting for 74% of gross value added - has been the main driver keeping the Italian economy afloat, much like in the rest of Europe. Government measures, such as the citizen income, also contributed to this. However, with the whole country essentially in lockdown, a sharp decline in service sector activity across sectors is likely on the cards. Neither does the outlook for manufacturing bring much cheer. On a p ositive note, Italy 's direct exp osure to Chinese sup p ly chain disrup tions is more limited than for example Germany 's. However, widesp read p roduction closures will still take their toll on industry output and we would not be surprised to see a quarterly growth contraction of -0.75 to -1.0% q/q in Q1.
Author

Danske Research Team
Danske Bank A/S
Research is part of Danske Bank Markets and operate as Danske Bank's research department. The department monitors financial markets and economic trends of relevance to Danske Bank Markets and its clients.