Intervention is a “con game”
Outlook
Some big guns are commenting on the US-Japan intervention, pointing out that BoJ chief Ueda said at last week’s policy meeting that he fears rising inflation—but then didn’t promote a hike or deliver forward guidance that a hike is coming. Intervention is a “con game,” according to one analyst. With the MoF and the American TreasSec promoting intervention and rate hikes, the independence of the BoJ is at risk. If Trump can’t control the Fed, maybe his lackey can control some other country’s central bank.
Whatever the next steps, everybody and his brother point out that the dollar/yen will be driven by what always drives currencies—growth and relative yields. The US worry is that Japan, the biggest holder along with China of US Treasuries, will sell them off and raise US yields. This is a genuine worry only if the US thinks there are no other buyers waiting in the wings, and this is likely the case because of the sheer size of the Japanese holdings.
Who else is out there who can replace Japan? Japan holds $1.143 trillion, and has already shed some over the past three months—from $1.209 trillion in April, now the lowest since April 2025. As we continue to note, nobody understand contagion. If Japan dumps Treasuries, maybe some others would want to follow.
Other central bank trouble resides at the Fed. Warsh bombed last week and we still await the correction. One issue—he must be losing respect among the other members of the FOMC not only because of what he said, but also fear that distaste for Warsh will contaminate the entire board. One member scoffed at the “task forces” that are supposed to deliver fresh insights leading to policy changes, as though the board and the giant and very smart team of backroom economists have missed something.
CNN had a cute headline—Keven Warsh can’t re-open the Strait of Hormuz. The article goes on to point out that upcoming inflation is not something the Fed can do anything about. Moody’s economist Zandi, who is pretty savvy, says “Monetary policy 101 says when there is a supply shock, don’t respond. Follow the script. It’s orked pretty well. Bottom line: I don’t think they should raise rates.”
This was written before the Fed decision last week but bears repeating. Zandi went on to warn “that raising rates to cool demand could tip over the stock market, which could take down the job market. ‘That’s a dangerous game to play. The labor market is weak and it wouldn’t take a lot to push us into a recession.’”
Even former Fed chair Yellen said earlier the “default strategy” for the Fed should be “looking through supply shocks,” instead of being tempted into rate hikes.
“’Monetary policy cannot tame supply-driven inflation without exacting unacceptable unemployment costs,’ Yellen said at a Brookings event.”
Thankfully, other are coming forward to point out that the US economy has been violating the “rules” of economics for some time. You can have high growth and high inflation at the same time. The rates of each have nothing to do with the credibility and trustworthiness of the Fed in the eyes of business people, financial markets and the average Joe.
Besides, the labor market has stabilized and is not “weak” enough to lead to a recession. That may be ahead because of AI, but it’s not here yet. AI can’t cook dinner or mow the lawn. In addition, the tech sector capital spending and its octopus arm effects shows no sign of abating.
All the same, there is a sense of crisis in the air centered around central banks.
Forecast
If currency expert TreasSec Bessent is worried about the world selling off US Treasuries, we should listen to him. The US current account deficit is almost $1 trillion—every year. This means foreign entities have the dollars and we count on them to return the dollars by investing in our bonds and equities, with some going into direct investment (US FDI still the most of anyone in the world, including China and India) and real estate. Remember when foreigners were buying up shopping centers?
If foreigners stop or reduce buying Treasuries, yields must go up to try to attract buyers. The extreme case is the US competing with the likes of Nigeria. That’s not going to happen, of course, but if Bessent is trying to fend it off, we need to heed.
Yields have been rising all by themselves on the inflation story and some modicum of anti-Trump sentiment. The latest tariff mess will also reduce the amount of dollars foreigners will have to deliver back. Rising yields are almost always a tailwind for the dollar. We are having a hard time buying into a lasting dollar decline because of the relative yield. Still, the chart rules.
Tidbit
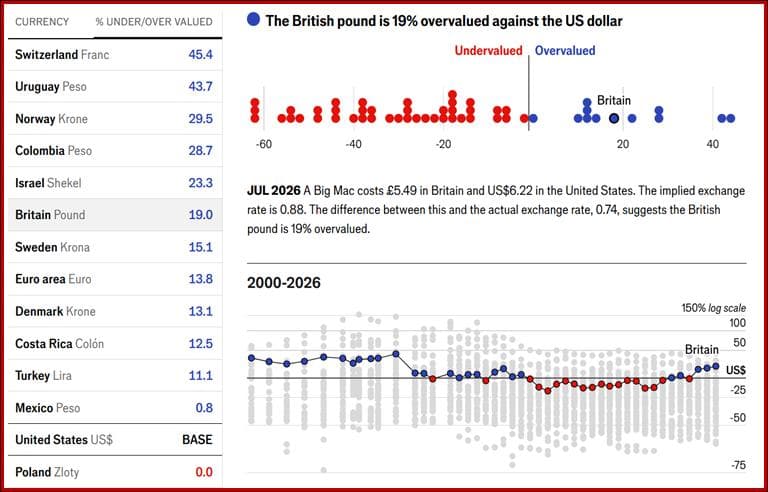
The Economist Big Mac comparison of currencies based on the price of a Big Mac was just updated. It is based on the purchasing power parity theory of currency valuation, which has 87 things wrong with it but is too much fun to drop. See the table. Apart from Poland’s currency being correctly priceD, the interesting thing is that the dollar is overvalued across the board.
This is an excerpt from “The Rockefeller Morning Briefing,” which is far larger (about 10 pages). The Briefing has been published every day for over 25 years and represents experienced analysis and insight. The report offers deep background and is not intended to guide FX trading. Rockefeller produces other reports (in spot and futures) for trading purposes.
To get a two-week trial of the full reports plus traders advice for only $3.95. Click here!
Author

Barbara Rockefeller
Rockefeller Treasury Services, Inc.
Experience Before founding Rockefeller Treasury, Barbara worked at Citibank and other banks as a risk manager, new product developer (Cititrend), FX trader, advisor and loan officer. Miss Rockefeller is engaged to perform FX-relat

















