Gold price’s coin flip lasted a day
The bulls were surprised today. You were not.
Gold closed Thursday at $4,539.90, its best day in weeks, after Fed Governor Waller said he would lean toward holding in September if August inflation shows progress, and the odds of a hike fell from 63 percent to a coin flip. This morning, the August payrolls printed 162,000 against a consensus of 55,000, the odds went back above 60 percent within minutes, and gold trades near $4,427 as I write this, with silver falling faster.
The market got its dovish Fed. It lasted one session.
What happened after yesterday's alert
Waller's remarks landed after yesterday's analysis was posted, and they did what Williams did not the day before: the two-year yield fell to 4.32 percent, the 10-year closed at 4.76 percent for a second day of declines, the Dow gained 624 points, the S&P 500 rose 1.1 percent, and the Nasdaq 1.4 percent, their best day in nearly a month, and gold rose 2.8 percent into the close.
Yesterday, I wrote: "A dollar that falls because another central bank turns more hawkish is not the same as a dollar that falls because the Fed turns dovish." This is also in perfect tune with my gold forecast for September 2026.
For one afternoon, the Fed did turn dovish, on one governor's conditional preference, and gold's best day in weeks was built on it. The condition was that the data cooperate.
The data did not cooperate
Payrolls rose 162,000 in August, the strongest month since March, with the prior two months revised up by a combined 55,000 and July's loss turned into a gain of 21,000. The unemployment rate held at 4.1 percent and wages rose 0.3 percent. Short-end yields jumped, the USD Index reversed from its weekly low near 98.9 to trade above 99.3, and the hike odds that Waller had pulled to 50 percent went back above 60.
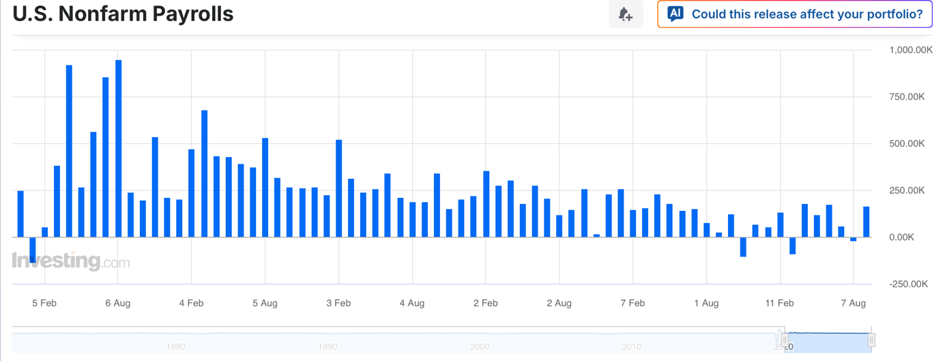
Yesterday, I also wrote: "Tomorrow's payrolls are the last release before the decision that has any chance of moving those odds."
They moved them, and in the direction that hurt the hold camp most. Bank of America counted 61 inflation references in Chair Warsh's Jackson Hole speech against 30 for the labor market, so a soft jobs number was the only argument the hold camp had, and this morning removed it. What remains is next Friday's CPI, carrying a month of elevated oil, five days before the decision.
Silver led both ways
Yesterday, I wrote: "This dynamic: miners weaker than gold and silver stronger than gold has 'watch out, it's a fake rally' written all over it."
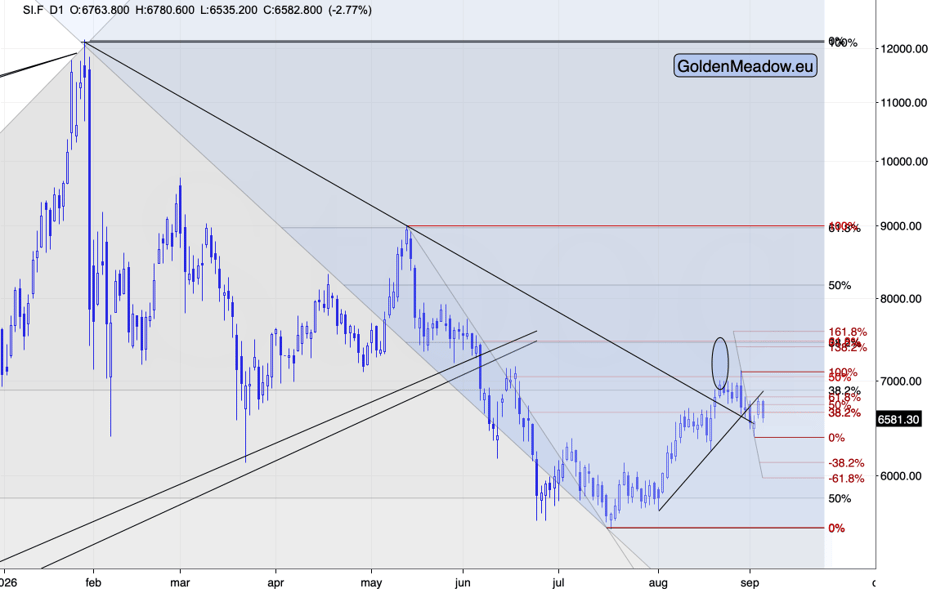
Silver led Thursday's rally, and it is leading this morning's decline, falling faster than gold. That is the sequence silver has delivered at this year's tops: it outperforms into the peak and underperforms out of it.
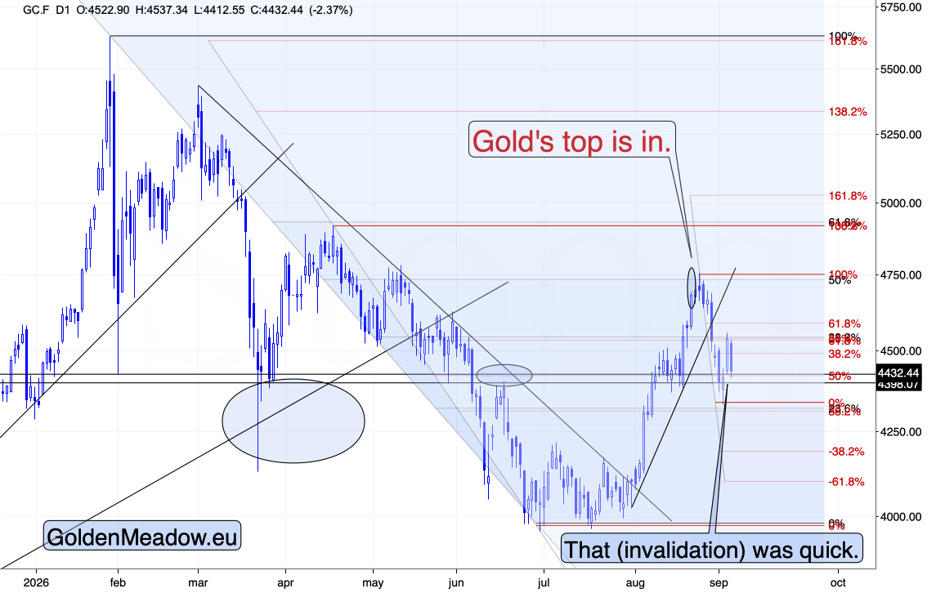
Gold plunged almost as much as it had rallied yesterday. Please note that the current back-and-forth movement is somewhat similar to what we saw in mid-August (with more volatility this time). Both consolidations could be the shoulders of a head-and-shoulders top formation. The target based on this formation would be close to $4,100, but please remember that the targets based on this formation work on an “at least” basis.
The miners at the line
Yesterday, the GDXJ closed about 3.3 percent higher near $132.3.
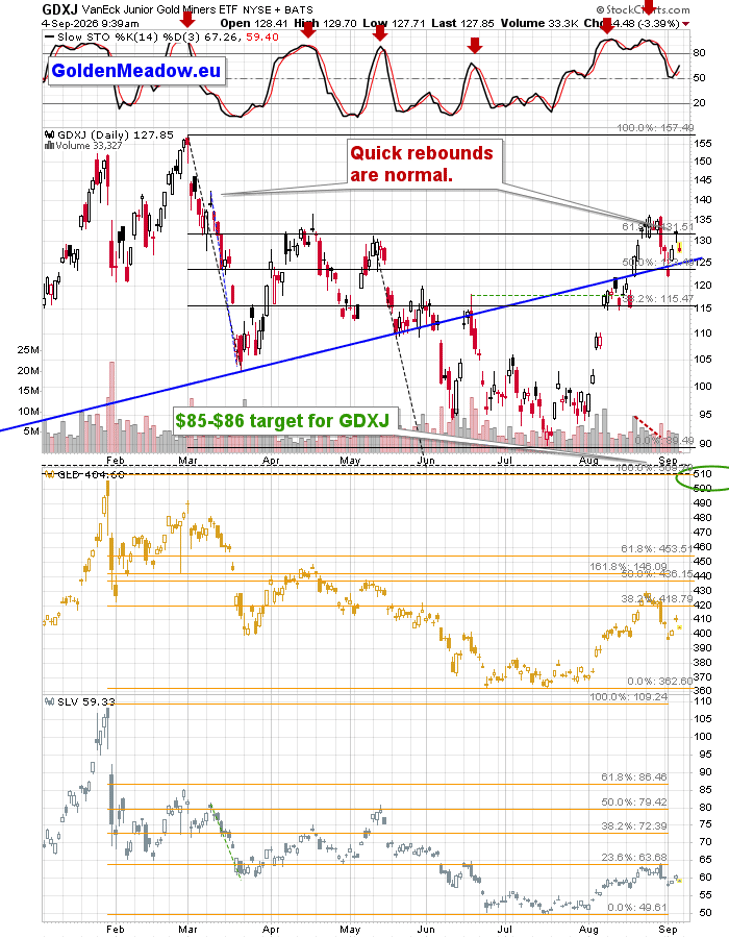
Today, it’s already about 3.4% lower – more than cancelling yesterday’s upswing.
On Wednesday, I wrote: "This move lower is likely to continue soon, just as the March decline continued."
The March rebounds were sharp, they reached resistance, and they were over within days. This one reached resistance in two, and the corrective upswing seems to be over.
The Dollar held the retracement
Yesterday, I wrote that the USD Index's decline "stopped at the 61.8% Fibonacci retracement level based on the late-August rally" and that it was "a post-breakout correction." The index bottomed near 98.9 overnight, at that retracement, and reversed higher on the payrolls.
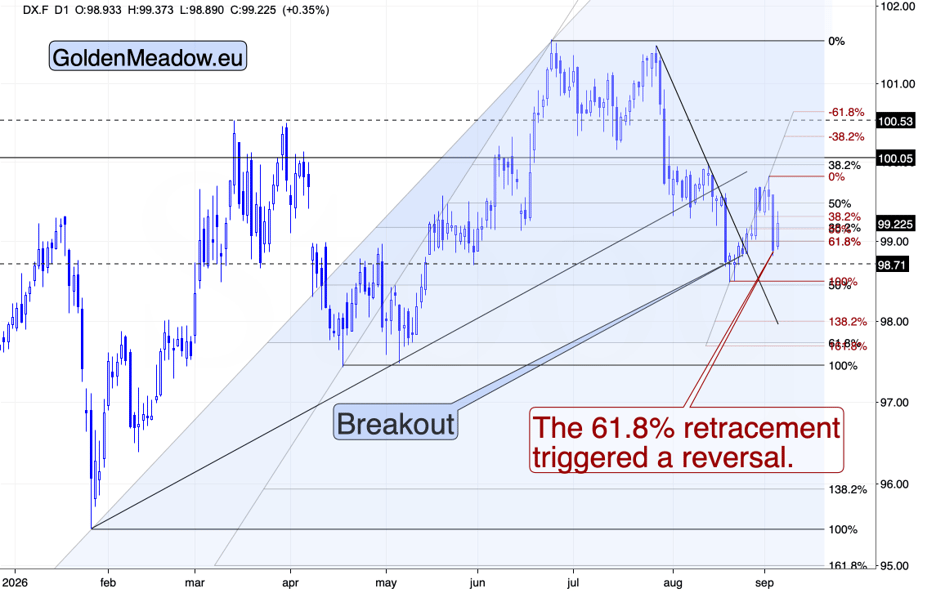
The yen is still near 155, the Bank of Japan is still expected to hike on September 18, and the dollar is rising anyway. The headwind that produced yesterday's decline is still blowing, and the index is moving into it. That is the rate channel reasserting itself over the currency story within a day.
Please note that gold, silver, and mining stocks declined more – compared to yesterday’s upswing – than the USD index rallied compared to yesterday’s decline.
This kind of USD-PMs link is exactly what we want to see when forecasting declines in the precious metals sector.
Iran, briefly
The exchange of strikes quieted after Wednesday. The IRGC claimed two tankers hit mines in the strait, which CENTCOM denied, Iran's foreign minister met his Qatari counterpart in Tehran on Thursday in the latest mediation attempt, and President Trump wrote that he is "not trying to force Iran to the bargaining table" and likes the current position better, "with almost total control of the Hormuz Strait." Daily transits remain at less than half their pre-war level.
Brent is near $95 and up about 7 percent on the week, WTI is lower this morning, and gold is giving back a hundred dollars on a week when oil rose 7 percent. The war premium has not been in the gold price since spring, and this week did not put it back.
Where this leaves us
My outlook and positions are unchanged, and my subscriber-only profit-take levels remain in place.
Silver led the bounce and is leading the decline, the miners closed at the line and are set to open below it, FCX fell on the sector's best day in weeks, and the dollar held the retracement it needed to hold and reversed on the data.
The hold camp needed one thing from the labor market. The labor market gave the hike camp its best number since March.
Want free follow-ups to the above article and details not available to 99%+ investors? Sign up to our free newsletter today!
Author

Przemyslaw Radomski, CFA
Gold Price Forecast
Przemyslaw Radomski, CFA (PR) is a precious metals investor and analyst who takes advantage of the emotionality on the markets, and invites you to do the same. His company, Sunshine Profits, publishes analytical software that any