Australian Dollar Price Forecast: Further consolidation not ruled out
- AUD/USD fades Friday’s gain, although the 0.7000 region holds the downside.
- The US Dollar adds to its recent gains amid a broadly cautious stance.
- The next risk events for the pair will come from the Fed and domestic inflation.
The Australian Dollar (AUD) has started the new trading week on the back foot, prompting AUD/USD to partially give away Friday’s advance, revisiting at the same time the boundaries of the 0.7000 contention zone.
The pair’s resumption of the selling interest has followed the US Dollar’s firm price action, underpinned by the widespread caution among investors ahead of key data releases as well as the Federal Reserve’s (Fed) interest rate decision later in the week.
Looking at the broader picture, spot continues to trade just below its 200-day SMA near 0.7050, keeping the bearish outlook well in place for now. However, the Reserve Bank of Australia’s (RBA) hawkish policy stance, in combination with still elevated domestic inflation, should cushion against any deep and sustained corrections.
Australia's resilience comes with a few cracks
Australia’s economy continues to compare favourably with many of its G10 peers, supported by domestic demand and positive economic growth. Persistent inflation also supports the RBA’s cautious, data-dependent policy stance.
However, business activity seems to have lost some momentum after preliminary data showed the Purchasing Managers’ Index (PMI) for Manufacturing improving marginally to 49.5 in September and easing to 47.8 when it comes to Services, from 49.6 and 51.9, respectively.
Trade data provided another positive, albeit humble, signal after August’s trade surplus came in at just A$0.495 billion, adding to the A$1.351 billion surplus registered in the previous month (revised from A$1.923 billion).
Growth figures were less encouraging, however. Indeed, the Gross Domestic Product (GDP) expanded by 0.4% QoQ in the second quarter of 2026, up from 0.3%, while annual growth came in at 2.1%, down from the previous 2.5% yearly expansion.
The labour market, however, disappointed investors in September after the Unemployment Rate held steady at 4.7% (August’s print was revised higher to 4.7% from 4.6%), and the Employment Change shrunk by 39.3K, reversing August’s 29.3K increase (revised from 39.5K).
Inflation seems to have lost some impulse after the most-watched Trimmed Mean came in at 3.6% over the last twelve months, despite the headline CPI ticking higher to 4.0% from a year earlier.
The Melbourne Institute’s Consumer Inflation Expectations measure reinforced those figures after ticking higher to 5.3% in October.
The figures leave the RBA’s inflation task incomplete. Policymakers expect inflation to return to target only in early 2028, keeping the emphasis on patience rather than an imminent policy pivot.
China steadies the ship, but offers little extra fuel
China is providing stability for the Australian economy, but not the growth impulse that has supported the Australian Dollar during previous expansions.
The Chinese economy grew by 4.5% YoY in the July-September period, while Industrial Production growth regained traction, expanding by 5.5% from a year earlier and 5.3% YDT. In addition, the latest trade data showed a $133.53 billion surplus in September, supported by firm increases in both imports and exports. Reinforcing this picture, consumer spending remained solid after Retail Sales expanded by 1.1% over the last twelve months.
In addition, business surveys presented a promising picture: the National Bureau of Statistics reported that the Manufacturing PMI improved to 50.1 in September (from 49.8), while the Services PMI improved to 50.2 (from 49.0). In the same direction, private measures like RatingDog remained in expansionary territory, with Manufacturing at 52.1 (from 51.5) and Services at 51.6 (from 51.4).
Disinflationary pressures seem to have taken a breather in September, with the CPI gaining 0.9% from a year earlier, up from 0.8%, while prices rose by 0.2% on a monthly basis. Producer Prices rose more than initially estimated by 5.0% over the previous twelve months, up from the 3.8% increase recorded in the previous month.
As widely anticipated, the People’s Bank of China (PBoC) kept its Loan Prime Rates (LPR) unchanged at 3.00% for the one-year tenor and 3.50% for the five-year tenor.
Following the latest string of auspicious results from Chinese fundamentals, it seems to finally add some optimism for Australia and the Aussie Dollar.
RBA keeps the tightening door wide open
In a unanimous decision, the RBA hiked its OCR by 25 basis points to 4.60% at its meeting in late September.
The RBA Minutes showed a unanimous vote for more tightening. Indeed, all Board members voted for the 25 basis point rate hike, believing that excess demand was stronger than previously assumed and that the risk of persistently high inflation had increased. Furthermore, policymakers debated whether to hold rates for a moment but decided to take timely action to keep inflation expectations anchored.
Additionally, the RBA highlighted broad domestic cost pressures, higher unit labour costs, elevated oil prices and emerging inflation risks from the AI boom. Some indicators suggested financial conditions were only modestly restrictive, while models implied the neutral rate may have moved higher. The Board also warned that a rise in global neutral rates could weaken the Australian Dollar if domestic rates failed to follow.
Overall, the Minutes were clearly hawkish and leave further tightening firmly on the table, although policymakers remain mindful of falling house prices and the risk of slowing economic activity.
In the meantime, market participants now pencil in roughly 20 basis points of tightening from the RBA by year-end, while they remain pretty divided regarding a rate hike at the November 3 gathering.
AUD/USD recovery faces its toughest test yet
Baseline outlook
A further sidelined mood should not be ruled out in the short-term horizon. In the meantime, and looking at the broader picture, the pair should face a steady chance of further declines while below the 200-day SMA around 0.7050.
The resumption of the bullish bias will likely require a strong catalyst, namely a sustained improvement in risk appetite trends or renewed and persistent weakness in the Greenback.
Upside scenario
A stronger risk-on environment should encourage the pair to clear the key 0.7000 threshold in a sustained fashion. Once surpassed, spot is expected to face the next hurdle at its 200-day SMA, all preceding the weekly top at 0.7140 (September 21). North from here, a test of the 2026 ceiling near 0.7280 should come into view.
Downside scenario
In case bears regain control of sentiment surrounding the Aussie, there should be initial support at the October valley of 0.6894 (October 15). A breach below this level would increase the likelihood of a retest of the June bottom near 0.6860 (June 30).
Bears dig deeper, but the market is pushing back
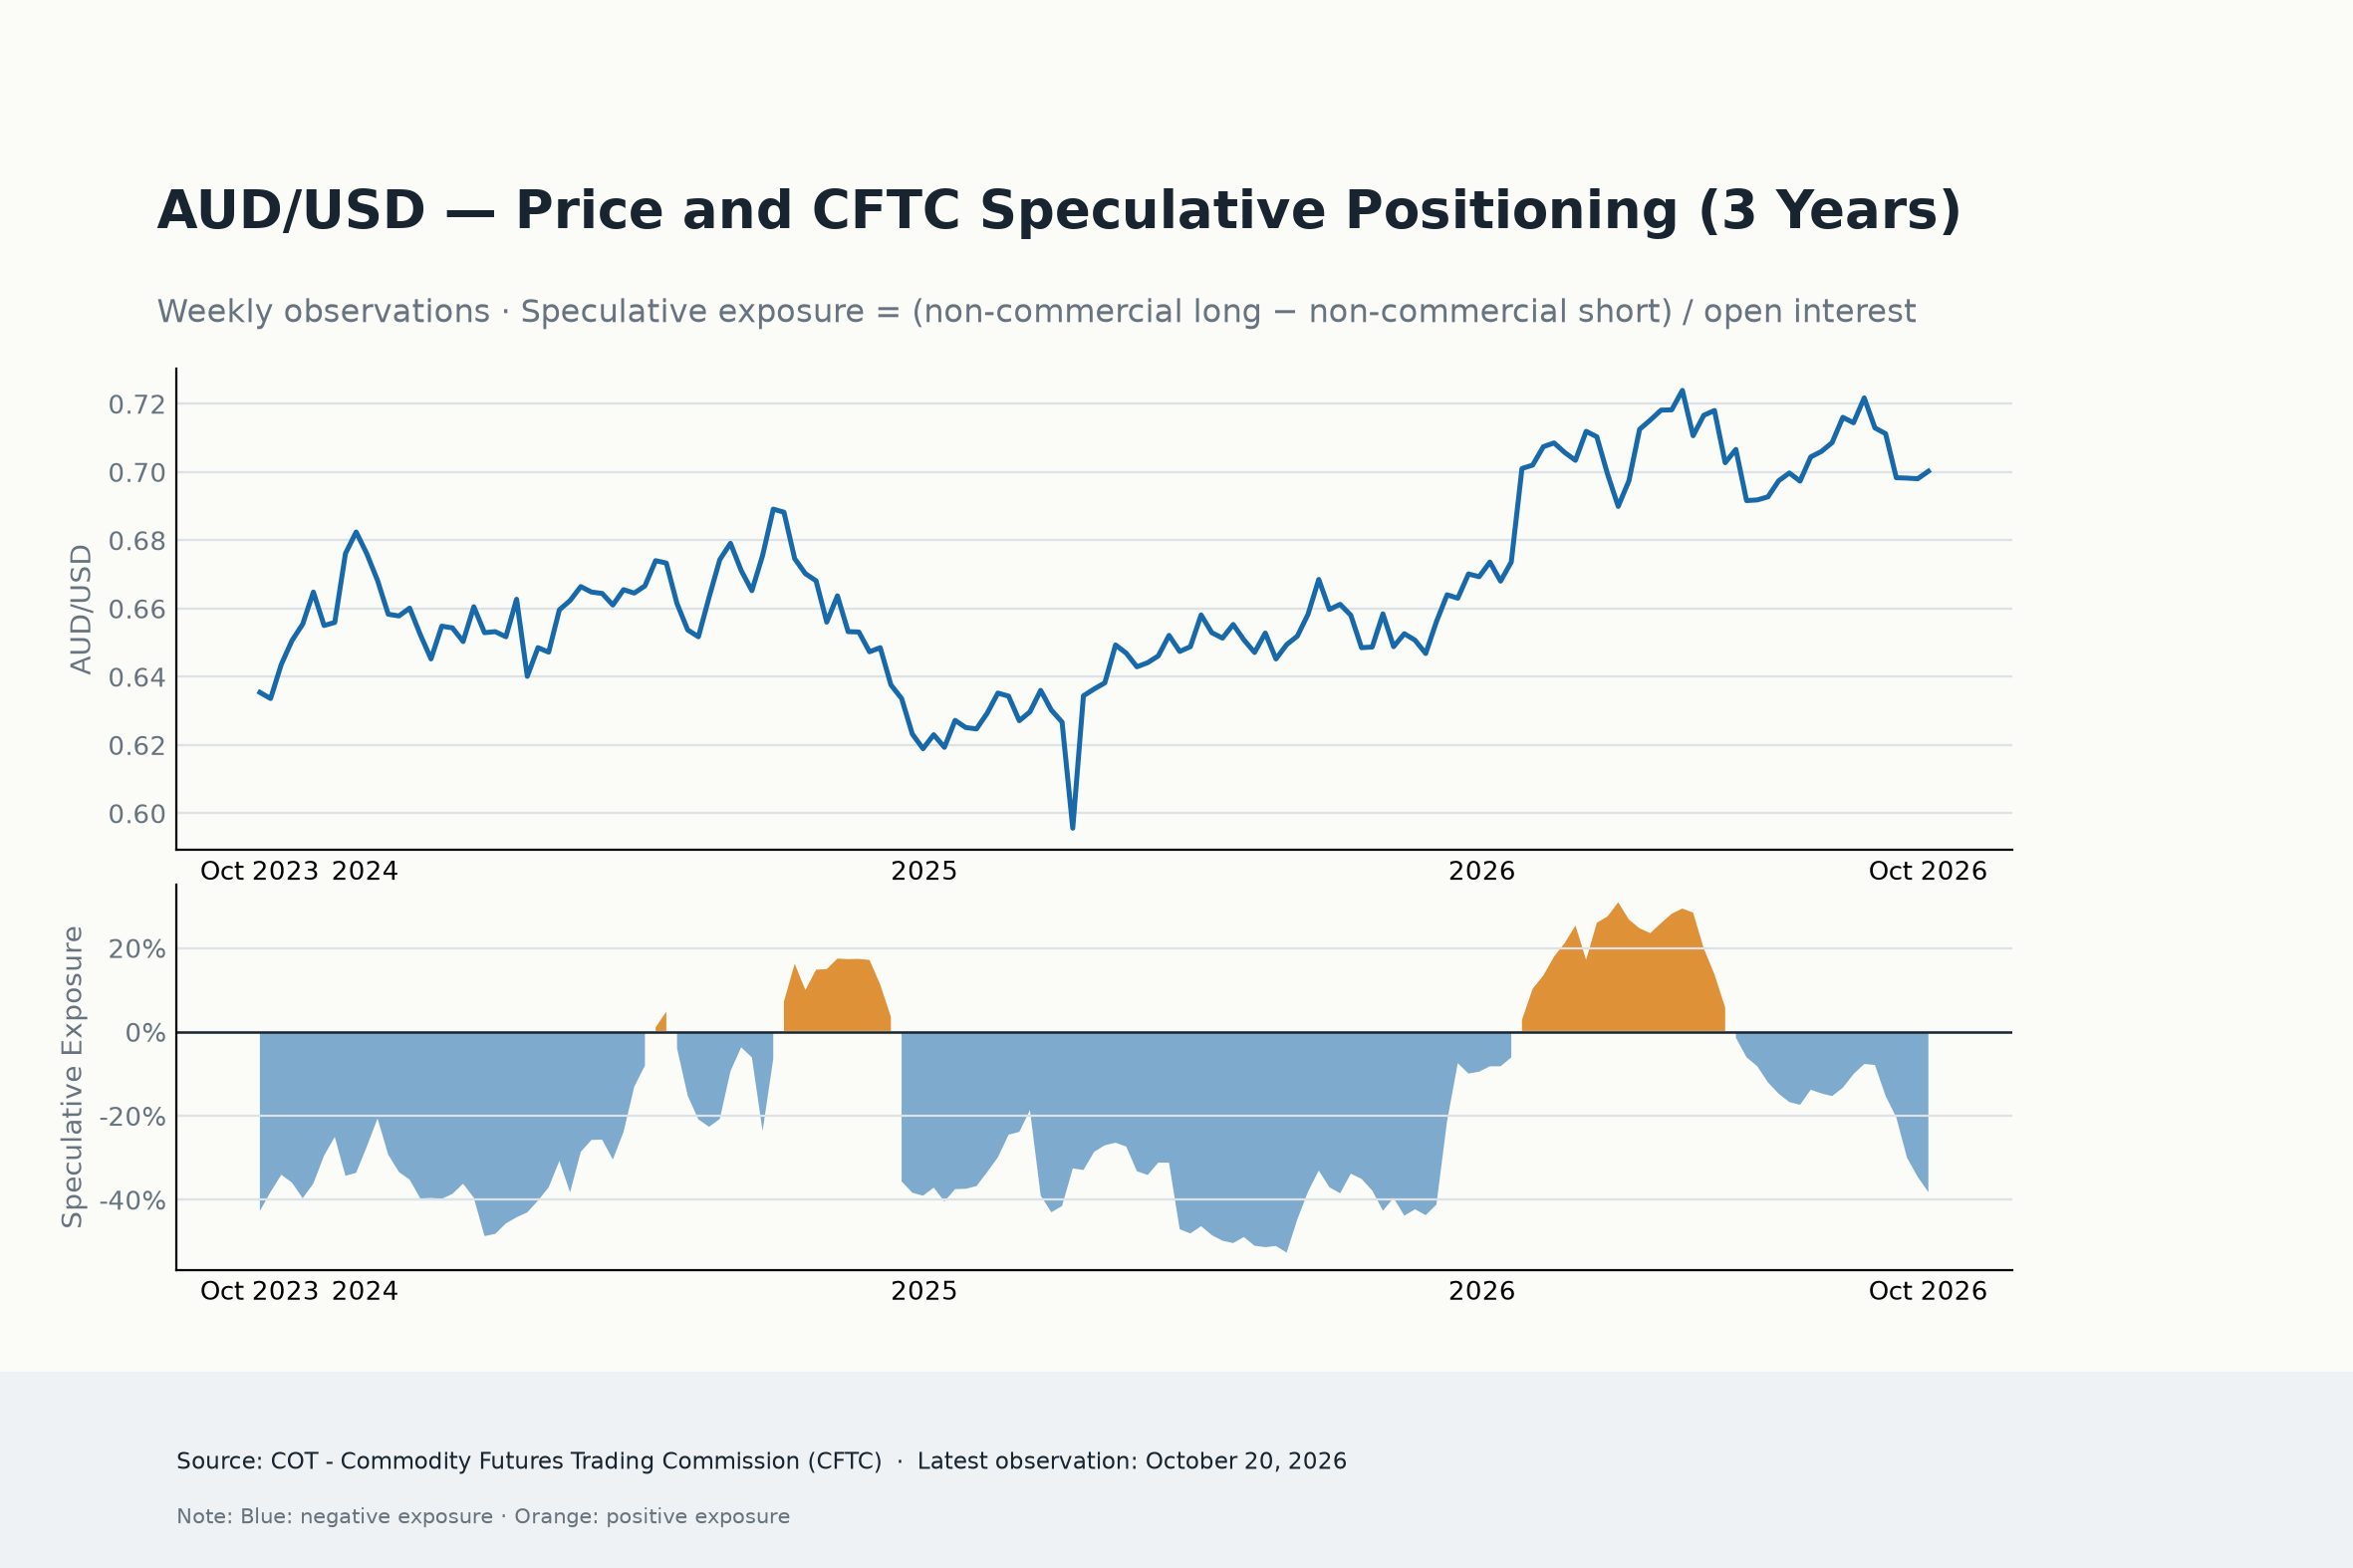
AUD bearish positioning intensified further in the week ending October 20, according to the latest Commodity Futures Trading Commission (CFTC) report. Non-commercial net shorts increased to almost 127.3K contracts, although the weekly decline slowed to nearly 10K contracts. The four-week change deteriorated to around -80.5K contracts, confirming that the broader bearish trend remains firmly established.
Open interest fell to just over 333K contracts. Net shorts increased, with bearish exposure rising and total market activity contracting in the latest move. The aggregate figures alone, however, cannot establish how much of the change came from long liquidation versus fresh short-building.
Speculative exposure fell further to -38.2%, while its percentile declined to 24.7. The Net Position Percentile remained at 0.0, indicating that the absolute net-short position is still at an extreme historical level, even though the speculative exposure percentile is less extreme.
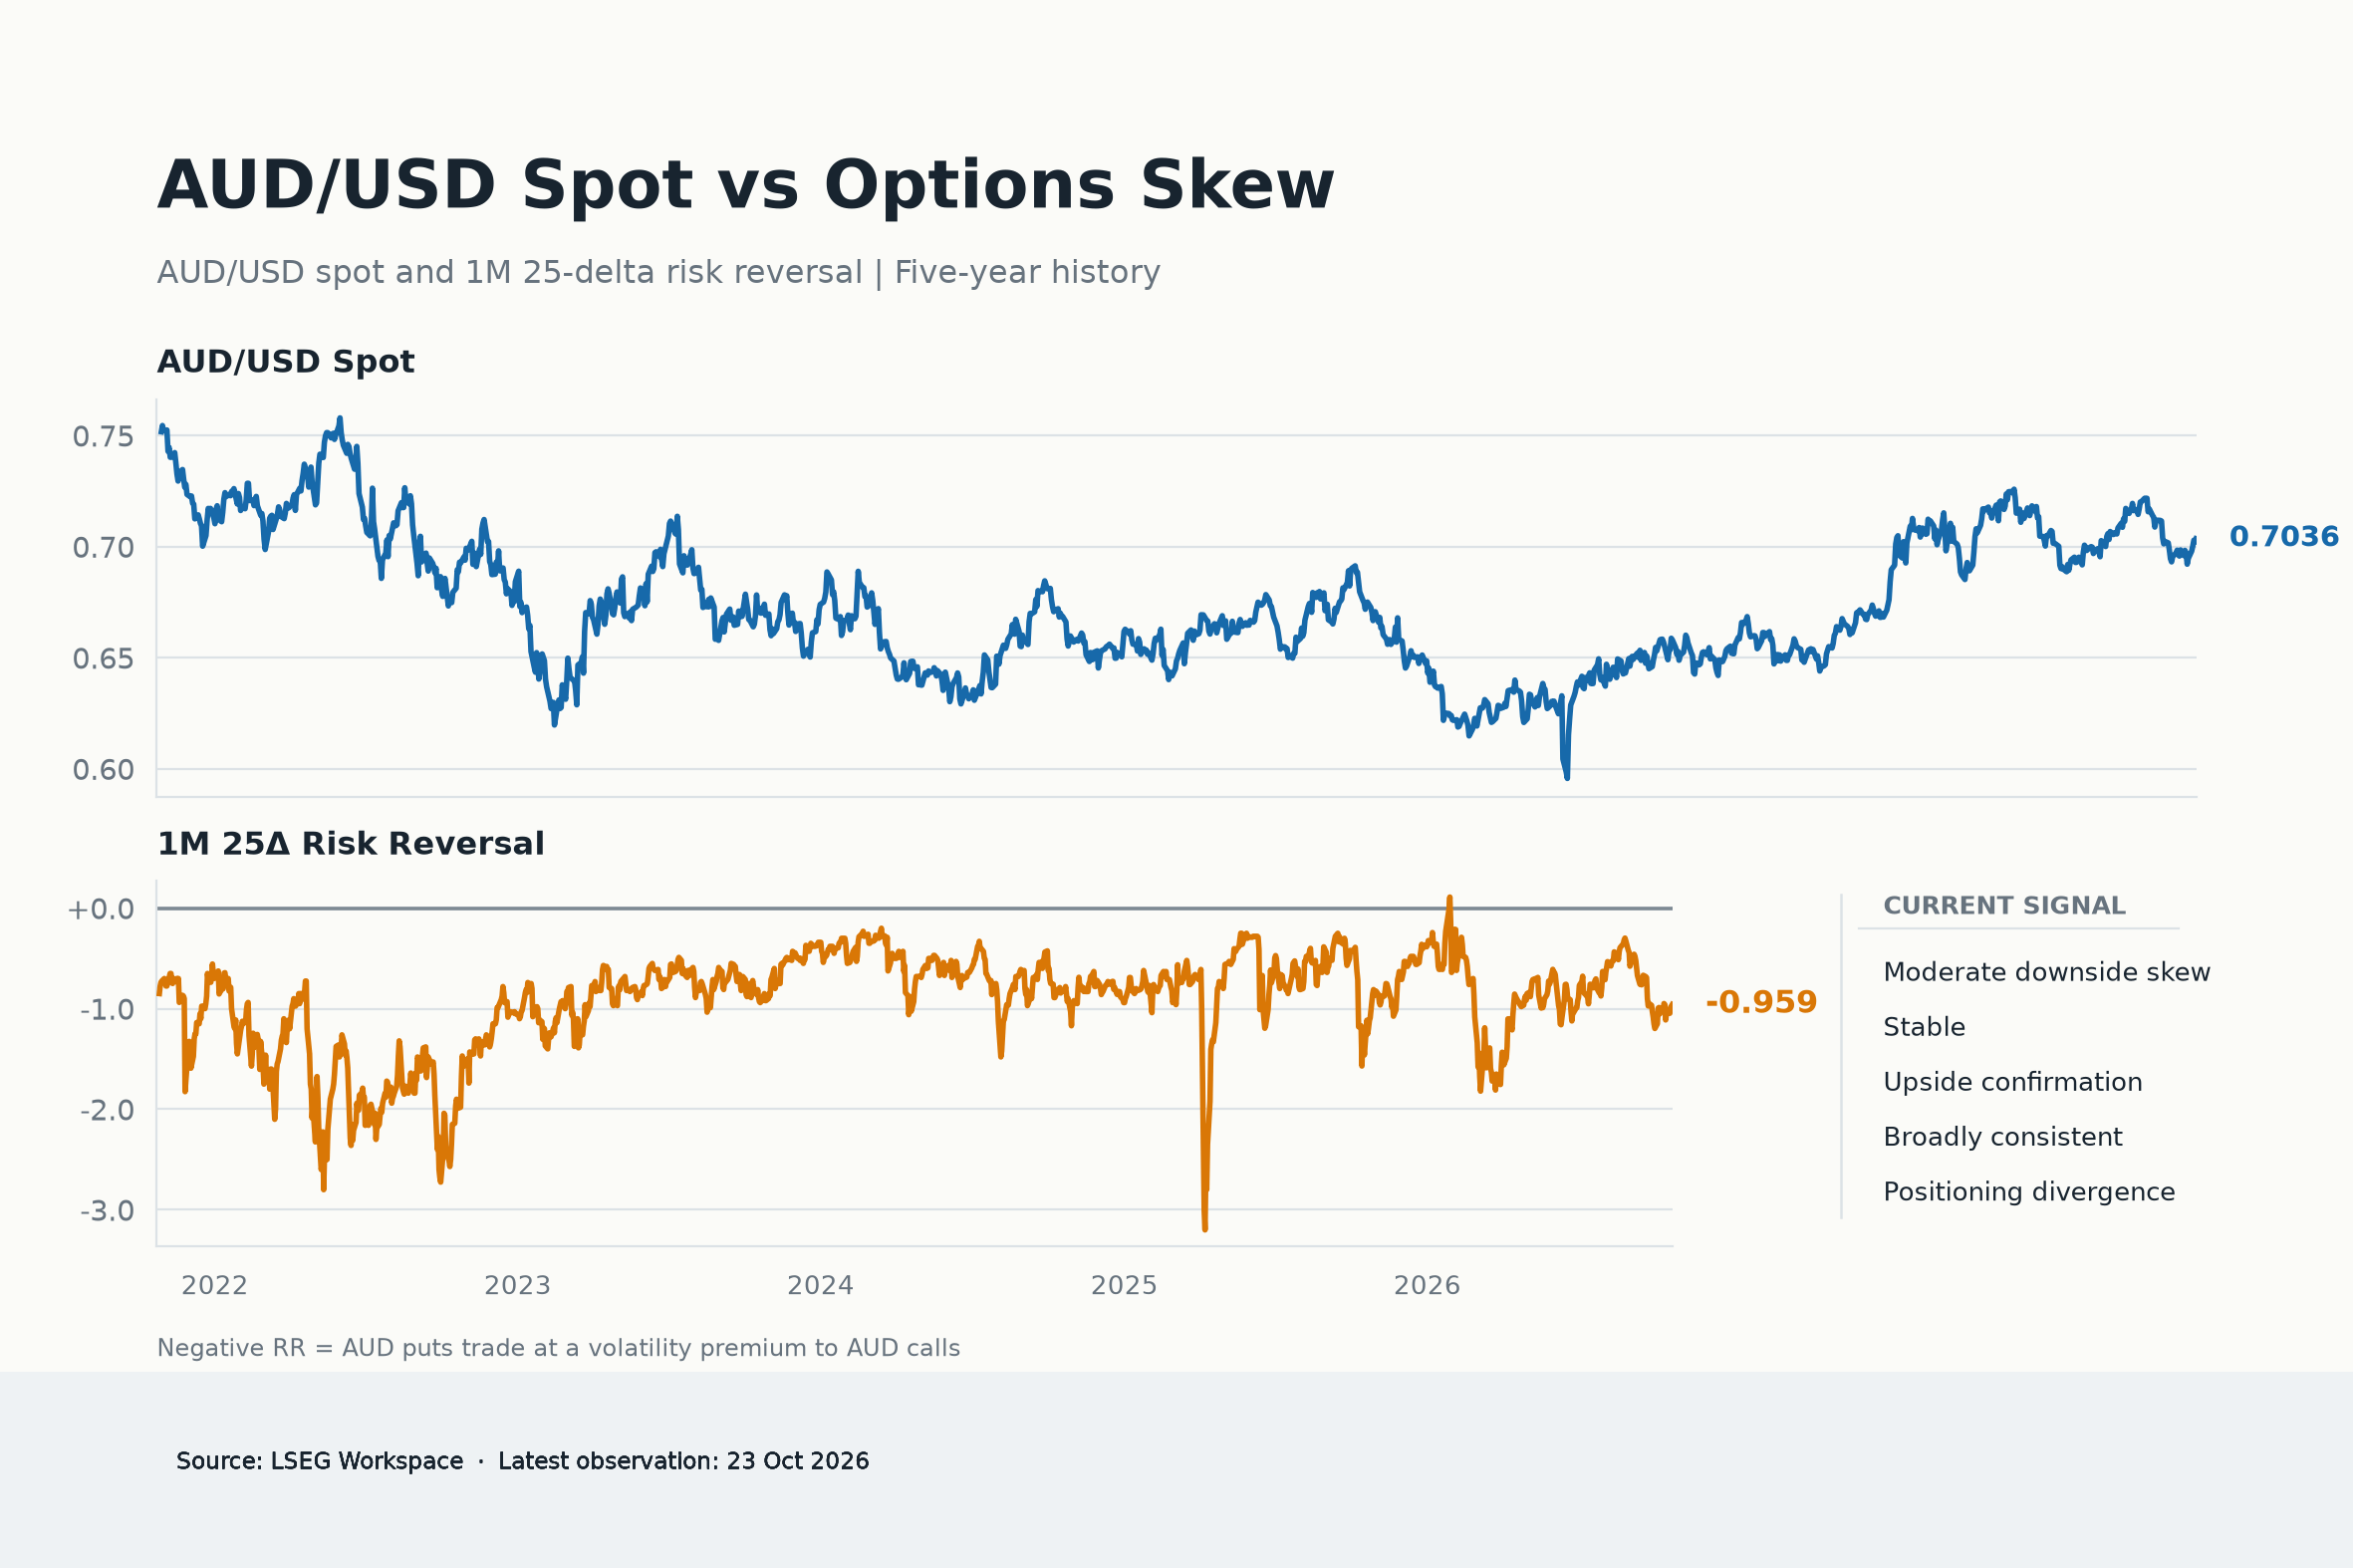
Meanwhile, the options market presents a somewhat different picture. The one-month 25-delta Risk Reversal improved to -0.959 volatility points on October 23, from -1.047 a week earlier. AUD puts still price a volatility premium to comparable calls but the latest reading is at the 32nd percentile of its five-year distribution, suggesting a moderate rather than particularly bearish downside skew.
The improvement was accompanied by a significant weekly rebound in the AUD/USD, which managed to break above the 0.7000 level. Both pairs have posted modest gains over the past month. Risk Reversals improved by 0.014 volatility points. Historically the spot advance would point to a 0.032 volatility point improvement.
The resulting deviation of -0.018 volatility points ranks at the 48th percentile of the rolling out-of-sample distribution, suggesting that options pricing remains broadly consistent with the currency's performance. In other words, options traders are becoming somewhat less defensive, but there is little evidence of an unusually strong bullish repricing.
This distinction matters: while speculative futures positioning continues to deteriorate, spot and options have recently moved in a more constructive direction. The resulting cross-market divergence suggests that bearish conviction in futures is no longer being fully reflected in the currency's immediate price action.
Nevertheless, the improvement in options sentiment remains relatively modest. The three-month Risk Reversal change remains negative at -0.127 volatility points, while the one-month skew continues to favour downside protection.
Overall, AUD positioning remains decisively bearish, but the short trade increasingly faces a potential squeeze. Net speculative shorts are historically extended, while spot has recovered and options sentiment has stabilised. This combination raises the possibility of a sharper rebound if bearish positioning begins to unwind, although continued weekly short accumulation and the absence of exceptional bullish options demand suggest that a sustained reversal remains unconfirmed.
Australian CPI and the Fed set up a pivotal week
US Dollar dynamics, global risk sentiment, and geopolitical developments remain the main near-term drivers of AUD/USD.
Event-wise, all the attention is expected to be on October 28, where we will see the inflation figures in Australia, seconded by the key FOMC gathering later in the day.
Beyond that, the main risks are expected to emerge from China, a persistently cautious Fed, a deterioration in investor risk appetite or a change in the RBA’s current policy stance.
Any of these developments could quickly alter the outlook for the Australian currency.
Technical analysis
In the daily chart, AUD/USD trades at 0.7025, retaining a capped near‑term tone as it holds beneath the 100‑day simple moving average (SMA) at 0.7033 and the 200‑day SMA at 0.7053, with the 55‑day SMA further overhead at 0.7073. The pair’s recovery off recent lows is underpinned by a mildly constructive Relative Strength Index near 52 while the Average Directional Index around 30 suggests a moderate, but not aggressive, trend, yet the location of price below all key averages hints that rallies remain vulnerable to selling into resistance.
On the topside, initial resistance is located at the 100‑day SMA at 0.7033, followed by the 200‑day SMA at 0.7053 and the 55‑day SMA at 0.7073, ahead of the horizontal barrier at 0.7079; above there, higher resistances are seen at 0.7278 and 0.7283, before the more distant ceiling at 0.7661. On the downside, first support emerges at the horizontal level near 0.6833, with deeper cushions at 0.6660 and 0.6593, while 0.6414 and 0.6373 mark more substantial structural floors if selling pressure resumes.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Crowded shorts meet a hawkish RBA
Although the big picture is nowhere near convincing, the Australian dollar (AUD) has a few reasons for optimism. The RBA’s hawkish stance and relatively resilient domestic fundamentals should help keep sellers at bay, but a firmer US Dollar, lingering geopolitical tensions and China’s lacklustre recovery could make further gains difficult to sustain.
There is, however, an intriguing twist. Speculators have continued to pile into AUD shorts, yet the currency has managed to regain some ground while options markets have become less defensive. That combination leaves the Aussie exposed to a potentially sharp rebound if traders start unwinding their bearish bets.
Attention now turns to Australia's October 28 inflation figures and the Fed’s rate decision later that day. Sticky domestic inflation and a less hawkish Fed could give the Aussie another leg higher, while softer price pressures and renewed demand for the Greenback would likely put sellers back in charge.
For now, a cautiously neutral stance with a slight bullish tilt seems warranted. The ingredients for a recovery are there, but whether the Aussie can build on its recent gains will depend as much on what happens abroad as on the RBA's determination to bring inflation under control.
RBA FAQs
The Reserve Bank of Australia (RBA) sets interest rates and manages monetary policy for Australia. Decisions are made by a board of governors at 11 meetings a year and ad hoc emergency meetings as required. The RBA’s primary mandate is to maintain price stability, which means an inflation rate of 2-3%, but also “..to contribute to the stability of the currency, full employment, and the economic prosperity and welfare of the Australian people.” Its main tool for achieving this is by raising or lowering interest rates. Relatively high interest rates will strengthen the Australian Dollar (AUD) and vice versa. Other RBA tools include quantitative easing and tightening.
While inflation had always traditionally been thought of as a negative factor for currencies since it lowers the value of money in general, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Moderately higher inflation now tends to lead central banks to put up their interest rates, which in turn has the effect of attracting more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in the case of Australia is the Aussie Dollar.
Macroeconomic data gauges the health of an economy and can have an impact on the value of its currency. Investors prefer to invest their capital in economies that are safe and growing rather than precarious and shrinking. Greater capital inflows increase the aggregate demand and value of the domestic currency. Classic indicators, such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can influence AUD. A strong economy may encourage the Reserve Bank of Australia to put up interest rates, also supporting AUD.
Quantitative Easing (QE) is a tool used in extreme situations when lowering interest rates is not enough to restore the flow of credit in the economy. QE is the process by which the Reserve Bank of Australia (RBA) prints Australian Dollars (AUD) for the purpose of buying assets – usually government or corporate bonds – from financial institutions, thereby providing them with much-needed liquidity. QE usually results in a weaker AUD.
Quantitative tightening (QT) is the reverse of QE. It is undertaken after QE when an economic recovery is underway and inflation starts rising. Whilst in QE the Reserve Bank of Australia (RBA) purchases government and corporate bonds from financial institutions to provide them with liquidity, in QT the RBA stops buying more assets, and stops reinvesting the principal maturing on the bonds it already holds. It would be positive (or bullish) for the Australian Dollar.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.

















