European stocks slip into negative territory amid inflation and ahead of ECB monetary policy meeting

Key highlights
The RBA blindsided economists when it increased the cash rate from 0.35 percent to 0.85 percent, the largest increase in 22 years, and indicated inflation would peak higher than the 6 percent forecast in May. The Reserve Bank of Australia is tipped to lift the cash rate to 1.35 percent in July, using back-to-back 0.5 percentage point rate rises in an effort to curb inflation, which the bank says is growing faster than expected.
Growth among British businesses slowed sharply in May to its weakest since early 2021 when the country was under a COVID-19 lockdown, according to a survey, although the loss of momentum was less severe than initially reported. The composite Purchasing Managers Index slumped to 53.1 from 58.2 in April, the lowest since February 2021, as Britain's economy felt the hit from accelerating inflation.
USD/INR movement
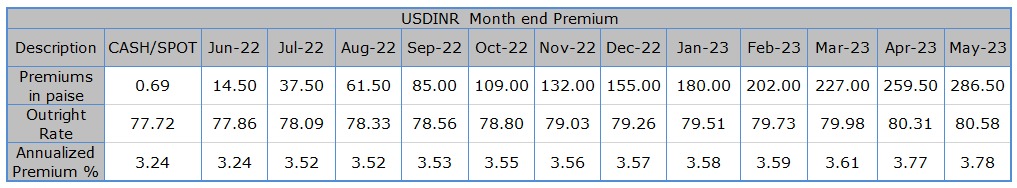
The USDINR pair made a gap up opening at 77.72 and traded within the range of 77.68-77.73. The pair closed the day at 77.71 levels. The USDINR pair traded in a tight range ahead of a monetary policy decision by the Reserve Bank of India which is due for tomorrow. Surging crude prices, foreign fund outflows, broad dollar strength and firm US bonds is expected to keep the Indian rupee under pressure.
Global currency updates
The EURUSD pair shed ground for the third session in a row and pushes further south of the 1.0700 mark in the first half of the week, in response to the selling pressure in the risk-associated universe. The GBPUSD pair has managed to erase a portion of its daily losses after having touched its weakest level since May 19 earlier in the day. The pair stays under modest bearish pressure near 1.2500 in the European trading hours. The USDJPY continues to trend higher and posted new 2022 high at 133.00. Weak Japan’s household spending data signaled that rising costs hit consumers more than expected, contributing to fresh yen’s weakness, along with comments from top officials which add to expectations that the Bank of Japan is unlikely to change its ultra-loose monetary policy in the short term.
Bond market
U.S. Treasury yields were slightly lower as investors continue to assess inflation. Economic data releases today will include April’s balance of trade reading, while the Fed remains quiet during its blackout period. Investors are still trying to determine whether a recent resurgence in stocks is a bear market rally or a sign that the year’s risk asset sell-off has bottomed. The yield on 10-year benchmark rose to 7.518% as compared with 7.501% at close in the previous trading session. India's benchmark 10-year bond yield rose to its highest levels in three years ahead of RBI policy announcement due tomorrow.
Equity market
Indian equity benchmarks Sensex and Nifty 50 extended losses to a third straight day amid weakness across most sectors, as concerns persisted among investors globally on inflation and aggressive hikes in COVID-era interest rates. Financial, IT, media and consumer durable shares were the biggest drags on headline indices. Broader markets also weakened, with the Nifty midcap 100 and Nifty smallcap 100 indices falling around half a percent each. All eyes were on the outcome of a key RBI policy meeting due this week.
Evening sunshine
"Focus to be on the US Trade Balance and Treasury Secretary Yellen Speech."
European stocks slipped into negative territory amid nervousness over inflation and ahead of ECB monetary policy meeting at the end of this week. The U.K.’s market reaction amid political turbulence in the country was limited today after U.K. Prime Minister Boris Johnson survived a vote of confidence yesterday. U.S. stock index futures slipped on concerns over risks from rising inflation and the Federal Reserve's plan to further raise interest rates.
Author

Abhishek Goenka
IFA Global
Mr. Abhishek Goenka is the Founder and CEO of IFA Global. He pilots the IFA Global strategic direction with a focus on relentlessly improving the existing offerings while constantly searching for the next generation of business excellence.
















